
By Jon Merwin, Founder and CEO
Home · Flood · Condo · Renters · Umbrella · Auto · All of New Hampshire
- Portsmouth Atlantic Insurance is an independent New Hampshire home insurance agent based in Portsmouth, and we insure homes in every part of the state.
- We compare 40+ carriers for homeowners, condo, renters, flood, umbrella and auto. We charge no fees.
- Where you live changes the questions to ask: Nor’easters and tidal flooding on the Seacoast, finished basements in the southern tier, empty seasonal homes in the Lakes Region, long fire-response distances up north.
- New Hampshire law does not require homeowners insurance, but most mortgage lenders do, and a standard homeowners policy leaves out flood.
- Find your county and town below, or check any agent’s New Hampshire license through the NAIC lookup.
Looking for a New Hampshire home insurance agent who can do more than a basic home and auto bundle? Portsmouth Atlantic Insurance is an independent agency, founded in 2005 and licensed in 10 states. We are New Hampshire’s highest-rated agency on Google, with 1,000+ Google reviews and over 2,000 testimonials. Because we don’t work for one insurance company, we compare 40+ carriers for your home first, then your cars, umbrella, flood and valuables. Our office is in Portsmouth, and our clients live all over the state, from Rye and New Castle to Bedford, Hanover and the shores of Lake Winnipesaukee. Most reviews happen by phone or email, so distance from Portsmouth doesn’t matter.
This page covers what a New Hampshire homeowners insurance agency should look at for your house, how coverage needs change by county and town, what owners of larger homes should ask, and how to check that any agent is properly licensed. For a full walkthrough of coverage options and carriers, see our guide to New Hampshire home insurance.
What a New Hampshire home insurance agent should do for you
A homeowners policy is only as good as the numbers on the declarations page. When we review a New Hampshire home, we start there:
- A dwelling limit based on the cost to rebuild, not what you paid for the house or its assessed value, with extended replacement cost where a carrier offers it.
- Deductibles you can live with, including any separate wind or named-storm deductible, shown in dollars rather than only as a percentage.
- Water coverage that matches the house: water backup for a finished basement, and a separate flood policy where the address calls for it.
- Liability limits that line up across the home, the cars and an umbrella, so there are no gaps between policies.
- Ordinance or law coverage on older homes that would need code upgrades after a loss.
As an independent agent, we can put the same house in front of several carriers and show you the differences in coverage side by side, and you deal with the same Portsmouth team at renewal and at claim time.
Does it matter where in New Hampshire you live?
Yes. Every New Hampshire home gets Nor’easters, ice dams and long heating seasons, but each region adds its own risks. Use the table below as a starting point before your review.
| Region | Example towns | Risks worth a closer look | Ask your agent about |
|---|---|---|---|
| Seacoast | Portsmouth, Rye, New Castle, Hampton, Exeter | Nor’easters, storm surge, tidal and coastal flooding, wind on exposed lots, older homes in historic districts | Flood (NFIP and private), wind or named-storm deductibles, replacement cost for historic finishes |
| Merrimack Valley & southern tier | Bedford, Manchester, Amherst, Hollis, Windham, Hudson | Larger suburban homes, finished basements, sump and sewer backup, teen drivers | Water backup limits, extended replacement cost, umbrella limits |
| Lakes Region | Wolfeboro, Alton, Gilford and other Lake Winnipesaukee towns | Seasonal homes left empty in winter, frozen pipes, docks, boats and guests | Vacancy or unoccupancy terms, water-shutoff devices, boat and umbrella coverage |
| Upper Valley & Monadnock | Hanover, Keene | River flooding, older farmhouses, wood stoves, outbuildings | Flood outside mapped zones, coverage for barns and other structures, heating system details |
| White Mountains & North Country | Second homes and ski-area properties | Long fire-response distances, heavy snow loads, rentals to visitors | How distance to a fire station and hydrant affects your options, roof and snow-load questions, short-term rental terms |
If you own a condo, start with the association’s master policy, because it decides how much of the unit you need to insure yourself. Our guide to condo insurance in New Hampshire explains how an HO-6 fits with it.
Seacoast homes: Nor’easters, flood and wind
All of New Hampshire’s Atlantic coastline sits in Rockingham County, and coastal storms are part of owning a home there. In January 2024, two storms a few days apart pushed seawater over Route 1A and into Hampton Beach streets; on January 13 the New Hampshire Department of Transportation told the public to avoid Route 1A in Hampton, North Hampton and Rye because of the high tide. Storms like that are why we ask Seacoast owners three things at every review:
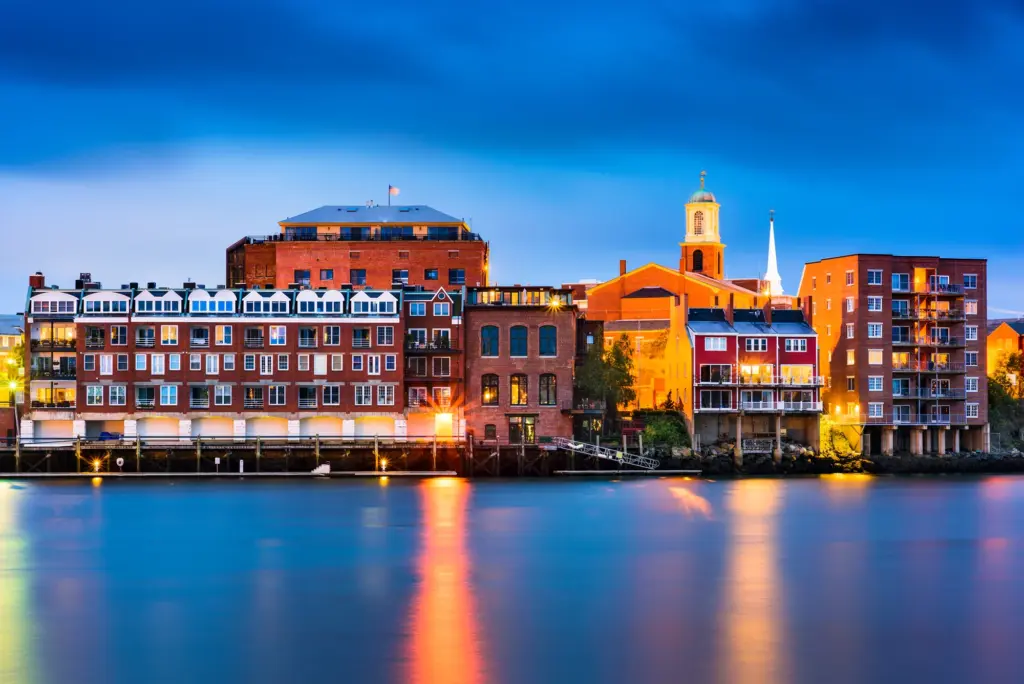
- Do you have flood coverage, and is it enough? Surge and rising water are flood, which a homeowners policy excludes.
- What is your wind or named-storm deductible in dollars? Many coastal policies carry one, separate from the all-perils deductible.
- Is the roof ready? Wind-driven rain, ice dams and fallen limbs after a Nor’easter are usually homeowners claims, subject to your deductible and policy terms, and roof age matters to carriers.
See our pages on coastal home insurance in New Hampshire and homeowners insurance in Portsmouth, NH, or the Rockingham County page for every Seacoast town.
Do you need flood insurance in New Hampshire if you’re not on the coast?
Often, yes. Standard homeowners policies exclude flood, and flooding in New Hampshire isn’t limited to the coast. Snowmelt, heavy rain and rivers like the Merrimack, the Lamprey and the Connecticut can reach homes outside mapped flood zones. You can check your property on FEMA’s Flood Map Service Center.
- NFIP through Selective. We write National Flood Insurance Program policies through Selective. New NFIP policies generally have a 30-day waiting period before they take effect (see FloodSmart for the exceptions), so buy before storm season, not when a storm is in the forecast.
- Private flood. When a home needs more than the NFIP offers, or coverage the NFIP leaves out, we compare Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Each one underwrites address by address.
- Elevation certificates. If you have one, send it. A raised house, raised mechanicals or flood vents can change how flood carriers look at a home.
For a closer look, read our guide to flood insurance in New Hampshire. If you’re near the water in Rye, Hampton or New Castle, our page on coastal home insurance in New Hampshire covers tidal and surge flooding. In Strafford County, see new FEMA flood maps for Dover, Durham and the Piscataqua watershed.
What should high-value homeowners in New Hampshire ask an insurance agent?
A standard homeowners policy is built for an average house. A custom build on the Seacoast, a renovated Bedford colonial or a lake house with a boathouse usually needs more than that. Bring these questions to any agent you’re considering. Live in Portsmouth? See our guide to homeowners insurance in Portsmouth, NH.
- Is my dwelling limit based on the real cost to rebuild? Ask for a current replacement-cost estimate, and ask whether extended or guaranteed replacement cost is available on your home.
- How are jewelry, art, wine and collections handled? Standard policies cap certain categories. Scheduling items, or adding a separate valuables policy, can remove those caps.
- What happens if water backs up or a pipe freezes? Water backup coverage is often an add-on, and seasonal homes may have vacancy terms that change what’s covered.
- Is my liability protection in line with what I own? An umbrella policy sits above your home, auto and watercraft liability. It matters more if you have a pool, a dock, a boat or snowmobile trails crossing your land.
- Do I need flood coverage, and how much? Flood is excluded from standard homeowners policies, and NFIP building limits may not cover a high-value home on their own.
- Can one carrier write the whole household? Putting the home, second home, cars and umbrella with one high-value carrier can simplify claims and help avoid gaps between policies.
Learn more on our high net worth insurance and high-value home insurance in New Hampshire pages, or see how these questions apply on the coast on our high-value home insurance in Portsmouth page.
Want to see how coverage changes as home values climb? Our guides walk through insuring a $2 million, $3 million, $4 million, $5 million and $10 million home in New Hampshire. If you also own luxury or collector cars, see our page on high-value auto insurance in New Hampshire.
Own a home anywhere in New Hampshire? Ask for a homeowners coverage review. Talk to our Portsmouth team: (603) 431-4020, use the form below or start on our quotes page.
Which insurance companies can a New Hampshire independent agency compare?
We work with 40+ carriers. Under about $2 million in dwelling coverage, nearly all of them are in play, and Openly and National General can fit homes up to about $5 million. From about $2 million to $3 million, Hanover is often a fit; Andover writes up to about $1.5 million in New Hampshire, or about $1 million for homes far from a fire hydrant or fire station. Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. For flood, we offer NFIP policies through Selective and private flood from Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge.
There isn’t one “best” insurance company for every New Hampshire home. Which carrier fits depends on the home’s age, construction, location, claims history and the limits you need, and each carrier makes its own underwriting decisions. Our job is to show you what each option covers so you can compare them properly. See our full carrier list. If a carrier has non-renewed your home, see our guide to non-renewed and hard-to-place home insurance.
What New Hampshire clients say they value
We read every review and survey comment. A few themes come up again and again:
- Fast, clear answers. Clients mention quick replies by phone and email, and explanations of the options that make sense the first time.
- Patience with questions. First-time buyers and long-time owners both describe being walked through their choices, then left to pick what fits.
- Help with harder homes. Several clients bought older houses that needed work and say we found them a place to land.
- One place for the household. People like having home, flood, liability and auto handled together, and having us move several policies over at once.
- Support after a claim. Long-time clients mention being treated professionally when they had a claim, not just at the sale.
Read them in our clients’ own words on our client feedback page.
How do you check that an insurance agent is licensed in New Hampshire?
The New Hampshire Insurance Department licenses insurance producers, and you can look up any agent or agency through the NAIC State Based Systems license lookup (choose New Hampshire). The lookup shows whether the license is active and which lines of authority it covers. Before you choose an agent, also ask:
- Is the agency independent or captive? An independent agency can quote several carriers; a captive agent represents one company.
- Which carriers do you use for homes like mine?
- Who handles my account day to day, and who do I call when I have a claim?
- How often will you review my coverage as my home and assets change?
Why New Hampshire homeowners choose Portsmouth Atlantic Insurance
- Independent since we were founded in 2005, with access to 40+ carriers and no fees.
- New Hampshire’s highest-rated agency on Google, with 1,000+ Google reviews and over 2,000 testimonials. Read them on our client feedback page.
- Licensed in 10 states, which helps if you own a second home in another state.
- A local team in Portsmouth. Meet our team.
New Hampshire insurance by county and town
We work with homeowners across the state. If you want to sit down with an insurance agent in Portsmouth, NH, start with our office page. Each town page below has local details on flooding, storms, older homes and the questions to ask.
Rockingham County (Seacoast and southern tier)
Start with our Rockingham County, NH home insurance page. Towns: Atkinson, Auburn, Brentwood, Candia, Chester, Danville, Deerfield, Derry, East Kingston, Epping, Exeter, Fremont, Greenland, Hampstead, Hampton, Hampton Falls, Kensington, Kingston, Londonderry, New Castle, Newfields, Newington, Newmarket, Newton, North Hampton, Northwood, Nottingham, Plaistow, Portsmouth, Raymond, Rye, Salem, Sandown, Seabrook, South Hampton, Stratham and Windham. For larger homes, see our high-value pages for Atkinson, Kensington, Brentwood, Newington, South Hampton and Auburn.
Strafford County (Dover, Durham and the Great Bay and Salmon Falls towns)
Towns: Barrington, Dover, Durham, Farmington, Lee, Madbury, Middleton, Milton, New Durham, Rochester, Rollinsford, Somersworth and Strafford.
Hillsborough County (Manchester, Nashua and the southern tier)
Towns: Amherst, Bedford, Brookline, Goffstown, Hollis, Hudson, Litchfield, Manchester, Merrimack, Mont Vernon, Nashua, New Boston, Pelham and Weare.
Merrimack County (Concord and the capital region)
Towns: Allenstown, Andover, Bow, Concord, Dunbarton, Henniker, Hooksett, Hopkinton, Loudon, Northfield, Pembroke and Warner. For larger homes near Concord, see our high-value pages for Bow, Hopkinton and Dunbarton.
Belknap County (Lakes Region)
Towns: Alton, Barnstead, Belmont, Gilford, Laconia and Meredith.
Carroll County (Lake Wentworth, Squam, Ossipee and the eastern Lakes Region)
Towns: Brookfield, Effingham, Moultonborough, Sandwich, Tuftonboro, Wakefield and Wolfeboro. If your lake house sits empty for part of the year, see our guide to second home insurance in New Hampshire.
Grafton and Cheshire Counties (Upper Valley, White Mountains and Monadnock)
Towns: Hanover, Holderness, Lyme and Sugar Hill (Grafton County) and Keene (Cheshire County).
Don’t see your town? We still write policies there. See all of our locations and service areas. Insuring a home in Connecticut? See our Connecticut insurance agency page.
How a New Hampshire home quote works
- Tell us about the house: address, year built, square footage, roof age and updates to wiring, plumbing and heating.
- Send your current declarations page so we can compare like for like and flag limits that look short.
- We shop the carriers that fit and lay the options side by side, with the differences in coverage, deductibles and storm terms, not just the bill.
- You choose, and we handle the switch, including your mortgage company and the effective date, so there is no gap.
Want the whole picture, from the first conversation through onboarding and your annual review? See our process, step by step.
Sources
- New Hampshire Insurance Department, "Producers/Adjusters FAQ" (license verification)
- NAIC State Based Systems, "Lookup"
- FEMA, "FEMA Flood Map Service Center"
- FloodSmart (NFIP), "Floodsmart | The National Flood Insurance Program"
- FloodSmart, buying a flood policy
- NHDOT, "Heavy Rain and a High Tide to Bring Flooding to the NH Coastal Roads" (January 2024)
Get a New Hampshire home insurance quote
Tell us about your home and we’ll compare our carriers and follow up with options, including flood and umbrella if you need them. We charge no fees. Request a quote. There’s no obligation to buy. Prefer to talk? Call (603) 431-4020.
Frequently asked questions
Do you insure homes everywhere in New Hampshire?
Yes. We are licensed statewide and insure homes from the Seacoast to the Lakes Region, the Upper Valley and the North Country, from our Portsmouth office at 601 Islington St. Most reviews happen by phone or email. Call (603) 431-4020.
What is the difference between an independent and a captive insurance agent?
A captive agent represents one insurance company. An independent agency like Portsmouth Atlantic Insurance works with many carriers, 40+ in our case, so we can compare coverage from several companies for the same home.
Is homeowners insurance required by law in New Hampshire?
No. New Hampshire law does not require homeowners insurance, but most mortgage lenders require it for as long as you have a loan. Even with the mortgage paid off, it protects what is usually your largest asset and your personal liability.
Does homeowners insurance cover flooding in New Hampshire?
No. Standard homeowners policies exclude flood, including storm surge on the Seacoast. Flood coverage comes from a separate NFIP or private flood policy, and NFIP policies generally have a 30-day waiting period before they take effect.
How do I check that an agent is licensed in New Hampshire?
Use the NAIC State Based Systems license lookup and choose New Hampshire. It shows whether the license is active and which lines of insurance the agent is authorized to sell.
Which insurance companies do you use for high-value homes in New Hampshire?
Under about $2 million in dwelling coverage, almost all of our 40+ carriers can fit, and Openly and National General can reach about $5 million. From about $2 million to $3 million, Hanover is often a fit, and Andover writes up to about $1.5 million (about $1 million for homes far from a fire hydrant or fire station). Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. Which carrier fits depends on the home, its location and the coverage you need.
Do you charge fees?
No. We don’t charge fees on any policy we write.
Jon Merwin, Founder and CEO · Portsmouth, NH
By Jon Merwin, Founder and CEO. Portsmouth Atlantic Insurance is an independent agency founded in 2005. Meet our team.