
By Jonathan Merwin, Founder and CEO, Licensed Insurance Advisor
If you own a home on the New Hampshire Seacoast, two things decide most of your insurance questions: wind and water. A nor’easter can damage a roof and push seawater into the street on the same day, and a homeowners policy treats those two losses very differently. This page explains how coastal homeowners insurance works in Portsmouth, Rye, New Castle, Hampton, North Hampton and Seabrook, and how to put the pieces together.
Portsmouth Atlantic Insurance is a family-owned independent agency founded in 2005, based at 601 Islington Street in Portsmouth. We compare home coverage from 40+ carriers, write flood insurance, and charge no agency fees. We’re New Hampshire’s highest-rated agency on Google, with 1,000+ Google reviews and over 2,000 testimonials.
What makes a Seacoast home “coastal” to an insurer
Insurers look at distance to the water, elevation, flood zone, roof age and construction, and how the home is protected from wind. The state’s science panel found that the largest storm surges recorded at Fort Point since 2003 came from nor’easters, not hurricanes (NH Coastal Risks and Hazards Commission science panel report (2014)), and Portsmouth’s hazard plan notes that nor’easters can occur in any month (City of Portsmouth Hazard Mitigation Plan Update (2024 draft)). So coastal risk on the Seacoast is a year-round question, not just a hurricane-season one.
Where surge and tidal flooding hit the Seacoast
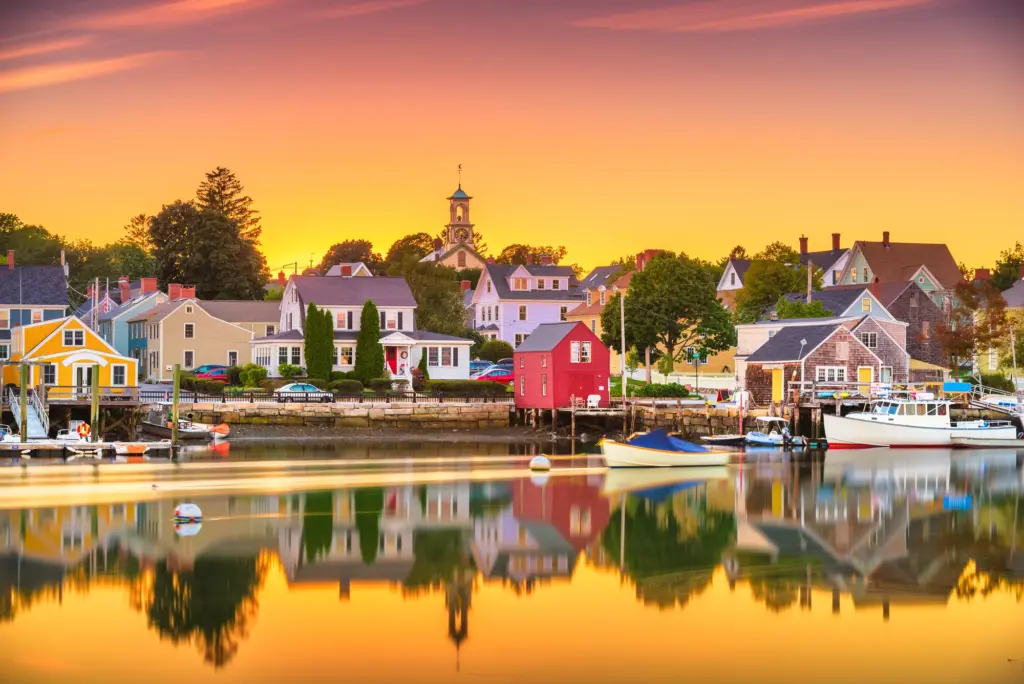
New Hampshire’s ocean coast is short, but almost every mile of it is exposed in a different way. Open-ocean beaches take waves and overwash. The Piscataqua River, Little Harbour and the tidal creeks behind the beaches flood more slowly, as storm tides back up into low streets, marsh edges and basements. The same storm can hit a Route 1A beach house and a South End basement for very different reasons, which is why a flood policy has to be fitted to the specific address.
- Portsmouth: the city’s hazard plan points to the South End, North and South Mill Ponds, Peirce Island, Little Harbour and Sagamore Creek. Our Portsmouth flood insurance guide walks through each area and the city’s Extended Flood Hazard Area.
- New Castle: an island town at the mouth of the Piscataqua, with waterfront homes facing open water and a single road on and off. See our New Castle insurance agency page.
- Rye: the town’s floodplain rules cover coastal high-hazard Zone VE along with Zones A, AE and AO, and rebuilding rules are strictest in VE. See our Rye insurance agency page.
- North Hampton: Little Boar’s Head and the homes along Route 1A sit close to the ocean, often on high-value lots. See North Hampton home insurance.
- Hampton and Seabrook: Hampton Beach, North Beach and the Hampton-Seabrook Estuary combine beach exposure with low, marsh-edge neighborhoods. See flood insurance in Hampton, NH and Seabrook home insurance.
The current FEMA flood maps for coastal Rockingham County took effect on January 29, 2021, after an updated coastal flood study that used LiDAR elevation data (NH Department of Environmental Services). If you bought or last reviewed your flood coverage before then, your zone may have changed. You can look up an address on our flood zone check page.
Wind: what your homeowners policy covers
Wind damage to your roof, siding and windows is normally covered by a homeowners policy, subject to your deductible. Near the coast, many policies carry a separate wind or named-storm deductible, often a percentage of the dwelling limit rather than a flat dollar amount. On a $600,000 dwelling limit, for example, a 2% deductible means you pay the first $12,000 of a covered wind loss. Check your declarations page for the percentage and what triggers it.
Rain that gets in because the wind first damaged the roof or a window is usually covered. Rain that seeps in without that kind of opening often is not. Keeping the roof in good shape, securing outdoor furniture and having a generator are the simplest ways to cut the risk.
Hurricane, named-storm and wind/hail deductibles are not the same thing
Coastal policies can use different triggers, and the wording matters more than the percentage. Read your declarations page and endorsement for which of these applies:
- Hurricane deductible: usually applies only when the National Weather Service has named a hurricane, often within a set window before and after landfall or a watch or warning.
- Named-storm deductible: can also apply to tropical storms that never reach hurricane strength.
- Wind/hail deductible: applies to any windstorm or hail loss, including a nor’easter that never gets a name. On the Seacoast, this is the one that tends to catch people off guard, because the largest recorded storm surges here have come from nor’easters, not hurricanes.
Ask us to translate the percentage into dollars for your dwelling limit, and to compare carriers that use a flat-dollar or lower-percentage option for your address. Some carriers require a wind/hail deductible on homes near the ocean, so the deductible is often part of what makes a coastal home insurable at all.
Ice dams and winter water damage
Nor’easters bring snow as well as wind. When snow melts on a warm roof and refreezes at the colder eaves, it can form an ice dam that backs water up under the shingles and into ceilings and walls. Most standard homeowners policies cover the resulting water damage, though removing the ice itself and fixing a worn-out roof usually aren’t covered. Burst pipes are generally covered if the heat was kept on or the system was drained, which matters for seasonal Seacoast homes that sit empty over the winter. Our guide to snow and ice damage insurance covers the details, and our post on leaving a Seacoast property empty explains vacancy rules.
Water: flood is a separate policy
Homeowners policies exclude flood, including storm surge and rising tidal water. Flood coverage comes from the National Flood Insurance Program (NFIP) or a private flood carrier. NFIP building coverage is capped at $250,000 and contents at $100,000 (FloodSmart.gov (NFIP)), and new NFIP policies generally have a 30-day waiting period unless an exception applies, such as a policy bought with a new mortgage (FloodSmart.gov, Buy a policy).
- NFIP: we write National Flood Insurance Program policies through Selective, a Write Your Own carrier. Coverage terms are set by FEMA.
- Private flood: we compare Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Some private options offer higher building limits, replacement cost on contents or shorter waiting periods, depending on the property.
- Excess flood: sits above an NFIP policy for homes that would cost more than $250,000 to rebuild.
Look up your address in the FEMA Flood Map Service Center. For details by town, see our Seacoast NH flood insurance page.
Wind vs. flood: how one storm becomes several claims
Here is how a typical nor’easter loss on the Seacoast can split up. The coverage depends on the cause of each part of the damage, not on the storm itself:
- Shingles torn off and a window blown in: homeowners policy, subject to the wind or wind/hail deductible.
- Rain driven in through that broken window: usually homeowners, as part of the same wind loss.
- Storm tide or waves pushing water into the basement and first floor: flood policy (NFIP or private), with its own deductible.
- Sewer or drain backup from overwhelmed storm drains: depends on the cause. FEMA notes that an NFIP policy can cover a sewer backup caused by a flood, but not one caused by clogged pipes. Otherwise it falls to a water backup endorsement on the homeowners policy.
- A dock, seawall or landscaping damaged by waves: often limited or excluded under both policies.
Because each piece can carry its own deductible, it’s worth reviewing the whole set together, before storm season, with someone who can see both the homeowners and flood policies.
NFIP vs. private flood on the Seacoast
NFIP rates are set by FEMA, and every NFIP provider charges the same rate for the same home (FloodSmart.gov, What you need to know about buying flood insurance). The choice that matters is whether an NFIP policy, a private policy, or both fit the house. A few NFIP limits come up often on the Seacoast:
- Building coverage tops out at $250,000 and contents at $100,000, which is below the rebuild cost of many oceanfront homes.
- Personal property kept in a basement is not covered, and neither are decks, patios, fences, landscaping or temporary living expenses while the home is repaired.
- New policies generally have a 30-day wait. The main exceptions are a policy bought when you make, increase, extend or renew a mortgage, and a policy bought within 12 months of a map change that newly puts the home in a high-risk zone.
Private flood can fill some of those gaps, depending on the carrier and the property: higher building limits, loss-of-use coverage, or a shorter waiting period. Not every private carrier will write every coastal address, and terms change, so we quote NFIP through Selective and compare private options side by side. For homes worth more than the NFIP limit, excess flood can sit on top. Our Seacoast flood insurance guide goes deeper on both.
Elevation certificates and flood zone changes
An elevation certificate shows how high your building sits compared with how high floodwaters are expected to reach, including the first-floor height and whether there’s a basement. FEMA says most homeowners don’t need one to buy flood insurance, but homes in high-risk Zone A or coastal Zone V may need one, and it can identify discounts (FloodSmart.gov, Get an elevation certificate). Your town’s floodplain manager may already have one on file. If not, a licensed land surveyor, engineer or architect can complete one.
If you believe your home was mapped into a Special Flood Hazard Area by mistake, for example because it sits on naturally high ground, you can ask FEMA for a Letter of Map Amendment (LOMA). If FEMA grants it, your lender may drop its federal flood insurance requirement (FEMA, Change your flood zone designation). Even then, many Seacoast owners keep a flood policy, because storm tides don’t stop at a map line.
Town by town
Portsmouth
Older homes in the South End and along the waterfront bring both flood exposure and rebuild costs for period details. See Portsmouth homeowners insurance and, for larger homes, Portsmouth high-value home insurance.
Rye
Rye regulates FEMA flood Zones A, AE, AO and VE, and homes in Zone VE that are substantially damaged must be rebuilt elevated on pilings or columns (Town of Rye floodplain management ordinance). That can make ordinance or law coverage especially important. See our Rye agency page, homeowners insurance in Rye, NH and Rye high-value home insurance.
New Castle
New Castle is made up entirely of islands, and Route 1B is the only access and the sole evacuation route (Town of New Castle Master Plan report). Protecting the house before a storm matters because getting to it afterward can take time. See New Castle high-value home insurance, and for harbor-side flood questions, our Portsmouth flood insurance guide, which also covers Little Harbour and the back channels.
Hampton and Seabrook
Beach cottages, year-round homes and summer rentals sit close together near the water. Rental use and seasonal vacancy can change which policy fits, so tell us how the home is used. See our guide to homeowners insurance in Hampton, NH, our Hampton insurance agency page, Hampton flood insurance and, if you rent the home by the week, short-term rental insurance in Hampton. In Seabrook, see Seabrook Beach and estuary home insurance.
North Hampton
Little Boar’s Head and the estates along Route 1A combine ocean exposure with high rebuild costs, so dwelling limits, wind deductibles and flood limits all deserve a close look. See North Hampton home insurance and North Hampton high-value home insurance.
Own on another coast too?
Many Seacoast clients also own on a neighboring shore. See coastal home insurance in Massachusetts, coastal home insurance in Connecticut, or, just across the bridge, York and Kittery, Maine. We’re licensed in 10 states: Maine, New Hampshire, Vermont, Massachusetts, Rhode Island, Connecticut, New York, Florida, Ohio and Illinois.
Which carriers fit a coastal home
It depends mostly on the home’s rebuild cost (Coverage A, which you can rough out with our replacement cost estimator) and how close it is to the water:
- Under about $2 million: most of our 40+ carriers are options. Cincinnati, a high-value carrier that writes homes at any dwelling limit, usually wants at least about $150,000 in dwelling coverage. Coastal appetite varies by carrier and changes over time, so we check current availability for each address.
- About $2-3 million: Hanover is among the options (Andover writes up to about $1.5 million, or about $1 million for homes far from a fire hydrant or fire station), along with Openly and National General up to about $5 million. For coastal primary homes in New Hampshire, Hanover can write up to $2 million in dwelling coverage through its Prestige and Platinum programs, subject to underwriting review.
- Larger homes: Cincinnati and Chubb write homes at any dwelling limit. For the largest homes, both typically inspect inside and out, and water-leak detection is usually required.
For larger homes, see our New Hampshire high-value home insurance hub, Rye high-value home insurance and Portsmouth high-value home insurance. For a standard home anywhere in the state, start with homeowners insurance in New Hampshire.
Setting the right dwelling limit on the coast
Rebuilding near the water often costs more than rebuilding the same house inland. Older Portsmouth homes have period trim, plaster and slate that are expensive to match. In Zone VE, a substantially damaged home may have to be rebuilt higher on pilings or columns, and the code upgrades that come with that are paid by ordinance or law coverage, not the base dwelling limit. Market value and assessed value don’t measure any of this, so we set Coverage A from a rebuild estimate. Our home replacement cost estimator gives you a starting range before we talk.
A coastal homeowner’s checklist
- Know your wind or named-storm deductible in dollars.
- Check your flood zone and decide on flood coverage before storm season, allowing for the waiting period.
- Set the dwelling limit from a rebuild estimate, and add ordinance or law coverage.
- Ask how docks, seawalls and boathouses are covered; they are often limited or excluded.
- Add water backup coverage for finished basements.
- Keep an elevation certificate on file if you have one, or ask your town’s floodplain manager whether one exists.
- Know which deductible applies to a nor’easter (wind/hail) and which applies only to a named hurricane.
- Clear gutters and add attic insulation and ventilation to cut the risk of ice dams.
- Add a personal umbrella and separate boat insurance if you keep a boat.
Get your quote
Tell us about the house and we will follow up with options. About 90% of our quotes go out within 24 hours, and we don’t charge any fees. Our Portsmouth office at 601 Islington Street is open Monday to Thursday 9 AM to 5 PM and Friday 8 AM to 4 PM. Prefer to talk? Call (603) 431-4020 or use our quote page.
Frequently asked questions
Does homeowners insurance cover storm surge on the Seacoast?
No. Storm surge is flood, which homeowners policies exclude. You need an NFIP or private flood policy.
What is a wind or named-storm deductible?
A separate deductible some coastal policies apply to wind or named-storm damage, often a percentage of the dwelling limit. Check your declarations page for the percentage and trigger.
How long does flood insurance take to start?
New NFIP policies generally take 30 days to start unless an exception applies, such as a policy bought with a new mortgage. Some private flood policies have shorter waiting periods.
Who writes NFIP flood policies at Portsmouth Atlantic?
We write NFIP policies through Selective, a Write Your Own carrier, and also compare private flood from Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Not sure where your home sits? Check your flood zone by address.
Will insurers write a home right on the water?
Often, yes, but appetite varies by carrier and changes over time. Comparing many carriers matters more on the coast than inland.
Do I need an elevation certificate for a Seacoast home?
Most homeowners don’t need one to buy flood insurance, but homes in high-risk Zone A or coastal Zone V may need one, and it can identify discounts. Ask your town’s floodplain manager whether one is already on file.
Does a hurricane deductible apply to a nor’easter?
Usually not. A hurricane deductible normally applies only to a named hurricane. A wind/hail deductible, if your policy has one, can apply to any windstorm, including a nor’easter. Check your declarations page for which one you have.
Does homeowners insurance cover ice dam damage?
Most standard homeowners policies cover the water damage an ice dam causes inside the home. Removing the ice and repairing an old or worn roof usually aren’t covered. See our snow and ice damage guide.
Do you charge agency fees?
No. We do not charge agency fees on any policy, including home, auto, flood and umbrella.
By Jonathan Merwin, Founder and CEO, Licensed Insurance Advisor
Family-owned since 2005, with 1,000+ Google reviews and over 2,000 testimonials. Meet our team.