
By Jon Merwin, Founder and CEO, Licensed Insurance Advisor
Darien is a small town that insures like three different ones. South of I-95, Tokeneke, Noroton and Long Neck Point face the Sound. Along the Post Road and around the two train stations are older houses, condos and the town’s few apartment buildings. In the north, two-acre lots, longer driveways and private wells take over. A good Darien policy starts with which of those places the house is in.
We are Portsmouth Atlantic Insurance, a family-owned independent agency founded in 2005 and licensed in 10 states. Darien homeowners, condo owners and landlords use us to compare home, flood, auto, collector car and umbrella coverage from 40+ carriers. We serve Connecticut from our Fairfield office at 1885 Post Road and by phone, email and online. Request a quote. There’s no obligation to buy. Questions? Call (203) 859-6858.
New Hampshire’s highest-rated agency on Google · 1,000+ Google reviews and over 2,000 testimonials.
Key takeaways
- Darien is overwhelmingly owner-occupied, single-family housing, and much of it is either pre-war or postwar, with heavy renovation since.
- Renovations, additions and teardowns are where coverage gaps open most often: tell your carrier before the work starts.
- North Darien relies partly on private wells and volunteer fire departments; the shoreline relies on flood insurance.
- Flood is always a separate policy. Our Darien flood page covers the shoreline and rivers in depth.
Darien housing at a glance
The Census Bureau’s Vintage 2025 estimates put Darien at about 22,600 residents. Of about 7,200 occupied homes in the 2020–2024 American Community Survey, close to 6,000 are owned and about 1,300 rented. About 6,500 of the town’s 7,700 housing units are detached single-family houses; buildings of five or more units hold roughly 640, and two- to four-unit buildings about 310 (table B25024).
Age is the bigger story. About 2,100 units were built in 1939 or earlier and about 2,200 more in the 1940s and 1950s, so well over half of Darien’s homes are at least 65 years old, according to table B25034. Roughly 1,600 were built between 2000 and 2019. The town’s 2021 hazard mitigation annex warns that much of the town was built before today’s wind provisions, leaving roofs and windows on older houses more exposed in a strong storm.
Neighborhood by neighborhood
Tokeneke, Long Neck Point, Noroton Bay and Contentment Island
The shoreline neighborhoods carry the town’s highest flood and wind exposure. The annex lists coastal flooding at Holly Pond, Contentment Island Road and through Tokeneke, and counts 30 of Darien’s 55 repetitive flood loss properties along the shoreline. Tokeneke is zoned largely for one-acre lots, and many of its houses are large, custom and expensive to rebuild. For these homes we look closely at the dwelling limit, the named-storm deductible, roof and window protection, and how private or excess flood sits on top of NFIP coverage. Our Darien flood insurance page walks through each shoreline area and river.
Long Neck Point, the Noroton Neck shore and the small islands off Tokeneke take the Sound head on. The annex warns that a 100-year storm with one foot of sea level rise could flood much of Noroton Neck, Tokeneke Park, Hay Island, Butlers Island and Colyer Point at the western end of Contentment Island. It notes that many low-lying houses that flooded in Sandy have since been elevated or are being elevated, that Pear Tree Beach now floods regularly at high tide, and that a main sewer pumping station near Weed Beach came close to going under in Sandy. Connecticut plans for about 50 centimeters, roughly 20 inches, of sea level rise by 2050, using UConn’s CIRCA projection.
For shoreline houses we also look at how the house would be lived in after a storm: whether the drive or the road floods first, where the family would stay during repairs, and whether loss-of-use limits are high enough for a long rebuild in a town with few rentals.
Noroton, Noroton Heights and the Post Road
The western part of town and the Post Road corridor have Darien’s denser housing: older colonials and capes on smaller lots, condos near the stations, and several newer mixed-use projects. Heavy rain is the bigger water issue here. The annex names the Boston Post Road at Hecker Avenue, Leroy Avenue and Raymond Street at the railroad underpasses, and the neighborhood next to Town Hall as places that flood, sometimes enough to reroute emergency vehicles. Water backup coverage and a sump with battery backup earn their keep in these basements.
Historic homes cluster along the Post Road. The Boston Post Road Historic District has 23 contributing buildings, including a row of 12 nineteenth-century houses and the Bates-Scofield House. Older houses anywhere in town benefit from extended replacement cost and ordinance or law coverage, and from a policy that pays to match original materials.
North Darien
The northernmost areas are zoned for two-acre lots, and the annex notes that some northern properties rely on private wells because public water mains do not reach them. Darien’s fire service is all volunteer, with three departments: Darien, Noroton and Noroton Heights. For new construction where mains are absent, Darien asks builders to supply firefighting water, and it can require sprinklers on sites that trucks have trouble reaching. The annex also flags the northern stretches as the part of town where small wildfires are a concern. Northern neighborhoods can also see more snow than the shoreline.
Expect an underwriter to ask how far the nearest hydrant is, whether alarms are monitored for fire and freezing, whether there are sprinklers, how the house is heated and whether a fire truck can get up the drive. Private association roads are a liability and access question too; the annex notes that some associations do not keep up drainage, which can lead to washed-out or blocked roads.
The Five Mile River and the Goodwives
The Five Mile River forms Darien’s eastern border with Norwalk’s Rowayton, and the Goodwives River and Stony Brook run through the middle of town to Gorhams Pond and the harbor. Houses near any of them can take water from rain as well as tide, which is why we review flood coverage with every Darien home near a stream, mapped zone or not.
The Five Mile River has the largest watershed of the four that drain Darien, though only a small part of it lies inside town; the rest of the water comes from upstream before it reaches the harbor between Darien and Rowayton. The annex maps an AE zone along the river. Near the mouth, a high tide can meet heavy rain coming down the river, so a house set back from the water can still see it in the yard or the basement.
Many Five Mile River owners keep a boat at a dock or mooring nearby. Docks and boathouses usually fall under the other-structures part of a homeowners policy, with limits that may not fit a substantial dock, and the boat itself belongs on its own boat policy, not the homeowners. Tell us about the dock, the lift and the boat together so nothing falls between policies.
Renovations, additions and rebuilds
With so many older houses on valuable lots, Darien sees constant construction. That is where we see the most avoidable gaps:
- Raising the dwelling limit when an addition, a finished basement or a new kitchen adds rebuild cost. A limit set before the project will fall short after it.
- Vacancy during a gut renovation. Many policies restrict coverage when a house is unoccupied for an extended period. Tell the carrier, and add a renovation endorsement or move to builder’s risk for a full rebuild.
- Contractor insurance. Get a certificate of insurance from every contractor before work begins, naming you where possible.
- Flood rules. In a mapped flood zone, a large enough project can bring the whole house under current elevation standards. Check with the town first, and see our flood page for how the NFIP treats elevated houses.
Home coverage from cape to estate
Rebuild cost drives the dwelling limit, not purchase figure or assessment. On a renovated 1920s colonial or a newer shingle-style house in Darien, that number deserves a fresh estimate every few years. Most Darien houses have plenty of options. Our Connecticut homeowners carriers are Vermont Mutual, Andover, Providence Mutual, Liberty Mutual, Hanover, Foremost, Openly, Stillwater, Cincinnati and National General. Cincinnati usually wants at least about $150,000 in dwelling coverage.
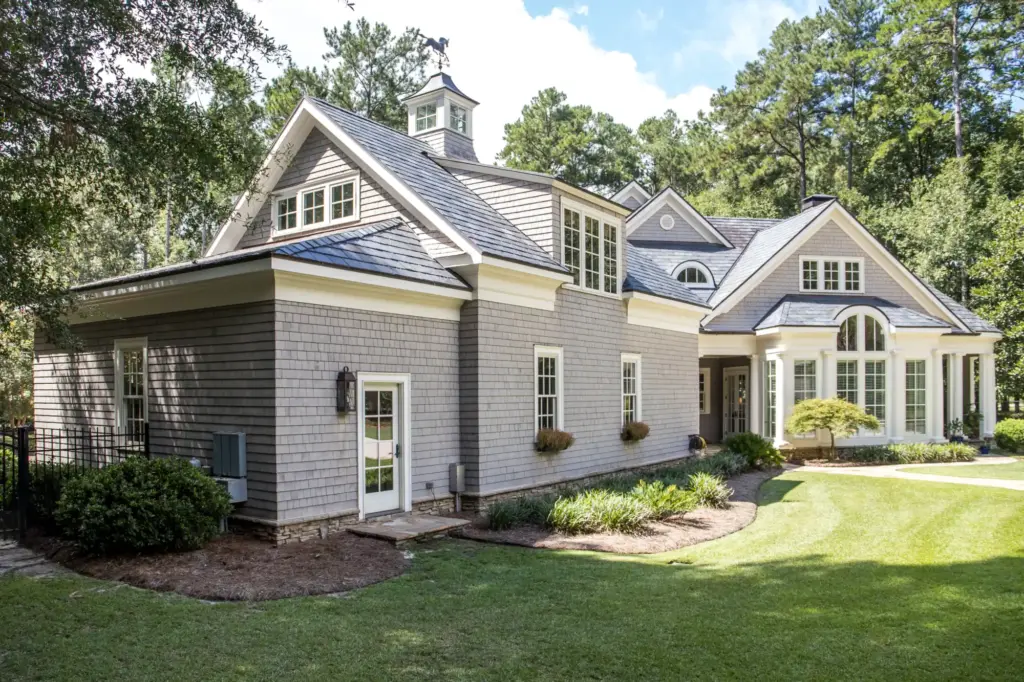
For bigger houses, Openly and National General handle homes to roughly $5 million. Cincinnati and Chubb are two similar high-value carriers that compete with each other and write homes at any dwelling limit, which is why we quote both. Our Darien high-value home insurance page compares how those carriers handle replacement cost, cash settlement, outbuildings and valuables, and the Greenwich, Darien and Westport luxury home article adds context.
Coverage we review on most Darien homes
- Water damage and leak detection. Houses empty during the commute or a winter trip benefit from automatic water shut-off valves and monitored low-temperature sensors, which many carriers favor.
- Generators and equipment breakdown, since the annex points to downed trees and power outages as the main storm risk.
- Scheduled jewelry, art, wine and collections with current appraisals.
- The named-storm deductible, explained in our hurricane deductible article.
Flood in Darien, briefly
The annex records 55 repetitive flood loss properties in Darien, 45 of them residential: 30 on the shoreline, seven each on Stony Brook and the Noroton River, two on the Goodwives River, and the rest outside mapped flood zones. Mapped AE zones follow the Noroton River, Stony Brook, the Goodwives River, Tokeneke Brook and the Five Mile River. Look up your house on the FEMA Flood Map Service Center.
Darien flood zones, in plain terms
- VE zones run along the open Long Island Sound shoreline. FEMA defines them as coastal areas with a 1% or greater annual chance of flooding plus storm waves, and puts the odds of a flood there at about one in four over a 30-year mortgage.
- AE zones sit behind the VE line on the shore and follow the Noroton River, Stony Brook, the Goodwives River, Tokeneke Brook and the Five Mile River, with base flood elevations set.
- A zones mark areas that store floodwater but have no base flood elevation set, the annex says.
- Zone X is lower risk, not no risk: nine of Darien’s 55 repetitive loss properties sit outside mapped flood zones.
Darien has been in the NFIP since January 2, 1981, and its flood maps were last revised in 2013. The town builds in one foot of freeboard above the base flood elevation and runs an online Darien Flood Hazard Mapper, according to the annex. The NFIP caps a home policy at $250,000 for the building and $100,000 for contents, and a new NFIP policy generally takes effect 30 days after purchase unless an exception applies, such as buying it with a new or refinanced mortgage (FloodSmart).
Selective is where we place new NFIP policies, and we also compare private and excess flood from Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. For a shoreline home, the federal building limit rarely covers rebuild cost, so excess flood is often part of the plan. The full story, from Noroton Neck to Tokeneke Park, is on our Darien flood page and the Fairfield County flood guide.
Condos and rentals
Darien has relatively few condos and apartments, mostly along the I-95 and Post Road corridor. Unit owners should line up their HO-6 with the association’s master policy and deductible; boards can read our guide to Connecticut condo association insurance. Renting out property in Darien? Rentals up to four units belong on a landlord form, and we place them with Hanover, Liberty Mutual, Vermont Mutual, Andover, Foremost and Providence Mutual. See our landlord insurance page, and ask tenants for renters insurance.
Cars, teen drivers and umbrellas
Darien drivers split their miles among I-95, the Merritt, the Post Road and the station lots. We quote auto insurance alongside your home so liability limits line up, and classic cars go on an agreed-value collector car policy. Adding a teen driver is the moment to revisit limits.
Pools, trampolines, boats, frequent guests, domestic employees and young drivers all raise liability exposure. A personal umbrella sits on top of your home, auto and watercraft policies, and the underlying limits must match what the umbrella carrier requires.
What to have ready
- The address, year built, size, and any guest house, pool house or detached garage.
- Updates to the roof, heating, electrical and plumbing, and any renovation planned or underway.
- Whether you have public water or a well, plus your alarm, sprinkler, generator and leak-protection setup.
- Any elevation certificate and current flood declarations.
- Current policies for the house, cars, umbrella, valuables and any classic car, and a five-year claims history.
Neighboring towns have their own pages: New Canaan, Stamford and Greenwich. For the wider region, start with Fairfield County or our Connecticut agency page.
Clients have given us 1,000+ Google reviews and over 2,000 testimonials, and we are New Hampshire’s highest-rated agency on Google. A sample is on our client feedback page.
Request a Darien quote
40+ carriers · New Hampshire’s highest-rated agency on Google · 1,000+ Google reviews and over 2,000 testimonials.
Fill in the form below or visit our quote page. We will match the house to the carriers that fit and send you options. Request a quote. There’s no obligation to buy. Rather talk? Call (203) 859-6858.
Jon Merwin, Founder and CEO, Licensed Insurance Advisor
Frequently asked questions
Do you have an office in Darien?
We serve Connecticut from our Fairfield office at 1885 Post Road and by phone, email and online. Darien clients can reach us at (203) 859-6858 or through the quote form on this page.
What should I tell my insurer before a Darien renovation or teardown?
Tell us before work starts. A house that will be empty or gutted may need a vacancy or renovation endorsement, or a builder’s risk policy for a full rebuild. Contractors should carry their own insurance, and the dwelling limit should be raised when the project adds space or finishes.
Does it matter if my north Darien house is on a well?
Carriers ask about water supply because it affects firefighting. Darien’s fire departments are volunteer, and some northern properties have no public water mains. A monitored fire alarm, sprinklers, and a clear, plowed driveway help. We will ask about them on the application.
Which carriers write larger Darien homes?
Up to roughly $5 million, Openly and National General are strong fits. Cincinnati and Chubb are two similar high-value carriers that compete with each other and write homes at any dwelling limit, which is why we quote both. Cincinnati usually wants at least about $150,000 in dwelling coverage.
Is flood covered on my homeowners policy?
No policy for a house covers flood from the Sound, the rivers or heavy rain. That takes a separate NFIP policy, which we place through Selective for new policies, or private and excess flood from Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge.
My Tokeneke or Noroton Neck house is in a VE zone. What does that change?
FEMA uses VE for coastal areas with a 1% or greater annual chance of flooding plus the added hazard of storm waves. Lenders require flood insurance on mortgaged buildings in these zones, building rules for new and substantially improved homes are stricter, and Darien adds one foot of freeboard above the base flood elevation. An elevation certificate is the key document for the quote.
I live on the Five Mile River but outside the mapped zone. Do I need flood insurance?
It is worth a hard look. The river’s mapped AE zone follows the channel, but the annex counts nine Darien repetitive loss properties outside mapped flood zones, and tide and heavy rain can meet near the mouth. Flood coverage outside high-risk zones is often easier to place, and we can compare NFIP and private options.
Can you insure a Darien condo or a rental?
We do both. For a condo, the HO-6 should fill whatever the association’s master policy leaves out. For rentals of up to four units, we compare landlord forms from Hanover, Liberty Mutual, Vermont Mutual, Andover, Foremost and Providence Mutual.
How do I get started?
Upload or describe your current coverage in the form below, or phone (203) 859-6858. Request a quote. There’s no obligation to buy.
Sources
- U.S. Census Bureau, Vintage 2025 Connecticut town population estimates
- U.S. Census Bureau, ACS five-year 2020–2024, B25003 (Darien town)
- U.S. Census Bureau, ACS five-year 2020–2024, B25024 (Darien town)
- U.S. Census Bureau, ACS five-year 2020–2024, B25034 (Darien town)
- WestCOG Hazard Mitigation Plan, Darien municipal annex (August 2021)
- FEMA Flood Map Service Center
- FEMA glossary, Zone VE and V1-30
- FloodSmart (NFIP), Buy a policy: coverage limits and waiting period
General information for Darien, Connecticut homeowners and drivers, not a quote, an insurance contract or legal advice. What a policy pays depends on its wording, endorsements and the carrier’s underwriting. Local figures come from the sources above and may change.