
High-value homesHigh net worthMasterpieceAll 10 PAI states
By Jon Merwin, Founder and CEO, Licensed Insurance Advisor
Reviewed by Jon Merwin, Founder and CEO, Licensed Insurance Advisor
Key takeaways
- Chubb traces its roots to 1882 in New York. It began serving high net worth clients in personal lines in 1976 and launched its Masterpiece policy in 1986.
- AM Best rates Chubb’s insurance subsidiaries A++ (Superior), affirmed January 16, 2026, with a stable outlook.
- Chubb homeowners coverage includes extended replacement cost, a cash settlement option after a covered total loss, risk consultant home assessments and a deductible waiver on large losses in most states.
- Portsmouth Atlantic writes Chubb in all 10 states where we are licensed, and Chubb writes homes at any dwelling limit.
- Chubb also offers valuables, flood, equipment breakdown, yacht, classic car and umbrella coverage, so many families can bring their high-value risks to one insurer.
Is Chubb a good choice for a high-value home? For many high-net-worth families in New Hampshire, Massachusetts, Connecticut and Maine, it is one of the first carriers we quote. AM Best rates Chubb A++ (Superior), Chubb has built its personal insurance around high net worth clients for decades, and it writes homes at any dwelling limit. Portsmouth Atlantic Insurance represents Chubb from our office in Portsmouth, NH, and we write it in all 10 states where we are licensed. This is our independent agent’s view of what Chubb does well, who it fits and what to ask before you switch.
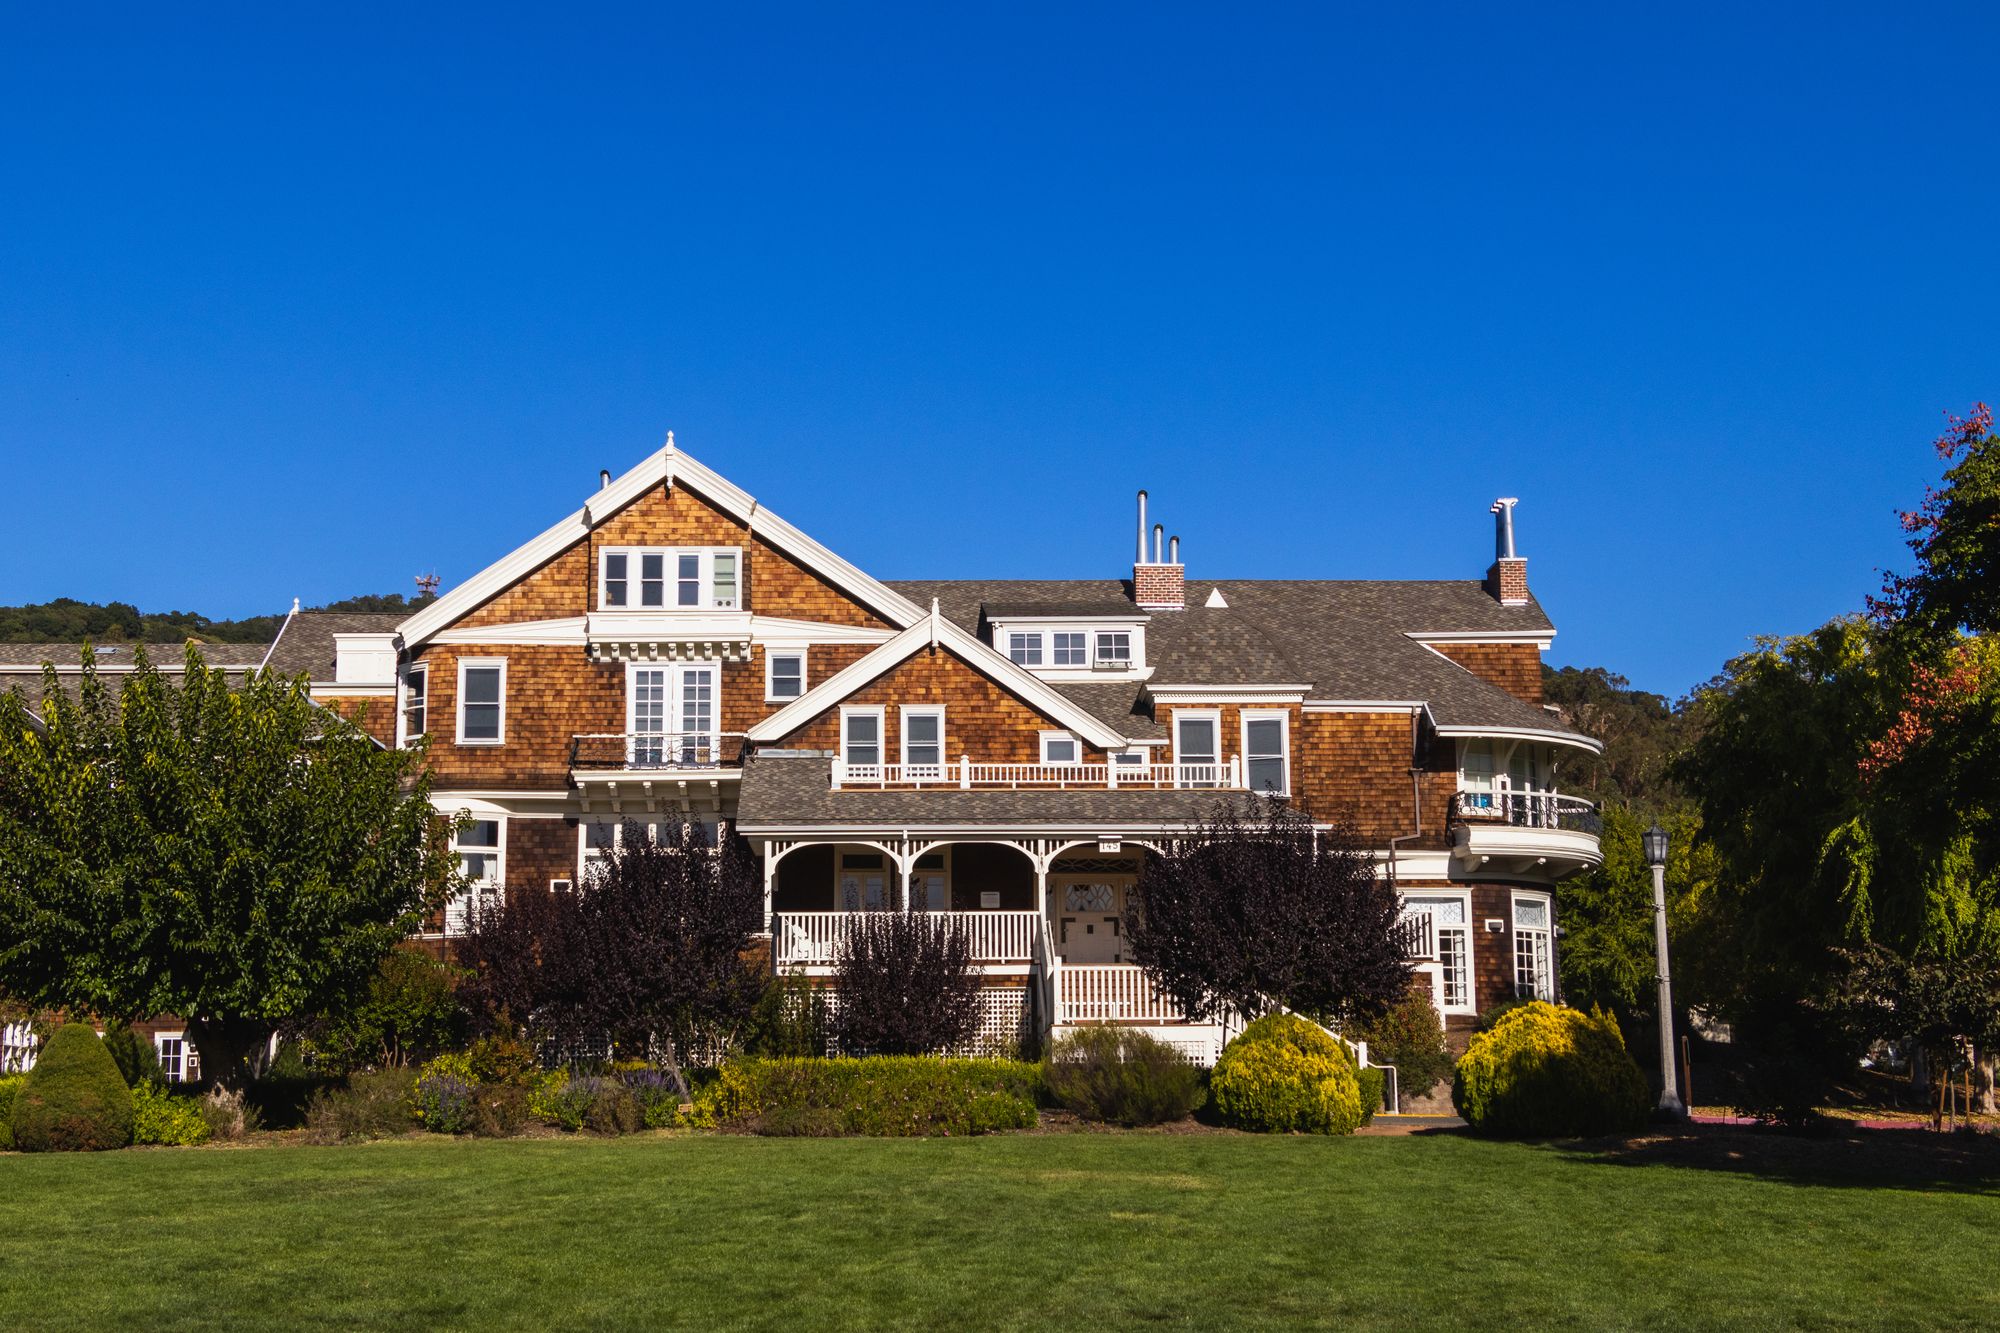
Who is Chubb?
The Chubb Corporation dates to 1882, when Thomas Caldecot Chubb and his son Percy opened a marine underwriting business in New York City’s seaport district. In 1976, Chubb began focusing its personal lines on high net worth clients. In 1986, it launched the Masterpiece policy, which Chubb calls the company’s definitive high net worth product (Chubb, history).
Chubb took its present form in 2016, when ACE Limited acquired the Chubb Corporation and the combined company kept the Chubb name. Chubb’s history page also notes that after Superstorm Sandy it settled the largest number of claims in company history (Chubb, history).
Chubb sells personal insurance through independent agents and brokers (Chubb homeowners insurance). That is how we place it for our clients.
What is Chubb’s AM Best rating?
AM Best rates the grouped insurance subsidiaries of Chubb Limited A++ (Superior) for financial strength, its highest rating, with long-term issuer credit ratings of aa+ (Superior). AM Best affirmed those ratings on January 16, 2026, with a stable outlook. AM Best assessed Chubb’s balance sheet strength as strongest and named Chubb a market leader in U.S. personal lines insurance for high-net-worth customers (AM Best, January 16, 2026).
Founded in New York
Chubb began as a marine underwriter in New York City’s seaport district.
AM Best A++ (Superior)
Affirmed January 16, 2026, with a stable outlook.
Masterpiece launched
Chubb’s high net worth personal lines policy.
All 10 PAI states
We write Chubb in every state where we are licensed.
Where does Portsmouth Atlantic write Chubb?
We write Chubb in all 10 states where we are licensed. Chubb writes homes at any dwelling limit, so there is no home too large for us to quote with Chubb, though every home still goes through Chubb’s underwriting.
New Hampshire and Maine
On the Seacoast and around the lakes, many high-value homes are coastal or seasonal, often with custom finishes, boats and collections. That mix suits Chubb’s home, valuables and yacht coverage. Chubb is also one of our Maine property carriers.
Massachusetts
Massachusetts has many older and historic high-value homes. Chubb’s historic home guidance and its focus on replacement cost make it a strong fit for houses with plaster, millwork and slate that cost more to restore.
Connecticut
In Fairfield County and along the shoreline, Chubb is often part of the conversation for larger homes, flood exposure and collections. We work with Connecticut homeowners by phone, email and online.
What is Chubb Masterpiece?
Masterpiece is the name Chubb uses for its high net worth personal lines policy (Chubb, history). Chubb refers to Masterpiece Homeowners, Condominium, Co-op and Contents policies on its equipment breakdown page (Chubb, equipment breakdown), and to Masterpiece Yacht for boats 36 feet and longer (Chubb, yacht). The idea is one carrier for the home, its contents and the other assets a high-net-worth family owns.
What stands out in Chubb’s home coverage?
Chubb describes several features of its homeowners coverage that matter most for larger homes (Chubb homeowners insurance):
Extended replacement cost
After a covered loss, Chubb will pay to repair or rebuild your home to its original condition, even if the cost exceeds your policy limit, including upgrades required by modern building codes.
Cash settlement option
After a covered total loss, if you decide not to rebuild or to rebuild elsewhere, Chubb offers a cash settlement up to your policy limit.
Home assessments
A Chubb risk consultant visits the home to document its details and help set an accurate replacement cost.
Deductible waiver
In most states, if your base deductible is $50,000 or less and a covered loss exceeds $100,000, Chubb waives the deductible.
Chubb also says it replaces contents without deduction for depreciation up to your policy limit, including upgraded appliances based on the exact or latest model available. If you cannot live in the home after a covered loss, Chubb says it will help you find a comparable place to stay, such as a similar home in your school district if available. Its HomeScan service uses infrared technology to help find leaks, missing insulation and faulty electrical connections behind walls before they cause damage (Chubb homeowners insurance). The deductible waiver does not apply when a special deductible, such as a hurricane or vacant house deductible, applies.
Condo and co-op owners
Chubb condo and co-op coverage starts with a risk consultant review of your unit. It covers your belongings and the improvements you have made, such as countertops, cabinets and flooring. In select states, extended replacement cost covers the difference if rebuilding your unit costs more than your limit. Chubb automatically includes $50,000 for your share of a covered assessment for damage to common elements, with higher limits available. Chubb says its adjusters are trained to respond within 24 hours and, if a claim is approved, to pay within 48 (Chubb, condos and co-ops).
Older and historic homes
Chubb’s guide for older and historic homes recommends checking whether a policy lets you restore with materials of like kind and quality, covers required code upgrades and lets you choose your own contractor, architect or engineer. It points to knob-and-tube wiring, plaster moldings, custom millwork, slate and copper roofing and historic district review boards as reasons these homes cost more to restore (Chubb, guide to older and historic homes).
Seasonal and second homes
Many of our Chubb clients own a lake house or a coastal second home that sits empty for weeks at a time. Chubb’s guidance on unoccupied and vacant homes explains the difference: a furnished home you leave for a few weeks may be unoccupied, while a home that is empty of furniture and personal property for more than 30 days may be considered vacant. For cold climates, Chubb recommends keeping the heat at a steady temperature, draining or shutting off water lines, testing backup generators weekly and using a monitored fire and burglar alarm or a property manager (Chubb, vacant but protected). Those steps matter for New England winters.
Flood
Standard homeowners policies do not cover flood. Chubb offers Personal and Excess Flood Insurance to its homeowners policyholders, with up to $15 million in total property coverage for the home and contents, replacement cost on covered property and coverage for finished basements (Chubb, flood insurance). We also place flood through Selective for NFIP policies and through private flood carriers, so we can compare options for coastal and riverfront homes.
Equipment breakdown
If you have a Masterpiece Homeowners, Condominium or Co-op policy, Chubb offers equipment breakdown coverage for heating and cooling systems, appliances, water heaters, pool equipment, well pumps, generators and home automation and security systems. Essential coverage is available up to a $250,000 limit and Enhanced coverage up to $500,000 (Chubb, equipment breakdown).
How does Chubb handle auto?
Chubb says its auto coverage complements its homeowners coverage. After a covered accident, Chubb pays for original equipment manufacturer (OEM) parts, and its collision repair experts oversee repairs. Chubb clients can choose coverage where the car’s value is agreed before a loss, so a total loss pays that amount regardless of age or mileage. Rental cars have no per-day limit, up to $15,000 total (Chubb, car insurance). For collector vehicles, Chubb’s classic car coverage uses agreed value, lets you choose your repair shop and puts no mileage limit on hobby use (Chubb, classic car). Ask us whether Chubb auto fits your household alongside your Chubb home.
Other Chubb coverages for high-net-worth families
| Coverage | What Chubb says it offers |
|---|---|
| Jewelry and watches | Worldwide coverage for most losses with no deductible |
| Fine art | Most fine art losses covered with no deductible; appraisals required only for items valued at $500,000 or more; up to 150% of the itemized amount if market value has risen; new purchases covered for up to 90 days |
| Wine and spirits | Blanket or itemized coverage, including spoilage from loss of utility service or climate control breakdown |
| Yacht | Masterpiece Yacht for pleasure yachts 36 feet or longer, with the full agreed amount and no deductible on a total loss |
| Personal umbrella | Excess liability limits from $1 million to $100 million, worldwide, with defense costs included |
| Cyber | Protection against identity theft, hacking, cybercrime and cyberstalking |
Is your dwelling coverage keeping up?
Replacement cost is different from your home’s market value. Chubb defines it as the estimated amount needed to repair or replace your home with the same level of detail and finishes at today’s costs, including labor, materials and, when needed, architects and designers. Chubb says it draws on more than 1,000 contractor interviews a year and quarterly and annual regional cost reviews to set replacement costs (Chubb, home replacement cost).
We review dwelling limits with every Chubb client at renewal and after any renovation. Our guide to insurance on a $2 million home walks through how we think about it.
Expert tip
“With rising inflation, dwelling replacement costs have gone up, and the goalposts have shifted. The dwelling coverage a high-value home needs now is much higher than it was. The upside is that carriers are expanding their appetite for higher-value homes, so homeowners have more good choices.”
— Jon Merwin, Founder and CEO, Licensed Insurance Advisor, Portsmouth Atlantic Insurance
What to ask before you switch to Chubb
- What is the replacement cost after Chubb’s assessment? It may differ from your current dwelling limit, and that number drives the rest of the policy.
- Which items should be scheduled? Jewelry, art, wine and collections often need their own coverage beyond the home policy.
- Do you need flood or a higher umbrella? Coastal, riverfront and lake homes often do, and both can be reviewed at the same time.
- Does a special deductible apply? Wind, hurricane and vacant house deductibles work differently from your base deductible.
- Should your cars, boat and other homes move too? Keeping your high-value risks together can make coverage easier to manage, but we check each one on its own.
We go through these questions with every client before we recommend a change, and we compare Chubb with our other high-value carriers at the same time.
Who is Chubb best for?
- Owners of very large homes. Chubb and Cincinnati both write homes at any dwelling limit, so we quote both.
- Families with collections. Chubb’s jewelry, fine art and wine coverage is built for valuable collections.
- Owners of coastal and waterfront homes. Chubb’s flood insurance and yacht coverage can sit alongside the home policy.
- Owners of older and historic homes. Extended replacement cost and Chubb’s restoration focus fit homes that are costly to rebuild.
- Families with homes in several states. We write Chubb in all 10 states where we are licensed.
Get a Chubb quote for your high-value home
Tell us about your home, cars, valuables and boat, and we’ll compare Chubb with our other high-value carriers.
What are Chubb’s pros and cons?
| Pros | Things to know |
|---|---|
| AM Best A++ (Superior), affirmed January 16, 2026 | Chubb underwrites each home carefully and typically assesses it in person |
| Writes homes at any dwelling limit | Chubb is built for high-value homes, so for many average-size homes another carrier may be a better fit |
| Extended replacement cost and a cash settlement option | The deductible waiver does not apply when a special deductible applies, and terms vary by state |
| Valuables, flood, yacht and umbrella from one insurer | Coverage, forms and availability vary by state |
How do Chubb claims work?
Chubb takes claims 24 hours a day, 7 days a week. Its main claims number is 1-800-CLAIMS-0 (1-800-252-4670) (Chubb, report a claim). Chubb says it restores homes with attention to detail and craftsmanship, and for condo claims its adjusters are trained to respond within 24 hours (Chubb, condos and co-ops). If you insure with Chubb through us, call (603) 431-4020 and we will help you report the claim and follow it through.
Why we place high-value clients with Chubb
We place clients with Chubb when the home, its contents and the family’s other assets call for a carrier built around high net worth clients. Chubb’s replacement cost approach, home assessments and valuables coverage are why it is on our list for larger homes.
For a high-value home, the right carrier is the one that will rebuild it the way it was built. That is why we compare Chubb side by side with our other high-value carriers for every client.
Where Chubb fits among our high-value carriers
Portsmouth Atlantic works with 40+ carriers, so Chubb is one of several high-value options we compare.
| Carrier | Where it fits through Portsmouth Atlantic |
|---|---|
| Chubb | Homes at any dwelling limit, in all 10 states where we are licensed |
| Cincinnati | Homes at any dwelling limit, in all 10 states where we are licensed |
| Openly | Homes up to about $5M in NH, ME, MA, CT, OH and IL |
| National General | Homes up to about $5M |
| Andover | Homes up to $2M in CT, up to $2.25M in MA and up to $1.5M in NH |
| Hanover | Another high-value option we compare |
See our high-net-worth insurance page for how we insure larger homes and collections.
Frequently asked questions
Is Chubb a good insurance company for a high-value home?
For many high-net-worth families, yes. AM Best rates Chubb’s insurance subsidiaries A++ (Superior), affirmed January 16, 2026, and Chubb has focused on high net worth clients since the 1970s. Its homeowners coverage includes extended replacement cost, a cash settlement option after a covered total loss and home assessments by Chubb risk consultants. We still compare it side by side with our other high-value carriers.
What is Chubb Masterpiece?
Masterpiece is Chubb’s personal lines policy for high net worth clients. Chubb launched it in 1986 and calls it the company’s definitive high net worth product. Chubb uses the Masterpiece name across its homeowners, condominium, co-op, contents and yacht policies.
Does Chubb insure homes worth $10 million or more?
Yes. Chubb writes homes at any dwelling limit, and so does Cincinnati, so we quote both. Every home still goes through underwriting, and Chubb typically sends a risk consultant to assess the home.
Where does Portsmouth Atlantic write Chubb?
We write Chubb in all 10 states where we are licensed, including New Hampshire, Massachusetts, Connecticut and Maine. That helps families who own homes in more than one state.
Does Chubb waive the deductible on large losses?
Chubb says that in most states, if your base deductible is $50,000 or less and your covered loss is more than $100,000, it will waive the deductible. The waiver does not apply when a special deductible, such as a hurricane or vacant house deductible, applies, and terms vary by state.
How do I file a Chubb claim?
Chubb takes claims 24 hours a day, 7 days a week. Its main claims line is 1-800-CLAIMS-0 (1-800-252-4670). If you insure with Chubb through Portsmouth Atlantic, you can also call us at (603) 431-4020 and we will help you start the claim.
Related reading
- Coastal Home Insurance in Connecticut
- Luxury Home Insurance in Greenwich, Darien & Westport, CT
- Best High-Value Home Insurance Companies, Compared
- Top 10 Independent Insurance Agencies in NH & CT (Oct 2026)
- Coastal Home Insurance New Hampshire
- Coastal MA High-Value Home Insurance
- Darien CT Insurance Agency
- Greenwich CT Insurance Agency
- NH High-Value Home Insurance
- High-Value Home Insurance Portsmouth NH
- New Canaan CT Insurance Agency
- New Castle NH High-Value Home Insurance
- Insurance Agency Portsmouth NH
- New Hampshire Boat Insurance
- Rye NH High-Value Home Insurance
Sources
- Chubb, history
- AM Best, Chubb Limited ratings affirmed (Jan. 16, 2026)
- Chubb, homeowners insurance
- Chubb, home replacement cost
- Chubb, guide to older and historic homes
- Chubb, condos and co-ops
- Chubb, flood insurance
- Chubb, home appliance and equipment breakdown
- Chubb, car insurance
- Chubb, classic car
- Chubb, jewelry
- Chubb, fine art
- Chubb, wine and spirits
- Chubb, yacht
- Chubb, personal umbrella excess liability
- Chubb, cyber
- Chubb, report a claim
This review is general information, not a policy. Coverage, forms and availability vary by state and policy, and every policy is subject to underwriting. Your policy documents control.
Related carrier reviews: Cincinnati Insurance Review (2026) · Andover Companies Review (2026) · Openly Review (2026) · High-net-worth insurance
Compare Chubb Masterpiece for your home
We’ll quote Chubb and our other high-value carriers side by side and walk you through the differences.
Jon Merwin, Founder and CEO, Licensed Insurance Advisor
Jon founded Portsmouth Atlantic Insurance in 2005 in Portsmouth, NH. Our family-owned independent agency is licensed in 10 states and works with 40+ carriers, and we have earned 1,000+ Google reviews and over 2,000 testimonials. We don’t charge additional fees. Meet our team.