
Home · Second homes · Vermont
By Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance · Reviewed by Jon Merwin, licensed insurance agent
Published October 2026 · Updated October 4, 2026
- Portsmouth Atlantic Insurance is licensed in Vermont and insures year-round homes, ski houses and lake camps there.
- About 15 percent of Vermont housing units are seasonal or recreational homes, one of the highest shares in New England, per Census data.
- Homeowners policies exclude flood. After the July 2023 and July 2024 flood disasters, flood coverage is worth a hard look even away from rivers.
- Second homes need the right occupancy rating, a plan for winter vacancy and honest disclosure of any rentals.
- Rebuilding costs have climbed, so check that your dwelling limit reflects today’s rebuild cost, not what you paid.
Looking for Vermont homeowners or second-home insurance? Portsmouth Atlantic Insurance is licensed in Vermont, among 10 states, and has been insuring homes since 2005. We insure year-round houses, ski-country condos and homes, and lake camps across Vermont, including homes for families whose main house is in New Hampshire, Massachusetts or Connecticut. As an independent agency, we compare 30+ carriers instead of selling one company’s policy. That matters most for second homes, where the right fit depends on how often you’re there, who else uses the place, and how close it sits to a river or lake.
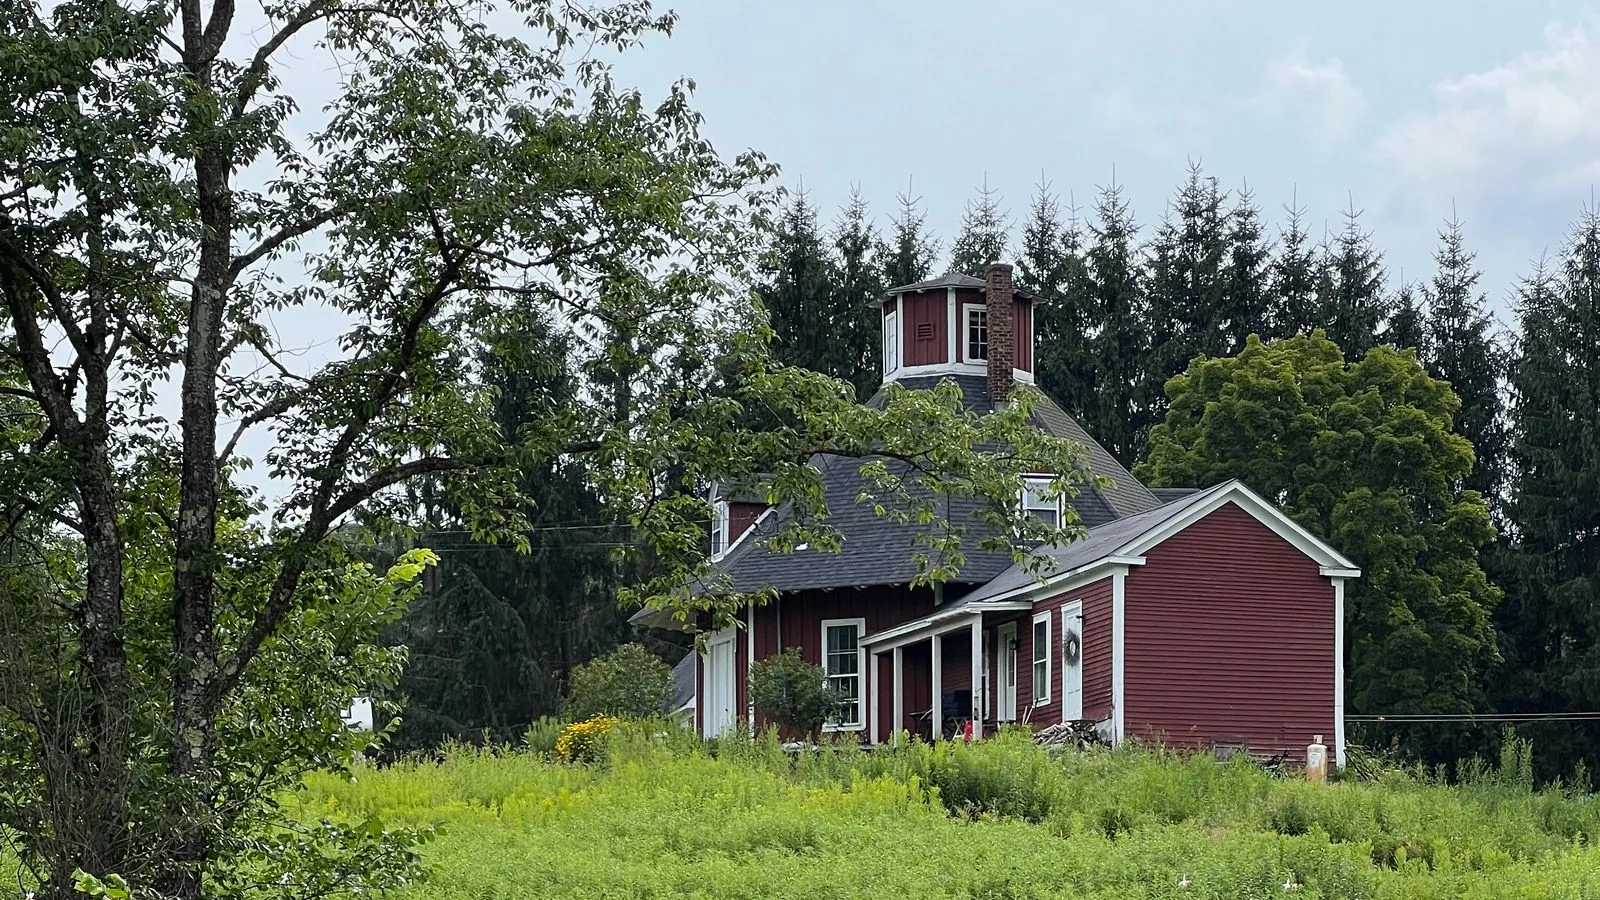
Can an agency based in New Hampshire insure my Vermont home?
Yes, as long as the agency holds a Vermont license. We do. Our Portsmouth, NH team works with Vermont homeowners by phone and email and handles renewals and claims support the same way we do for local clients. The Vermont Department of Financial Regulation suggests confirming that any company or agent you use is licensed in Vermont, which you can do through its Insurance Division.
How common are second homes in Vermont?
Very. In the Census Bureau’s 2019-2023 American Community Survey, about 15.1 percent of Vermont’s housing units were held for seasonal, recreational or occasional use. That compares with about 10.2 percent in New Hampshire and 1.8 percent in Connecticut. Within Vermont, the share runs highest in the islands of Lake Champlain, the Northeast Kingdom and the southern ski counties.
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, tables B25004 (vacancy status) and B25001 (housing units), from the ACS summary file. Our calculation: seasonal units divided by total housing units. Estimates have margins of error, so small differences between counties may not be meaningful.
Statewide, that’s roughly 50,700 seasonal homes, most of them empty for weeks or months at a time. That’s exactly what second-home policies have to plan for.
What does a Vermont second-home policy need to get right?
A second home can be insured well, but a few details decide whether a claim goes smoothly. Here’s what we review before we quote:
- Occupancy. The carrier needs to know this is a secondary or seasonal home, not your primary residence. Our second and seasonal home insurance guide explains the difference.
- Winter vacancy. Many policies limit coverage after a home has been empty for a stretch, especially for frozen pipes. The DFR recommends keeping the heat at 50 degrees or higher and insulating pipes. Our article on leaving a home empty covers what carriers expect.
- Rentals. If you rent the house during ski season or foliage weekends, the carrier has to know. Some policies allow occasional rentals; others need different coverage.
- Heating. Wood stoves, pellet stoves and backup generators are common in Vermont. Tell the carrier what you use, and keep chimneys and stoves serviced.
- Who checks on the house. A caretaker or neighbor who visits on a schedule, plus a low-temperature alert and water-leak sensors, can prevent the most common second-home claims.
“Inflation keeps moving the goalposts on dwelling replacement cost, and Vermont homes are no exception. Many of the houses we look at need far more dwelling coverage than they had a few years ago. The upside is that carriers are expanding their appetite for higher-value homes, so a well-kept ski house or lake home has more good options than it once did.”— Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance
Does homeowners insurance cover flooding in Vermont?
No. Flood is excluded from standard homeowners policies, whether the water comes from a river, a lake or heavy rain running off a hillside. The DFR’s homeowners and flood overview puts it plainly: every property has a flood risk, and both high-risk and lower-risk properties can buy NFIP flood insurance and may be able to buy private flood.
Vermont has seen why. FEMA declared major disasters for the July 2023 severe storms and flooding (incident period July 7 to 21, 2023) and for the July 9 to 11, 2024 severe storm and flooding. Vermont has no coastline. This was river and rainfall flooding, the kind a homeowners policy does not cover.
| Water damage | Generally covered by homeowners | Generally not covered | Ask about |
|---|---|---|---|
| Burst pipe from freezing | Yes, if sudden and accidental | If caused by neglect, such as leaving a vacant home unheated | Vacancy rules and low-temperature alerts |
| Ice dams | Yes, water damage from ice dams caused by ice and snow | Damage from poor maintenance | Roof condition and snow removal |
| Sump pump failure or sewer backup | No | Yes, unless you add it | Water backup and sump overflow endorsement |
| River, lake or surface-water flooding | No | Yes | NFIP or private flood policy |
| Slow leaks or seepage through the foundation | No | Yes | Maintenance and drainage fixes |
We write NFIP policies and also quote private flood through Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge where they’re available for the property. Private flood can offer higher limits or a shorter waiting period, but terms vary, so we compare them side by side. NFIP coverage generally starts 30 days after purchase unless an exception applies. More on our flood insurance page.
How much dwelling coverage does a Vermont home need?
Insure the cost to rebuild, not the market value. The DFR explains that most policies today pay on a replacement cost basis, without depreciation, up to your dwelling limit, but you generally have to rebuild to collect full replacement cost. If you don’t rebuild, you’re paid actual cash value. For an older farmhouse, a timber-frame ski house or a camp with a long gravel road, rebuild cost can be very different from what the house would sell for.
The DFR also suggests a home inventory and notes that jewelry, art, antiques and collections often need to be scheduled separately.
Which carriers insure higher-value Vermont homes?
For higher-value homes in Vermont, from ski houses to lake homes, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover. All six write in every state where we do business, including Vermont, and we place Cincinnati in all 10 of our licensed states across nearly all personal lines. For homes up to $5 million, we place only with Cincinnati, Chubb, Openly and National General. For homes of $10 million and up, we use only Chubb and Cincinnati.
We’ll review occupancy, flood and dwelling coverage and compare carriers for your Vermont home.
Talk to our Portsmouth team: (603) 431-4020 · Start a Vermont home insurance quote
What Vermont rules should homeowners know?
- Renewal notice. Under Vermont law, the insurer must give notice of its intent to renew, and the premium, 45 days before the policy expires.
- New policies. During the first 59 days of a new policy, a company may cancel for any reason. After that, it can cancel only for reasons such as nonpayment, fraud or a substantial increase in risk.
- Change in use. The DFR lists a change to a more hazardous use or a change in occupancy as examples of an increase in risk. Turning a family house into a full-time rental is the kind of change to tell us about first.
Can one agent cover my Vermont home and my home in another state?
Yes. Because we’re licensed in Vermont, New Hampshire, Massachusetts, Connecticut and Maine, among 10 states, we can coordinate both homes, your cars and one umbrella policy. Lining up the liability limits on every policy is what lets a single umbrella sit over all of them.
- The current declarations page for the Vermont home.
- How many months a year the house is occupied, and by whom.
- Any rental use, including short ski-season or foliage rentals.
- Heating type, including wood or pellet stoves and any generator.
- Distance to a river, stream or lake, and any existing flood policy.
Frequently asked questions
Can a New Hampshire insurance agency insure my Vermont home?
Yes, if the agency is licensed in Vermont. Portsmouth Atlantic Insurance is licensed in Vermont, among 10 states, so we can insure your Vermont house and coordinate it with your home in New Hampshire, Massachusetts or Connecticut.
Does homeowners insurance cover flooding in Vermont?
No. The Vermont Department of Financial Regulation notes that homeowners policies exclude flood. You need a separate NFIP or private flood policy. An NFIP policy generally takes effect 30 days after purchase unless an exception applies, such as a policy bought when you close on a mortgage.
Is ice dam damage covered on a Vermont homeowners policy?
Often, yes. The Vermont Department of Financial Regulation lists water damage from ice dams caused by ice and snow among the losses homeowners policies generally cover, while damage from poor maintenance or slow leaks is not. Raking snow off the roof and keeping gutters clear helps prevent ice dams.
What happens if my Vermont second home is empty all winter?
Many policies limit coverage when a home is vacant or unoccupied for a long stretch, especially for frozen pipes. Tell your agent how many months the house sits empty, keep the heat on, and have someone check it regularly.
How much notice does a Vermont insurer have to give before renewal?
According to the Vermont Department of Financial Regulation, an insurer must give notice of its intent to renew, and the premium, 45 days before the policy expires.
Sources
- Vermont Department of Financial Regulation, “Homeowner’s Insurance Guide”
- Vermont Department of Financial Regulation, “Homeowners and Flood Insurance Overview” (April 2026)
- FEMA, “Vermont Severe Storms, Flooding, Landslides, and Mudslides” (DR-4720)
- FEMA, “Vermont Severe Storm, Flooding, Landslides, and Mudslides” (DR-4810)
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25004 “Vacancy Status”
This page is general information, not a policy. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Your policy documents control.
Year-round house, ski house or lake camp, we’ll compare carriers and line it up with your other policies.
Talk to our Portsmouth team: (603) 431-4020 · Request a Vermont home insurance quote
Reviewed by Jon Merwin, licensed insurance agent
Portsmouth Atlantic has been an independent agency since 2005, is licensed in 10 states, works with 30+ carriers and has earned over 2,000 testimonials. Meet our team.