
Home · Coastal · Historic homes · Massachusetts
By Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance · Reviewed by Jon Merwin, licensed insurance agent
Published October 2026 · Updated October 5, 2026
- Portsmouth Atlantic Insurance is licensed in Massachusetts and insures homes in Newburyport, from High Street and downtown to the Newburyport end of Plum Island, from our Portsmouth, NH office.
- About 45 percent of Newburyport’s housing units were built in 1939 or earlier, per Census data, compared with about 31 percent statewide. Older homes make rebuild cost and ordinance or law coverage a priority.
- Many Massachusetts policies carry a separate wind or named storm deductible. The Division of Insurance says these usually run from 1% to 5% of the insured value of the home.
- Flood is excluded from homeowners policies. Parts of Plum Island and the Merrimack River shoreline are mapped in FEMA flood zones, so check the maps and consider NFIP or private flood.
- Short-term rentals in Newburyport need a city license, and the application asks for proof of liability insurance.
Looking for home insurance in Newburyport, Massachusetts? Portsmouth Atlantic Insurance is licensed in Massachusetts, among 10 states, and our Portsmouth office is a short drive up I-95 from Newburyport. We insure Federal-era houses on High Street, condos, year-round homes across the city and beach houses on Plum Island. As an independent agency, we compare 30+ carriers instead of selling one company’s policy. That matters in Newburyport, where the right carrier often depends on the age of the house, how close it sits to the water and whether it’s ever rented.
Can a Portsmouth agency insure a home in Newburyport, Massachusetts?
Yes. We hold a Massachusetts license, and we write a lot of Massachusetts business from our office on Islington Street in Portsmouth. You can work with us by phone, email or in person. We also insure homes in the towns around Newburyport, including Newbury, West Newbury, Amesbury and Salisbury. If you also own a home in New Hampshire or Maine, we can insure it too and line up the renewal dates. For statewide coverage notes, see our Massachusetts homeowners insurance page.
How old are Newburyport homes?
Older than most. In the Census Bureau’s 2019-2023 American Community Survey, about 45.0 percent of Newburyport’s 8,298 housing units were built in 1939 or earlier. Statewide, the figure is about 30.7 percent. All told, about 56.7 percent of Newburyport’s homes were built before 1960. Here’s the breakdown by decade.
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 (year structure built), from the ACS summary file. Our calculation: units in each period divided by total housing units. Estimates carry margins of error; for example, the 1939-or-earlier figure is 3,736 units, plus or minus 400. Very small bars are drawn at a minimum width so the label stays readable.
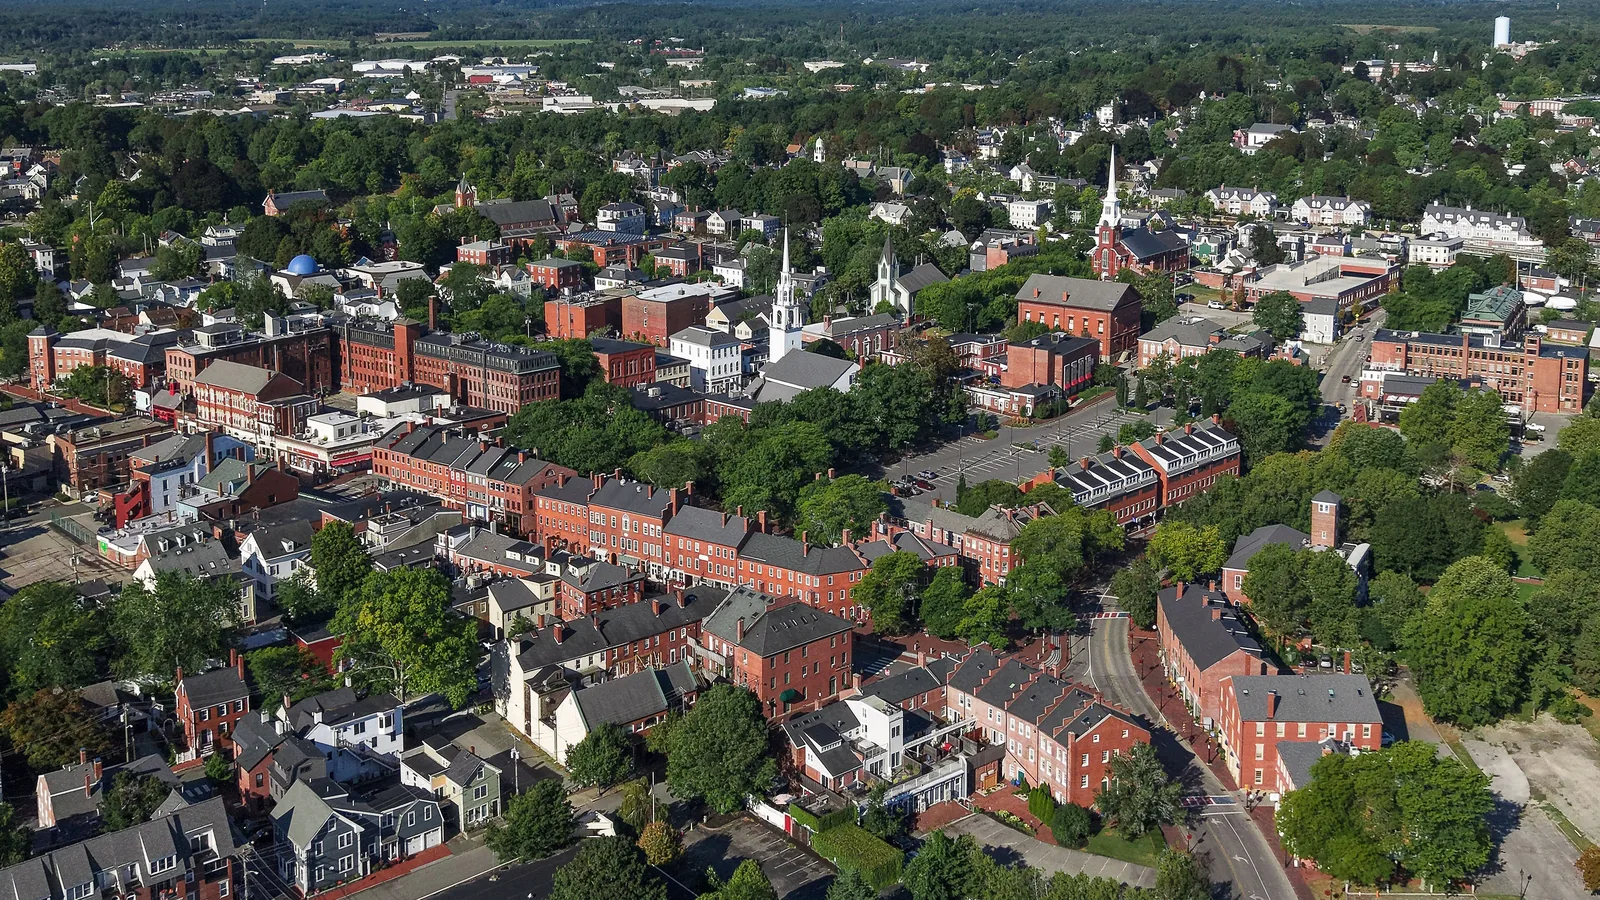
Much of that older housing sits in the Newburyport Historic District, which is listed on the National Register of Historic Places. The National Park Service describes it as roughly bounded by the Merrimack River, Plummer Avenue and Marlboro, Plummer, State and High Streets, with Federal, Greek Revival and Late Victorian architecture. High Street is lined with Federal-era homes. The city’s historic inventory form for one of them, the Pike-Cushing-Bachman House at 63 High Street, dates it to about 1810 and notes its roof balustrade, Palladian window and Ionic-columned portico, the kind of detail that is costly to rebuild.
What does an older Newburyport home change about coverage?
Three things matter most on an older Newburyport house:
- Replacement cost, not market value. Insure what it would cost to rebuild the house with similar materials and workmanship. The Massachusetts Division of Insurance (DOI) reminds homeowners that labor and construction costs have risen, so you may need to raise your dwelling coverage (Coverage A) to rebuild at today’s prices, and that additions and remodels can raise rebuilding costs too.
- Ordinance or law coverage. After a serious loss, rebuilding has to meet current building and floodplain rules. Ask how much the policy pays toward code upgrades, demolition of undamaged parts and the added cost of building to current rules.
- Local review before demolition. Newburyport’s demolition delay ordinance applies across most of the city and treats principal buildings 75 years or older, and buildings listed on the National Register, as historically significant. The Historical Commission can vote that a building should be preferably preserved and impose a delay. Inside the city’s Demolition Control Overlay District, demolishing more than 25% of the exterior walls of a building listed as contributing to the historic district requires a special permit from the Zoning Board of Appeals. Review like this can add time to a rebuild, so ask how long your policy’s additional living expense coverage lasts.
Updates matter as well. Tell us when the roof, heating, wiring and plumbing were last updated, because many carriers ask about those systems on older homes.
“Inflation keeps moving the goalposts on what it costs to rebuild, and older homes like the ones along High Street and down by the river feel it most. A lot of Newburyport homes need much higher dwelling coverage than they carried even a few years ago. The good news is that carriers are expanding their appetite for higher-value homes, so owners have more good choices than they used to.”— Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance
What does the Newburyport coast change about home insurance?
Wind is the first thing. The DOI says some Massachusetts policies have a special deductible that applies only when a named storm or wind causes damage. It is separate from the regular deductible, is usually a percentage of the home’s insured value, and generally ranges from 1% to 5%. It can also be a fixed amount, and it may apply per event, per season or per calendar year. On a larger home, a percentage deductible can be a meaningful number, so read the declarations page and ask us to translate it.
| Risk in Newburyport | Usually covered by homeowners | Usually not covered | What to ask |
|---|---|---|---|
| Wind damage to roof, siding or chimneys in a nor’easter | Yes | The part of the loss under your deductible | Is there a wind or named storm deductible, and is it per event, season or year? |
| Storm surge or high-tide flooding on Plum Island | No | Yes | NFIP or private flood policy |
| Merrimack River flooding | No | Yes | Flood zone, elevation certificate and flood policy |
| Frozen pipes in a closed-up second home | Often, if the home was heated or properly winterized | If vacancy rules or heating conditions were not met | Vacancy terms and low-temperature alerts |
| Sewer or drain backup | No | Yes, unless added | Water backup endorsement |
| Guest injured at a short-term rental | Depends on the policy and rental use | Often limited for regular rentals | Rental disclosure, liability limits and umbrella coverage |
Does homeowners insurance cover flooding in Newburyport or on Plum Island?
No. The DOI reminds homeowners that flood damage isn’t included in a standard home insurance policy, whether it comes from storm surge on Plum Island, a high tide along the waterfront or the Merrimack River. You can buy flood coverage from the National Flood Insurance Program (NFIP) or from a private insurer.
Newburyport’s flood maps were updated recently. The city’s floodplain rules now reference Essex County Flood Insurance Rate Maps dated July 8, 2025, covering zones A, AE, AH, AO, V and VE, including VE zones exposed to coastal wave action. The city’s planning office reported that the map tiles from Plum Island to downtown were not changed, while the flood zones grew slightly along the Merrimack River northwest of the Route 1 Gillis Bridge. Look up your address on FEMA’s Flood Map Service Center, and for homes near the water, ask whether an elevation certificate exists.
Plum Island, a barrier island that Newburyport shares with Newbury, has a long history of erosion. During a 2022-2023 U.S. Army Corps of Engineers harbor dredging project, sand was placed on Plum Island Beach just north of the South Jetty to protect the public beach, public infrastructure and private homes near an erosion hot spot, according to the city. If you own on the island, plan coverage with that history in mind.
- Waiting period. FloodSmart says NFIP coverage goes into effect 30 days after purchase, with exceptions, including a policy bought while making, increasing, extending or renewing a mortgage. If you’re buying in Newburyport, line up flood before closing.
- Program status. As of October 5, 2026, the Congressional Research Service reports that the NFIP is authorized through December 11, 2026.
- NFIP limits. NFIP building and contents limits are capped by federal rules and can fall short of the rebuild cost of a larger waterfront or historic home, so some owners add excess flood coverage or use a private flood policy.
- Private options. Private flood carriers we work with include Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Which ones can write a particular Newburyport home depends on the property.
Our flood insurance page explains the options in more detail.
We’ll compare carriers for wind, flood and older-home coverage and line it up with your other policies.
Talk to our Portsmouth team: (603) 431-4020 · Start a Newburyport home insurance quote
What if no insurer will write a Newburyport home?
Because we work with 30+ carriers, one decline doesn’t end the search. If no company in the regular market will write the home, the DOI says the market of last resort in Massachusetts is the Massachusetts Property Insurance Underwriting Association (MPIUA), known as the FAIR Plan. The DOI describes FAIR Plan coverage as basic property insurance. Like other home policies, it doesn’t cover flood, and as of 2025, new FAIR Plan policies for properties in Special Flood Hazard Areas in communities overseen by the Office of Coastal Zone Management also require a separate flood policy. Newburyport is one of the communities in that office’s North Shore region.
| FAIR Plan rule | What it says for a Newburyport home |
|---|---|
| Named storm deductible, within half a mile of the coast | At least 1% of the dwelling limit at lower dwelling limits, rising to 2% at higher limits |
| Named storm deductible, more than half a mile from the coast | A flat-dollar minimum (none at the lowest dwelling limits) instead of a percentage |
| Occasional rentals, year-round primary or secondary home | May be rented for up to 12 weeks a year |
| Occasional rentals, seasonal property | May be rented for up to 4 weeks a year |
We walk through how a FAIR Plan policy compares with a regular homeowners policy before you decide, and we can keep checking the regular market at renewal.
How should a Newburyport second home, condo or summer rental be insured?
The policy has to match how the home is really used. Our second and seasonal home insurance guide goes deeper. For Newburyport, we focus on:
- Short-term rentals. The city defines a short-term rental unit as a home, or any bedroom in it, rented for fewer than 30 consecutive days. Its guide says any unit offered for more than 14 days a year must be licensed through the Newburyport Licensing Commission, and the application asks for proof of liability insurance. Plum Island has its own rental category. Tell us before you rent, because many homeowners policies limit coverage for regular rentals.
- Condos. A condo unit-owner (HO-6) policy covers your unit, belongings and liability, and works alongside the association’s master policy. Most of the carriers we work with write HO-6 policies. Read the master policy and bylaws so your walls-in coverage and loss assessment limits fit. The city’s rental guide also asks condo owners for an affidavit of approval from the association before renting.
- Seasonal vacancy. If you close a Plum Island house for the winter, agree with us on whether it stays heated or gets drained, and who checks on it.
- Liability. Guests, renters, docks and pools add exposure. An umbrella policy can sit over your Newburyport home, a home in another state and your cars if the underlying limits line up.
How much dwelling coverage does a Newburyport home need?
Enough to rebuild it. For a historic house, that often means an estimate that counts plaster walls, original trim and millwork, slate or wood roofs and chimneys, not just square footage. We compare extended or guaranteed replacement cost options and set the limit with you before the policy starts.
For higher-value homes in Newburyport, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover, and all six write in Massachusetts. We also look at scheduling jewelry, art and collections at agreed values. For auto, we compare options from our 30+ carriers. Chubb and Cincinnati auto are available only when packaged with a Chubb or Cincinnati home policy. Our coastal Massachusetts high-value home insurance page and our high net worth insurance page cover the top of the market.
- Your current declarations page, including any wind or named storm deductible, as a percentage and in dollars.
- A current rebuild cost estimate, especially for an older or historic home.
- Ordinance or law coverage and how long additional living expense lasts.
- Flood zone, elevation certificate and any current NFIP or private flood policy.
- Roof age and updates to heating, wiring and plumbing.
- Any short-term or seasonal rental use, and your city rental license.
- For condos, the association’s master policy and bylaws.
- Valuables kept at the house, like jewelry, art or a boat.
Frequently asked questions
Can a Portsmouth, NH insurance agency insure my home in Newburyport, Massachusetts?
Yes. Portsmouth Atlantic Insurance is licensed in Massachusetts, among 10 states, and our Portsmouth office is a short drive from Newburyport. We insure year-round homes, historic houses, condos and second homes in Newburyport and nearby towns.
Does homeowners insurance cover flooding in Newburyport or on Plum Island?
No. Flood from storm surge, high tides, the Merrimack River or heavy rain is excluded from homeowners policies. You need a separate NFIP or private flood policy. NFIP coverage generally starts 30 days after purchase, unless an exception applies, such as a policy bought when you close on a mortgage.
What is a wind or named storm deductible in Massachusetts?
It is a separate deductible that applies only when wind or a named storm causes damage. The Massachusetts Division of Insurance says it is usually 1% to 5% of the insured value of the home, though it can be a fixed amount, and it may apply per event, per season or per calendar year.
Does an older home in Newburyport need different coverage?
Often, yes. Insure the cost to rebuild with similar materials, not the market value, and check ordinance or law coverage for code upgrades. Newburyport also reviews demolition of many older buildings, which can add time to a rebuild, so check how long additional living expense coverage lasts.
Do I need different insurance if I rent my Newburyport home short term?
You may. Newburyport requires a license for short-term rental units offered more than 14 days a year, and the application asks for proof of liability insurance. Tell your agent before you start renting, because many homeowners policies limit coverage for regular rentals.
What is the Massachusetts FAIR Plan?
The Massachusetts Property Insurance Underwriting Association, known as the FAIR Plan, is the market of last resort for homeowners who cannot get coverage from a private insurer. It offers basic property coverage and does not cover flood.
Sources
- Massachusetts Division of Insurance, “Division of Insurance Reminds Massachusetts Residents to Prepare Now for a Hurricane” (Aug. 8, 2024)
- Massachusetts Division of Insurance, “Massachusetts Property Insurance Underwriting Association”
- Massachusetts Property Insurance Underwriting Association, “Producer Quick Reference”
- Massachusetts Office of Coastal Zone Management, “CZM North Shore Region”
- National Park Service, NPGallery, “Newburyport Historic District” (NRIS 84002411)
- City of Newburyport, historic inventory form, 63 High Street (Pike-Cushing-Bachman House)
- City of Newburyport, “Demolition Delay Ordinance Process Flowchart”
- City of Newburyport, “A Quick Guide to Demolition Control Overlay District (DCOD) and Demo Delay in the DCOD”
- City of Newburyport Office of Planning and Development, memo on 2025 FEMA flood map and floodplain zoning update (April 14, 2025)
- City of Newburyport, “Harbor Dredging Project”
- The Boston Globe, “Sand dredged off Plum Island to prevent flooding; residents want long-term solution” (Jan. 1, 2023)
- City of Newburyport Licensing Commission, “Short-Term Rental Units”
- City of Newburyport, “Short-Term Rental Unit Guide” (rev. Jan. 22, 2024)
- FEMA, “Flood Map Service Center”
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- Congressional Research Service, “What Happens If the National Flood Insurance Program (NFIP) Lapses?” (updated Sept. 11, 2026)
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 “Year Structure Built”
This page is general information, not a policy. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Your policy documents control.
Historic house, downtown condo or Plum Island second home, we’ll compare carriers from our Portsmouth office.
Talk to our Portsmouth team: (603) 431-4020 · Request a Newburyport home insurance quote
Reviewed by Jon Merwin, licensed insurance agent
Portsmouth Atlantic has been an independent agency since 2005, is licensed in 10 states, works with 30+ carriers and has earned over 2,000 testimonials and 1,000+ Google reviews across our two offices. Meet our team.