
Home · Coastal · Flood · Condo · Massachusetts
By Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance · Reviewed by Jon Merwin, licensed insurance agent
Published October 2026 · Updated October 7, 2026
- Portsmouth Atlantic Insurance is licensed in Massachusetts and insures Marblehead homes, condos, cars and boats from our Portsmouth, NH office, about an hour up I-95.
- About 46 percent of Marblehead’s housing units were built in 1939 or earlier, per Census data, compared with about 31 percent statewide. Rebuild cost and ordinance or law coverage matter on homes that old.
- In the Old Town and Gingerbread Hill historic districts, most exterior work seen from a street, a way or navigable water needs a Certificate of Appropriateness first. That can shape what a rebuild costs and how long it takes.
- FEMA’s flood maps show coastal high-hazard Zone VE and Zone AE along Marblehead’s shoreline. Flood is excluded from homeowners policies, and NFIP coverage usually starts 30 days after purchase.
- Many Marblehead policies carry a separate wind or named storm deductible, which the Division of Insurance says generally runs from 1% to 5% of the home’s insured value.
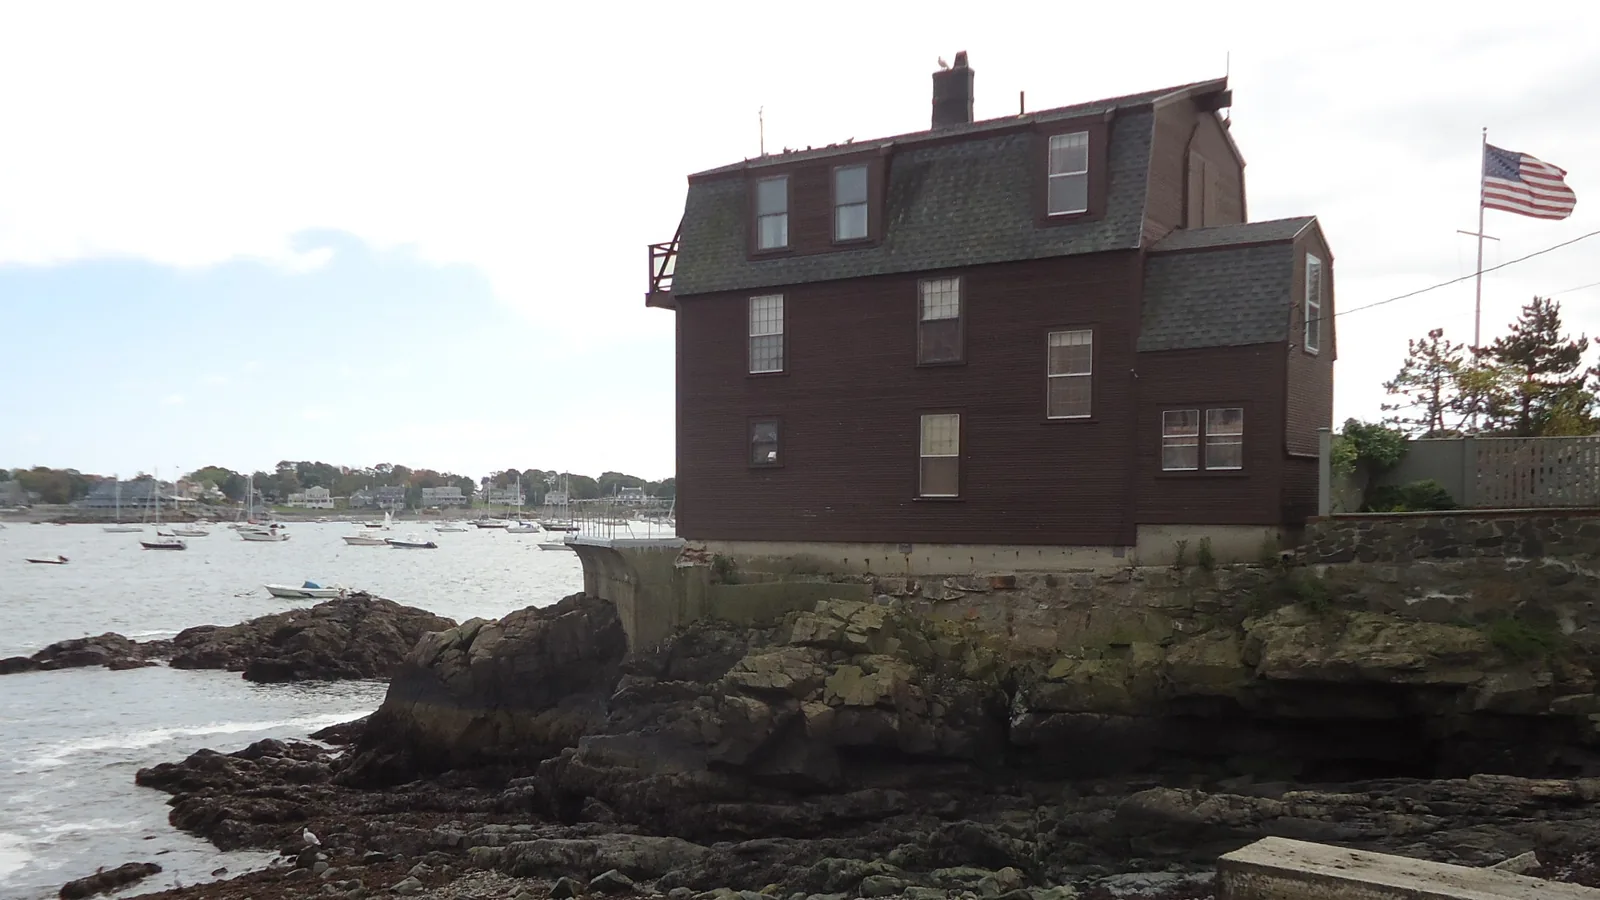
Looking for home insurance in Marblehead, Massachusetts? Portsmouth Atlantic Insurance is licensed in Massachusetts, among 10 states, and we write a lot of Massachusetts business from our office in Portsmouth, NH. In Marblehead we insure antique houses in Old Town, larger homes on Marblehead Neck and along the shore toward Clifton, condos and two-families, and the cars and boats that go with them. As an independent agency, we compare 30+ carriers instead of selling one company’s policy. That matters in Marblehead, where the right carrier often depends on how old the house is, how close it sits to the water and what it would really take to rebuild it.
Can a Portsmouth agency insure a home in Marblehead, Massachusetts?
Yes. We hold a Massachusetts license, and you can work with us by phone, email, video or in person at our Portsmouth office. We also insure homes up the coast in Newburyport, and if you own a place on the Cape, in New Hampshire or in Maine, we can insure it too. For statewide notes, see our Massachusetts homeowners insurance page.
How old are Marblehead homes?
Older than most. In the Census Bureau’s 2019-2023 American Community Survey, about 46.4 percent of Marblehead’s 8,854 housing units were built in 1939 or earlier. Statewide, the figure is about 30.7 percent. All told, about 66.9 percent of Marblehead’s homes were built before 1960. Here’s the breakdown by decade.
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 (year structure built), from the ACS summary file. Our calculation: units in each period divided by total housing units. Estimates carry margins of error; for example, the 1939-or-earlier figure is 4,111 units, plus or minus 463. Very small bars are drawn at a minimum width so the label stays readable.
Many of those older houses sit in Marblehead’s two local historic districts, Old Town and Gingerbread Hill, overseen by the Old and Historic Districts Commission (OHDC), established in 1967 under the Old and Historic Marblehead Districts Act (Chapter 101 of the Acts of 1965). Our guide to historic home insurance covers the basics.
What kind of homes does Marblehead have?
Mostly owner-occupied single-family houses. About 75.4 percent of Marblehead’s housing units are single-family detached homes, compared with about 51.4 percent statewide, and owners occupy about 82.8 percent of occupied homes, compared with about 62.6 percent statewide. About 20.8 percent of units are in buildings with two or more units, mostly two-families and small buildings of three or four units.
| Type of building | Marblehead | Massachusetts |
|---|---|---|
| Single-family, detached | 75.4% | 51.4% |
| Single-family, attached (townhouse) | 3.5% | 5.8% |
| 2 units | 5.6% | 9.4% |
| 3 or 4 units | 8.2% | 10.6% |
| 5 to 19 units | 5.5% | 10.0% |
| 20 or more units | 1.4% | 11.9% |
| Owner-occupied (share of occupied homes) | 82.8% | 62.6% |
That mix shapes the insurance. Most Marblehead owners need a homeowners policy built around rebuild cost, often with a wind deductible and a flood policy alongside it. Condo owners need an HO-6 policy that fits the master policy, and two-family owners need coverage for rental income and landlord liability too.
What do Marblehead’s historic districts change about a rebuild?
Quite a lot, if the house is inside Old Town or Gingerbread Hill. The town tells owners that before starting any repairs, alterations or new construction on structures subject to OHDC review, town bylaws require a Certificate of Appropriateness. The Commission’s purview covers buildings and features visible from a public way, and its guidelines say views from a public street, a private way or navigable water count. For a house that faces the harbor, that can mean the water side too.
- What needs approval. The town lists examples such as additions, window and door replacements, HVAC condensers, fences, roofs (including gutters, soffits and fascia), siding repair or replacement, walls, patios and chimneys. Interior work, paint color, storm doors and storm windows, and plantings generally don’t need a certificate.
- Small repairs in kind. The guidelines exempt general maintenance and repair only when the work is in kind and covers less than 20% of a feature, such as one side of a building or one plane of a roof. A storm that strips a whole roof plane or one side of a house would generally go through review.
- Materials. The most common window in the districts is a wood, double-hung, true-divided-light window. Wood is almost always the appropriate material for doors, wood gutters must be replaced with wood, and composites such as PVC generally aren’t approved, with limited exceptions such as some spots with direct ocean exposure.
- Time. Hearings are held twice a month. If the Commission refers an application to a public hearing, which is common for additions, parking and new fences or walls, the guidelines say it typically happens 3-4 weeks after the first hearing. A certificate is valid for one year.
- Upkeep. Under a 2021 bylaw, the Commission and the Building Commissioner can order repairs to a district building they find is being demolished by neglect, such as by letting water and wind in through the roof or walls.
For insurance, that points to three things: insure the house for what it would cost to rebuild with the materials the Commission is likely to require, ask how much the policy pays under ordinance or law coverage for code upgrades, and check how long additional living expense coverage lasts, because approvals add time.
“Inflation over the past few years has moved the goalposts on what it costs to rebuild, and the old houses in Marblehead’s Old Town feel that as much as anywhere. We’re seeing much higher dwelling coverage than in the past. Insurance companies are adjusting too, and expanding their appetite for higher-value homes, so owners here have more options than they used to.”— Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance
Does homeowners insurance cover flooding in Marblehead?
No. The Massachusetts Division of Insurance (DOI) reminds homeowners that flood damage isn’t included in a standard home insurance policy. You can buy flood coverage from the National Flood Insurance Program (NFIP) or from a private insurer.
Marblehead’s Engineering Department lists seven FEMA flood map panels for the town, from Pinecliff and Crestwood to downtown, Marblehead Neck, the islands and Clifton. FEMA’s revalidation letter to the town shows the current maps took effect July 16, 2014, and FEMA’s National Flood Hazard Layer shows one panel, Clifton to Seaview, was reissued effective July 8, 2025. The maps show Zone AE and coastal high-hazard Zone VE, where FEMA expects wave action on top of the flood, along the shoreline. Look up your address on FEMA’s Flood Map Service Center or ask the town engineer.
- Lender requirements. FloodSmart says you’re required to have flood insurance if you own a home in a Special Flood Hazard Area and have a government-backed mortgage, and some banks require it even outside high-risk areas.
- Waiting period. FloodSmart says NFIP coverage goes into effect 30 days after purchase, with exceptions, including a policy bought while making, increasing, extending or renewing a mortgage. Don’t wait for a storm forecast.
- Program status. As of early October 2026, the Congressional Research Service reports that the NFIP is authorized through December 11, 2026.
- Larger homes. NFIP building coverage has a federal cap, and FloodSmart says NFIP policies don’t cover temporary housing during repairs. For higher-value homes, we look at private or excess flood coverage.
- Private options. Private flood carriers we work with include Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Which ones can write a particular Marblehead home depends on the property.
Our flood insurance page explains the options in more detail. Water that backs up through a sewer or drain is a separate issue, and a standard homeowners policy needs a water backup endorsement to cover it.
| Risk in Marblehead | Usually covered by homeowners | Usually not covered | What to ask |
|---|---|---|---|
| Wind damage to a roof, chimney or shutters in a nor’easter | Yes | The part under your wind or named storm deductible | Is the wind deductible a percentage, and per event or per season? |
| Storm surge or wave wash into the first floor | No | Yes | Flood zone (AE or VE) and an NFIP or private flood policy |
| Water backing up through a basement drain | No | Yes, unless added | Water backup endorsement |
| Rebuilding an Old Town house with approved materials | Yes, up to your limits | Code upgrades beyond ordinance or law limits | Rebuild estimate, ordinance or law limit, additional living expense |
| A unit-owner’s share of a large condo claim | Only with loss assessment coverage | Assessments above your limit | Loss assessment limit vs. the master deductible |
| Your car flooded in a coastal storm | No (homeowners or flood) | Yes, without comprehensive | Comprehensive coverage on the auto policy |
We’ll compare carriers for coastal, historic and high-value homes and line up flood, auto, boat and umbrella coverage.
Talk to our Portsmouth team: (603) 431-4020 · Start a Marblehead home insurance quote
How do wind and named storm deductibles work in Marblehead?
The DOI says some Massachusetts policies have a special deductible that applies only when a named storm or wind causes damage. It is separate from the regular deductible, is usually a percentage of the home’s insured value, and generally ranges from 1% to 5%. It can also be a fixed amount, and it may apply per event, per season or per calendar year.
The FAIR Plan’s published rules show how distance from the water matters. Outside Barnstable, Dukes and Nantucket counties, its minimum named storm deductible within half a mile of the coast, as much of Marblehead is, is 1% or 2% of the dwelling limit, with 2% at higher limits; farther inland it is a flat-dollar minimum. Private carriers file their own rules, so ask us to translate any percentage into a dollar figure for your home before you choose.
What if no insurer will write a Marblehead home?
Because we work with 30+ carriers, one decline doesn’t end the search. If no company in the regular market will write the home, the DOI says the market of last resort is the Massachusetts Property Insurance Underwriting Association (MPIUA), known as the FAIR Plan, which offers basic property coverage and doesn’t cover flood. The DOI also says that as of 2025, a new FAIR Plan policy for a property in a Special Flood Hazard Area in a community overseen by the Office of Coastal Zone Management requires a separate flood policy, and CZM lists Marblehead among the communities its North Shore office serves. We compare a FAIR Plan policy with regular options before you decide and keep checking the regular market at renewal.
How should a Marblehead condo be insured?
A condo unit-owner (HO-6) policy covers your unit, your belongings and your personal liability. It works alongside the association’s master policy, which covers the building and common areas. Every carrier we write with insures condos except Progressive and Openly. Before we quote, we read three things:
- The master policy. Whether it covers bare walls only or fixtures and finishes too tells us how much walls-in coverage your HO-6 needs.
- The master deductible. If the association passes its deductible, including a wind deductible, on to unit owners, your HO-6 should be set up to respond.
- Loss assessment. If a large loss exceeds the master policy, the association can assess every owner; loss assessment coverage helps pay your share.
In the historic districts, the OHDC also asks that applications for work on condominiums include written approval from the association or its trustees, so exterior repairs after a loss run through the association too. Our guides to condo insurance vs. homeowners insurance and HOA master policies go deeper.
Can you rent a Marblehead home short term?
Check before you list it. We didn’t find a town-wide short-term rental bylaw in Marblehead as of October 2026; the Marblehead Current reported that the town began charging a 6% local room occupancy tax on short-term rentals in May 2024 while officials studied possible rules. The accessory dwelling unit (ADU) bylaw is stricter: under amendments Town Meeting passed on May 4, 2026, rentals of fewer than 31 days are prohibited in both the ADU and the main home on a property with an ADU. Ask the town’s planning office about your property first.
State law applies everywhere. Under Massachusetts General Laws Chapter 175, Section 4F, a short-term rental operator must carry at least $1 million in liability coverage for each short-term rental, unless the rental is offered through a hosting platform that maintains equal or greater coverage. The operator must also notify the homeowners or renters insurer, and insurers may exclude short-term rental claims from a regular homeowners policy. Tell us before you rent so the coverage fits. If the home is on the FAIR Plan, its rules allow occasional rental of up to 12 weeks a year for a year-round home and up to 4 weeks for a seasonal property.
Do you insure boats on Marblehead moorings?
Yes. The town calls Marblehead waters one of the busiest harbor complexes in New England, and a Harbormaster permit is required before installing mooring equipment or anchoring a boat. Homeowners policies offer limited protection for watercraft, so most boats need their own policy, set up for how and where the boat is used and stored. Our boat and watercraft insurance page explains the coverage.
What about auto and umbrella coverage?
For auto, we compare options from our 30+ carriers. Our high-value auto carriers are Cincinnati, Hagerty, Hanover and Progressive, and Chubb and Cincinnati auto are available only when packaged with a Chubb or Cincinnati home policy. The DOI notes that homeowners and flood insurance don’t cover cars, but an auto policy with comprehensive coverage will likely cover flood damage.
An umbrella policy adds liability limits over your home, cars and other properties, which is worth a look if you host guests on a boat, rent a unit or own more than one home.
How much dwelling coverage does a Marblehead home need?
Enough to rebuild it. The DOI notes that labor and construction costs have risen, so you may need to raise your dwelling coverage (Coverage A) to rebuild at today’s prices. For an older Marblehead house, the estimate should count wood windows and doors, plaster, original trim, chimneys and masonry, not just square footage. We compare extended or guaranteed replacement cost options and set the limit with you.
For higher-value homes on the Neck, along the harbor or in Old Town, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover, and all six write in Massachusetts. For the very largest homes, Chubb and Cincinnati are the carriers we use. We also look at scheduling jewelry, art and collections at agreed values. Our coastal Massachusetts high-value home insurance page, our article on insuring coastal luxury homes in Marblehead, Cohasset and Manchester-by-the-Sea and our high net worth insurance page go deeper.
- Year built, square footage and updates to the roof, heating, wiring and plumbing
- Whether the home is in the Old Town or Gingerbread Hill historic district, and any Certificates of Appropriateness for past work
- Your flood zone from FEMA’s map (AE, VE or other), any elevation certificate and whether you have a finished basement
- Your current declarations page, including any wind or named storm deductible, as a percentage and in dollars
- For condos: the master policy, the master deductible and the bylaws
- Any rental plans, an ADU on the property, and your boat and mooring details
- Jewelry, art or collections worth scheduling, your cars and your current liability and umbrella limits
Marblehead home insurance FAQs
Can an insurance agency in New Hampshire insure my home in Marblehead, MA?
Yes, if the agency is licensed in Massachusetts. Portsmouth Atlantic Insurance is licensed in Massachusetts and insures Marblehead homes, condos, cars and boats from our Portsmouth, NH office, by phone, email or video.
Does being in the Old Town historic district affect insurance on a Marblehead home?
It can affect the rebuild. Most exterior work visible from a street, way or navigable water in the Old Town and Gingerbread Hill districts needs a Certificate of Appropriateness first, and the Commission looks closely at materials such as wood windows, doors and gutters. Ask about rebuild cost, ordinance or law coverage and how long additional living expense coverage lasts.
Do I need flood insurance in Marblehead?
If the home is in a Special Flood Hazard Area, such as Zone AE or VE, and has a government-backed mortgage, flood insurance is required. Outside those zones it’s optional, but standard homeowners policies don’t cover flood, and NFIP coverage usually starts 30 days after purchase.
What is a named storm deductible on a Marblehead home?
It is a separate deductible that applies when a named storm or wind causes damage. The Massachusetts Division of Insurance says these generally run from 1% to 5% of the home’s insured value, and they can apply per event, per season or per calendar year.
What does a Marblehead condo owner need besides the master policy?
Usually a unit-owner (HO-6) policy for the inside of the unit, your belongings and your liability, plus loss assessment coverage for your share of a large association claim. How much walls-in coverage you need depends on what the master policy covers.
Can I rent my Marblehead home on a short-term rental site?
Check with the town first. Marblehead’s ADU bylaw prohibits rentals of fewer than 31 days in both units on a property with an ADU. State law also requires short-term rental operators to notify their insurer and carry at least $1 million in liability coverage for each rental.
Sources
- Massachusetts Division of Insurance, “Division of Insurance Reminds Massachusetts Residents to Prepare Now for a Hurricane” (Aug. 8, 2024)
- Massachusetts Division of Insurance, “Massachusetts Property Insurance Underwriting Association”
- Massachusetts Property Insurance Underwriting Association, “Producer Quick Reference”
- Massachusetts Office of Coastal Zone Management, “CZM North Shore Region”
- Marblehead Old and Historic Districts Commission, letter of general guidance to property owners in the historic districts (2025)
- Old and Historic Marblehead Districts Commission, OHDC process guidelines
- Old and Historic Marblehead Districts Commission, Application for Certificate of Appropriateness
- Town of Marblehead General Bylaws, Chapter 111, Demolition by Neglect (2021)
- Town of Marblehead, “Town Engineer” (flood insurance rate map panels)
- FEMA, revalidation letter to the Town of Marblehead (July 16, 2014)
- FEMA, National Flood Hazard Layer (panel effective dates and flood zones, checked October 2026)
- FEMA, “Flood Map Service Center”
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- FEMA FloodSmart, “Eligibility”
- Congressional Research Service, “What Happens If the National Flood Insurance Program (NFIP) Lapses?” (updated Sept. 11, 2026)
- Massachusetts General Laws, Chapter 175, Section 4F
- Marblehead Current, “Short-term rentals surge 131% in Marblehead” (Oct. 16, 2024)
- Marblehead Current, “Town still working out how new ADU rules work” (Sept. 1, 2026)
- The Marblehead Independent, 2026 Town Meeting article tracker (May 4, 2026)
- Town of Marblehead, “Harbormaster”
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, tables B25034 “Year Structure Built”, B25024 “Units in Structure” and B25003 “Tenure”
This page is general information, not a policy or legal advice. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Local rules change, so check current town rules before you build or rent. Your policy documents control.
Antique house in Old Town, waterfront home on the Neck or a condo near the harbor, we’ll compare carriers from our Portsmouth office.
Talk to our Portsmouth team: (603) 431-4020 · Request a Marblehead home insurance quote
Reviewed by Jon Merwin, licensed insurance agent
Portsmouth Atlantic has been an independent agency since 2005, is licensed in 10 states, works with 30+ carriers and has earned over 2,000 testimonials and 1,000+ Google reviews across our two offices. We don’t charge agency or broker fees on personal lines. Meet our team.