High-valueNH
Reviewed by Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance · Published October 4, 2026
Key takeaways
- At $4 million, what is inside the home, and the household’s liability, often need as much attention as the house itself.
- Standard homeowners policies carry limited coverage for jewelry, art, antiques and other valuables. Scheduling them on a floater at an appraised value closes that gap.
- Wine cellars, watch collections and art need their own questions: appraisals, storage, transit and how a partial loss is paid.
- Most insurers want about $250,000 of auto liability and $300,000 of home liability before selling an umbrella. Your umbrella limit should reflect your assets and risks.
- In New Hampshire, an umbrella over your auto policy includes uninsured motorist coverage equal to its limits unless you reject it in writing.
How much is insurance on a $4 million home in New Hampshire? The house is only part of the answer. The premium depends on rebuild cost, location, construction, protective devices, claims history and coverage choices. In a $4 million household, though, the contents and the liability exposure can be as valuable as the structure. We don’t publish an average premium, because a single number would mislead more people than it helps. What we can do is explain what drives the cost and what to check before you buy.
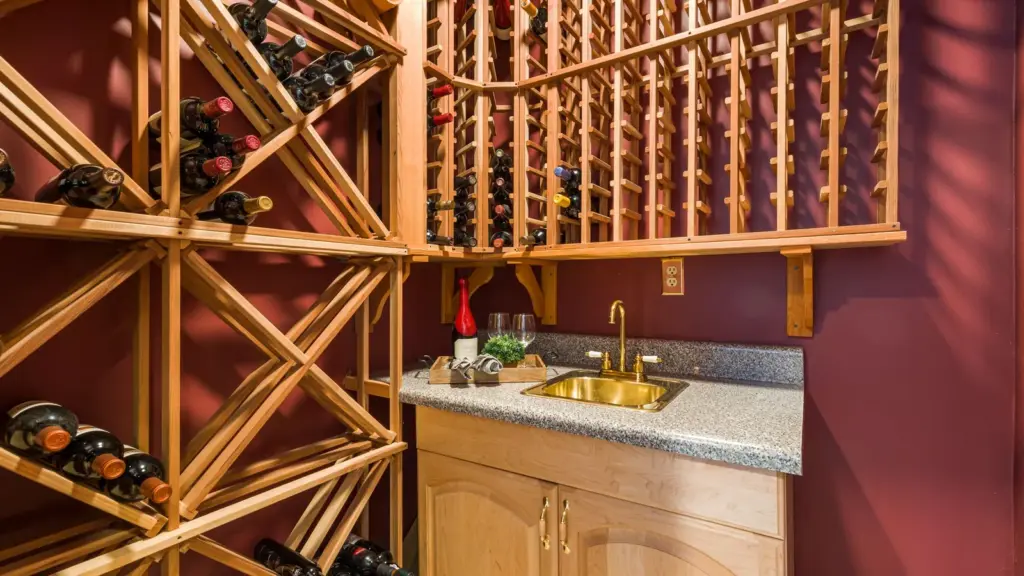
This guide covers two questions that matter most at this level: how to insure art, jewelry, wine and collections, and how much umbrella liability to carry. For rebuild cost, see our $3 million home guide.
What drives the cost to insure a $4 million home and its contents?
- Rebuild cost of the home and its outbuildings.
- The value and type of what’s inside: jewelry and watches, fine art, wine, collections and furnishings.
- How valuables are stored and protected: safes, vaults, monitored alarms, fire suppression and climate control.
- Liability exposure: drivers, pools, docks, household staff, rental properties and how often you entertain.
- Coverage choices: scheduled limits, deductibles, liability limits and the umbrella.
Why do standard homeowners policies fall short on valuables?
The NAIC notes that a typical homeowners policy includes limited coverage for valuables, and those limits may not fully cover an expensive piece of jewelry, antiques or artwork. Triple-I’s guide to special coverage for jewelry and other valuables explains that standard policies set a relatively low limit for theft of jewelry, and that there are two ways to increase coverage: raise the limit, or buy a floater and schedule individual items. Triple-I describes the floater as the broadest protection, covering accidental losses such as a ring lost down a drain, and notes that items must be professionally appraised first.
Scheduling an item means listing it with its own appraised value, so the category limits no longer cap it. Policies differ, so ask how each one handles breakage, partial losses and items you take with you when you travel.
How do you insure art, jewelry, wine and collections?
| Asset | Common gap on a standard policy | What to ask |
|---|---|---|
| Jewelry and watches | Low limits for theft | Scheduling at appraised value; coverage for loss or damage while traveling |
| Fine art | General contents limits may not fit | Agreed value, restoration costs, coverage in transit or on loan |
| Wine | Contents limits and storage risks | Cellar inventory, coverage for spoilage from a cooling failure, bottles in transit |
| Silver, antiques and rugs | Category limits and depreciation | Agreed value and whether pairs and sets are covered |
| Collections (coins, memorabilia, firearms) | Category limits and theft caps | Scheduling, newly acquired items and storage requirements |
- Keep appraisals current. Values change, especially for art, watches and wine. Schedule a review every few years, or sooner for active markets.
- Keep an inventory. Photos, receipts, appraisals and a cellar list make a claim far easier.
- Tell us about new purchases. Ask how long the policy covers newly acquired items before they must be scheduled.
- Protect the room. Safes, monitored alarms, water and temperature sensors and backup power for a cellar can affect eligibility with some carriers.
What do high-value policies already include for contents?
Before you schedule anything, it helps to know what a private-client contents policy may already include. Features differ by carrier. Availability varies by state and policy.
- Replacement cost on contents. Belongings are paid at what it costs to replace them, not at a depreciated value.
- Higher built-in limits for valuables. Chubb’s Masterpiece and Cincinnati’s Capstone forms carry higher category limits than standard policies for items such as jewelry, silver and firearms, and can cover them when lost or misplaced, not only stolen. Scheduling is still how you cover major pieces at full value.
- Spoilage. Some policies pay for food and wine spoiled when power or a cooling system fails. Ask how your cellar is treated.
- Identity fraud help. Some forms include or offer coverage for the cost of recovering from identity theft.
- Equipment breakdown. An optional add-on that can cover the sudden breakdown of a cellar cooling unit and other home systems.
Have art, jewelry or a wine cellar to insure?
Get a valuables and liability review from our Portsmouth team: (603) 431-4020.
How much umbrella coverage does a $4 million household need?
Triple-I explains that an umbrella policy kicks in when you reach the limit on the underlying liability coverage in your auto or homeowners policy, and can cover some claims those policies don’t, such as libel and slander. Because it pays after the underlying coverage is used up, most insurers want you to carry about $250,000 of liability on your auto policy and $300,000 on your homeowners policy before they will sell you an umbrella. High-value programs may set their own requirements.
There is no formula for the right umbrella limit. We look at:
- What you have to protect: home equity, investments, savings and future income.
- Who drives: teen and college-age drivers, household staff and the number of vehicles.
- Your property: pools, docks, boats, trampolines, dogs and rental homes.
- Your activities: frequent entertaining, nonprofit board service and a public profile. Ask whether the umbrella covers personal claims tied to unpaid board roles.
One New Hampshire rule to know: under RSA 264:15, an umbrella or excess policy over your auto policy must provide uninsured motorist coverage equal to the limits you buy, unless the named insured rejects it in writing. See our umbrella insurance page for how it works.
Which carriers insure $4 million homes and collections in New Hampshire?
As an independent agency comparing 30+ carriers, the carriers we work with that write homes up to $5 million are Cincinnati, Chubb, Openly and National General. Appetite for very high values, collections and umbrella limits differs by carrier, so we compare the home, valuables and liability together rather than one at a time.
Checklist: valuables and liability review
- List every item worth scheduling, with appraisals or receipts.
- Update appraisals that are more than a few years old.
- Keep a current wine cellar inventory.
- Ask how travel, transit, loans and newly acquired items are covered.
- Confirm home and auto liability limits meet the umbrella’s requirements.
- Choose an umbrella limit based on assets, drivers and property risks.
- Decide on uninsured motorist coverage in the umbrella in writing.
 Expert tip from Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance
“Even with art and collections in the picture, start with the house. Inflation over the past few years has driven dwelling replacement costs up, the goal posts have moved, and we’re seeing much higher dwelling coverage than we used to. Insurers are adjusting as well, expanding their appetite to handle higher-value homes.”
— Jon Merwin, Founder & CEO, Portsmouth Atlantic Insurance
Frequently asked questions
How much is homeowners insurance on a $4 million home?
There is no reliable single figure. The premium depends on the cost to rebuild the home, its location and construction, the valuables you schedule, your liability limits and the deductibles you choose. Comparing carriers for your household is the way to get a real number.
Does homeowners insurance cover jewelry and art?
A standard homeowners policy includes only limited coverage for valuables such as jewelry, antiques and artwork, and those limits may not cover expensive pieces. Scheduling items on a floater or valuables policy, after a professional appraisal, closes the gap.
How do I insure a wine collection?
Keep a current inventory and appraisal, then schedule the collection or insure it under a valuables policy. Ask how the policy treats breakage, bottles in transit and spoilage if the cellar’s cooling fails.
How much umbrella insurance should I carry with a $4 million home?
There is no fixed rule. The limit should reflect your assets, future income, drivers, property risks and activities. Insurers usually require minimum home and auto liability limits underneath the umbrella.
Does an umbrella policy include uninsured motorist coverage in New Hampshire?
Under RSA 264:15, an umbrella or excess policy over your auto policy must provide uninsured motorist coverage equal to the limits purchased, unless the named insured rejects it in writing.
Sources
- NAIC, "Homeowners Insurance" consumer guide
- Insurance Information Institute, "Special coverage for jewelry and other valuables"
- Insurance Information Institute, "What is an umbrella liability policy?"
- New Hampshire RSA 264:15, Uninsured or Hit-and-Run Motor Vehicle Coverage
Insuring a $4 million home in New Hampshire?
Talk to our Portsmouth team: (603) 431-4020. We have been independent since 2005 and compare 30+ carriers.
Jon Merwin, Founder & CEO · Portsmouth, NH
Reviewed by Jon Merwin, Founder & CEO. Meet our team.
Portsmouth Atlantic Insurance is the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews across our two offices.
Our New Hampshire high-value home guides by home value
- How Much Is Insurance on a $2 Million Home? (overview: carriers, coverage, flood)
- How Much Is Insurance on a $3 Million Home? (rebuild cost and guaranteed replacement)
- How Much Is Insurance on a $4 Million Home? (art, jewelry, wine and umbrella limits) (this guide)
- How Much Is Insurance on a $5 Million Home? (waterfront estates, staff and multiple homes)
- How Much Is Insurance on a $10 Million Home? (private-client coverage for very high-value households)
Each guide covers a different question, so read the one that matches what you are working through. For an overview of coverage built for these households, see our high net worth insurance page. For local help, see our New Hampshire insurance agency page.
Related guides
Next step: see our high-value home insurance in Portsmouth, NH page.