
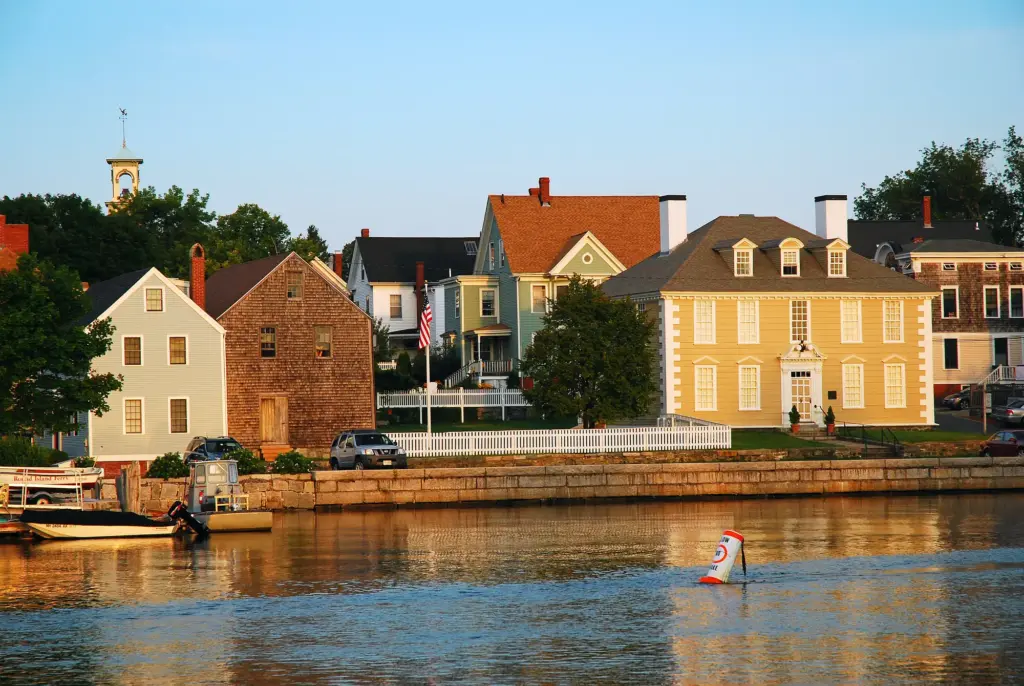
Portsmouth is not a typical high-value market. Many of the most valuable homes in the city are not new estates on big lots. They are 18th- and 19th-century houses in the South End and around Strawbery Banke, brick Federal homes a few blocks from Market Square, waterfront houses along Little Harbor and Sagamore Creek, and top-floor condos in converted downtown buildings. Each of those raises a different insurance question, and a standard homeowners policy is often not built to answer them.
This page is about insuring a high-value home in the city of Portsmouth itself. If your home is on the open coast, see our guides to Rye high-value home insurance and New Castle high-value home insurance, which cover oceanfront wind and island access in more depth. For carrier tiers and other towns across the state, start with our New Hampshire high-value home insurance hub. For a more typical house in town, see Portsmouth, NH homeowners insurance.
Portsmouth Atlantic Insurance is a family-owned independent agency founded in 2005, with our office at 601 Islington St, Unit 206. We’re licensed in 10 states, we work with 40+ carriers, and we’re New Hampshire’s highest-rated agency on Google, with 1,000+ Google reviews and over 2,000 testimonials. We don’t charge additional fees.
Key facts for Portsmouth high-value homes
- Historic South End and Strawbery Banke-area homes need a dwelling limit based on rebuilding with like kind and quality materials, not on market value or assessed value.
- Waterfront homes on Little Harbor, Sagamore Creek and the Piscataqua can sit in mapped flood zones. Homeowners insurance doesn’t cover flood.
- Downtown condo owners need an HO-6 policy that fits the association’s master policy, including improvements and loss assessment.
- Cincinnati and Chubb both write homes at any dwelling limit. Openly and National General fit homes up to about $5 million, and Andover can fit New Hampshire homes up to about $1.5 million. Liberty Mutual may also be an option for New Hampshire homes up to $4 million in dwelling coverage, with higher amounts subject to underwriting approval.
- We compare 40+ carriers and we don’t charge additional fees.
Why Portsmouth homes are different from the rest of the Seacoast
In Rye and New Castle, the biggest underwriting questions are usually wind off the open Atlantic, surge and distance to the water. In Portsmouth, the first question is often the house itself. Carriers want to know when it was built, how it was framed, what is behind the walls, and what it would really take to rebuild it on a tight city lot. Three kinds of homes come up most:
- Historic homes. The South End, the streets around Strawbery Banke and Prescott Park, and the older blocks off Pleasant, Court and State Streets hold some of the oldest housing in New England. Plaster walls, hand-planed trim, wide-pine floors, slate roofs and original windows are common.
- Waterfront homes. Houses on Little Harbor, Sagamore Creek, Pickering Avenue and along the Piscataqua face tidal water, salt air and winter storms, even though they are not on the open ocean.
- High-end condos and townhouses. Converted buildings downtown, newer luxury buildings near the waterfront and North End townhouses often have high-end finishes owned by the unit owner, not the association.
- Second homes. Many Portsmouth owners spend part of the year elsewhere, or keep a pied-à-terre downtown and a main home in another state.
Insuring historic homes in the South End and around Strawbery Banke
A historic house can be worth far more to rebuild than its sale price suggests. After a fire, recreating plaster, period millwork, custom windows and slate takes specialized trades, and the work may need to meet both today’s building code and the city’s historic district review. A quick online estimate built on average construction costs tends to miss that.
Here is what we look at with you:
- A real rebuild figure. Many high-value carriers send an appraiser to inspect the home and set the dwelling limit. Our home replacement cost estimator gives you a rough starting point before that visit.
- Like kind and quality. Some policies pay to rebuild with materials of like kind and quality. Others settle on functional replacement. That difference matters a great deal on a Federal or Georgian house.
- Building code upgrades. Older homes may need new wiring, plumbing, egress or structural work when they are rebuilt. Ordinance or law coverage helps with that cost.
- Wiring, heat and plumbing. Carriers will ask about knob-and-tube wiring, old boilers and galvanized pipes. Updated systems open up more carrier options.
- Close neighbors. Many South End homes sit a few feet from the next house. Fire spread and access come up in underwriting.
Our guide to older and historic home insurance in New Hampshire goes deeper on wiring, roofs and inspections.
Replacement Cost, Extended and Guaranteed Replacement
The New Hampshire Insurance Department defines replacement cost as the amount needed to rebuild or repair your home with materials of similar kind and quality without deducting for depreciation. Getting the dwelling limit right is the most important part of a high-value policy.
- Extended replacement cost adds a cushion above your dwelling limit if rebuilding costs more than expected.
- Guaranteed replacement cost, offered by some carriers on qualifying homes, pays to rebuild even above the dwelling limit, subject to the policy terms.
- Building code upgrades help with the cost of bringing an older home up to current code during a rebuild.
- Cash settlement options on some high-value policies let you take a settlement instead of rebuilding, which matters if you’d rather buy elsewhere after a total loss.
Which of these you can get depends on the carrier and the home, so we compare the carriers that fit your home side by side.
Waterfront homes on Little Harbor, Sagamore Creek and the Piscataqua
Portsmouth’s waterfront is tidal river and harbor, not open beach. That changes the risk but doesn’t remove it. Winter nor’easters and high tides can push water into low-lying streets near the harbor and the creeks, and salt air is hard on roofs, siding and mechanicals.
- Flood is a separate policy. The Insurance Department is clear that homeowners insurance doesn’t cover flood damage. FEMA’s National Flood Insurance Program generally caps building coverage at $250,000 and contents at $100,000, and a new NFIP policy usually takes effect 30 days after purchase, according to FloodSmart.
- Private flood for larger homes. We place new NFIP policies through Selective, and we compare private flood options such as Flow Flood, Neptune Flood and Beyond Floods when a home needs higher limits.
- Wind deductibles. Some coastal policies carry a separate wind or hurricane deductible figured as a percentage of the dwelling limit. We always show you the dollar figure.
- Docks, seawalls and boathouses. These are often limited or excluded on a homeowners form. Ask how each policy treats them, and see our Portsmouth boat insurance page if you keep a boat at the dock.
See our Portsmouth, NH flood insurance page and check an address with our flood zone check.
High-end condos and townhouses downtown
Downtown Portsmouth has many condos worth more than most single-family homes in the state. A condo policy (HO-6) works alongside the association’s master policy, so the first step is reading the master policy and the bylaws.
- Walls-in coverage. If the master policy covers only the original “bare walls,” your kitchen, baths, built-ins and flooring are on you. Owners who renovated need limits that match.
- Loss assessment. After a large claim at the building, the association can assess each owner. A higher loss assessment limit helps.
- Water from above. In a stacked building, a leak from the unit upstairs is a common claim. Water backup and leak detection devices help.
- Contents and collections. Art, furniture and jewelry in a high-end unit often need more than standard limits.
Our Portsmouth condo insurance page covers master policies in more detail.
Second homes and part-time owners
Plenty of Portsmouth owners split their year. Some keep a downtown condo for summers and live elsewhere in winter. Others have a primary house in the South End and a lake house up north or a home in another state. We’re licensed in 10 states, so we can often coordinate both homes and keep the liability on a single umbrella.
A home that sits empty for part of the winter raises questions about freeze, heat monitoring and how often someone checks the house. Water shutoff devices and monitored alarms help, and some carriers ask for them. See secondary and seasonal home insurance for more.
Which carriers fit a Portsmouth high-value home
For homes under about $2 million, we shop most of our 40+ carriers. Above that, the list narrows to carriers built for high-value homes:
- Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. We can place Chubb in every state where we’re licensed, which helps when you also own a home outside New Hampshire.
- Openly and National General fit homes up to about $5 million.
- Andover can fit New Hampshire homes up to about $1.5 million, and Hanover also writes high-value homes up to its limits.
The right fit depends on the age of the home, its distance to the water, its wiring and heat, and what else you own. We look at all of it before we recommend a carrier.
Jewelry, art, wine and collections
Standard homeowners policies put low limits on items like jewelry, watches, furs and silver, especially for theft. Scheduling those items on their own, usually backed by an appraisal, gives each piece dedicated coverage. We help clients schedule engagement rings, art, antiques, wine and other collections at the right value. Our guide to jewelry, watch and valuables insurance in New Hampshire walks through the special limits and appraisals.
Umbrella liability and the whole household
A home with a pool, a dock, regular guests or household staff carries more liability than most. A personal umbrella adds protection above your home and auto policies. Our umbrella insurance page and umbrella insurance calculator can help you think it through. Our high net worth insurance page covers the full picture, and our high-value auto insurance page explains how we cover luxury and collector cars alongside the home.
Buying a home in Portsmouth
Lenders want to see the dwelling limit, replacement cost terms and any wind deductible before closing. We work directly with your lender and title company, settle the coverage details early and send the binder and evidence of insurance to them. Start the conversation when you go under contract, especially for an older home or a waterfront address, because inspections and flood questions take time.
For more detail by home value, see our guides to insuring a $2 million, $3 million, $4 million, $5 million and $10 million home in New Hampshire.
Why work with an independent agency
An independent agency works for you, not for one insurance company. That matters most on a home that only a few carriers are built for.
- 40+ carriers. We compare the carriers that fit your home, including Chubb and Cincinnati.
- No fees. We don’t charge additional fees.
- Family-owned since 2005. A Portsmouth agency, licensed in 10 states.
- Highly rated. 1,000+ Google reviews and over 2,000 testimonials.
Talk to us about your Portsmouth home
Every household is different, so the best next step is a conversation. Call us at (603) 431-4020, email insure@portsmouthatlanticins.com, or start your high-value home insurance quote online.
We also insure high-value homes in nearby Newington and Stratham. Clients nearby can also sit down with us at our Portsmouth office.
High-value home insurance FAQs for Portsmouth, NH
What counts as a high-value home in Portsmouth?
There isn’t one cutoff. It usually means a home whose rebuilding cost, construction or contents go beyond what a standard homeowners policy is designed for. In Portsmouth that often means historic South End homes, waterfront houses and high-end downtown condos.
How do you insure a historic home in the South End?
We start with a rebuild figure based on like kind and quality materials, often set by the carrier’s appraiser. Then we look at building code upgrade coverage, the home’s wiring and heat, and whether the policy settles on like kind and quality or functional replacement.
Is my dwelling limit the same as my home’s market value?
No. The dwelling limit should reflect what it costs to rebuild the house. For historic homes that can be well above market value, and for some downtown properties much of the market value is the land.
What is the difference between extended and guaranteed replacement cost?
Extended replacement cost adds a set cushion above your dwelling limit. Guaranteed replacement cost, offered by some carriers on qualifying homes, pays to rebuild even above the dwelling limit, subject to the policy terms.
Do I need flood insurance on Little Harbor or Sagamore Creek?
Homeowners policies exclude flood, so a waterfront home needs a separate NFIP or private flood policy. If your lender requires it, you’ll need it before closing. A new NFIP policy usually takes effect 30 days after purchase.
How much flood coverage can I get?
The NFIP generally caps building coverage at $250,000 and contents at $100,000. Private flood insurance can offer higher limits, which often matters for larger homes.
What does a downtown condo owner need?
An HO-6 policy that fits the association’s master policy. Check whether the master policy covers improvements, and carry enough loss assessment coverage and contents coverage for what’s in the unit.
Can you insure my Portsmouth home and a second home in another state?
Often, yes. We’re licensed in 10 states, and we can place Chubb in every one of them, so we can often coordinate both homes and a single umbrella.
Do I need to schedule my jewelry and art?
Usually, yes. Standard policies have low limits for items like jewelry and watches, especially for theft. Scheduling them, usually with an appraisal, gives each item its own coverage.
Which high-value home carriers do you work with in New Hampshire?
For homes under about $2 million, we shop most of our 40+ carriers. Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. Openly and National General fit homes up to about $5 million, and Andover can fit New Hampshire homes up to about $1.5 million. Hanover can write primary homes in New Hampshire up to $2 million in dwelling coverage through its Prestige and Platinum programs, subject to underwriting review. We also work with Hanover.
By Jon Merwin, Founder and CEO, Licensed Insurance Advisor. Last reviewed October 2026.