
Home · Coastal · Second homes · Maine
By Jon Merwin, Founder and CEO
Published October 2026 · Updated October 11, 2026
- Portsmouth Atlantic Insurance is licensed in Maine and insures homes in Kittery, Kittery Point, Kittery Foreside and Gerrish Island from our Portsmouth, NH office across the river.
- Kittery is a year-round town shaped by Portsmouth Naval Shipyard. Only about 5.5 percent of its housing units are seasonal, per Census data.
- About 46 percent of Kittery homes were built before 1960, so carriers ask about roof, wiring and heating updates.
- Waterfront homes on Kittery Point and Gerrish Island face more wind exposure and may carry a higher windstorm deductible.
- Shipyard families who may transfer should plan ahead for renting the house out.
Looking for home insurance in Kittery, Maine? Our Portsmouth office sits just across the Piscataqua River, close enough that many of our Kittery clients drive past the shipyard on the way in. Portsmouth Atlantic Insurance is licensed in Maine, among 10 states, and has been an independent agency since 2005. We compare 40+ carriers for Kittery’s mix of older Foreside houses, Navy families, and waterfront homes out on Kittery Point and Gerrish Island.
Can a Portsmouth agency insure a home in Kittery, Maine?
Yes. We hold a Maine license, and Kittery is the closest Maine town to our Islington Street office. Kittery faces Portsmouth across the Piscataqua, with Portsmouth Naval Shipyard on Seavey Island in between. If you also own a home in New Hampshire or Massachusetts, we can insure it too. The Maine Bureau of Insurance runs a public licensee search if you’d like to confirm any agent’s license. If you also own in the next town up the coast, see our York, Maine home insurance page.
How old are Kittery homes?
Older than most. In the Census Bureau’s 2019-2023 American Community Survey, about 24.5 percent of Kittery’s 5,464 housing units were built in 1939 or earlier, and another 14.6 percent in the 1940s. All told, about 46 percent were built before 1960. Here’s the breakdown by decade.
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 (year structure built), from the ACS summary file. Our calculation: units in each period divided by total housing units. Small-town estimates carry margins of error; for example, the 1939-or-earlier figure is 1,337 units, plus or minus 289.
That matters for insurance. The Maine Bureau of Insurance says premiums are often higher for older homes, although many insurers offer discounts if the major systems (roof, heating, plumbing and electrical) have been updated within the past 10 to 20 years. When we quote a Kittery home, we ask about those updates first.
Are many Kittery homes second homes?
Fewer than you might expect on the Maine coast. The same Census survey puts about 5.5 percent of Kittery’s housing units (300 units, plus or minus 162) in seasonal, recreational or occasional use. Next door in York, it’s about 32 percent. Kittery is mostly year-round homes, but the seasonal cottages and second homes it does have, many of them near the water, still need the right occupancy rating and a winter plan. Our second and seasonal home insurance guide explains what carriers ask.
Some older Kittery houses have been split into two condo units, with owners sharing the roof, foundation and yard. If you own one, our guide to condex insurance in Maine explains how the association’s policy and your own unit policy should fit together.
Kittery Point and Gerrish Island waterfront homes
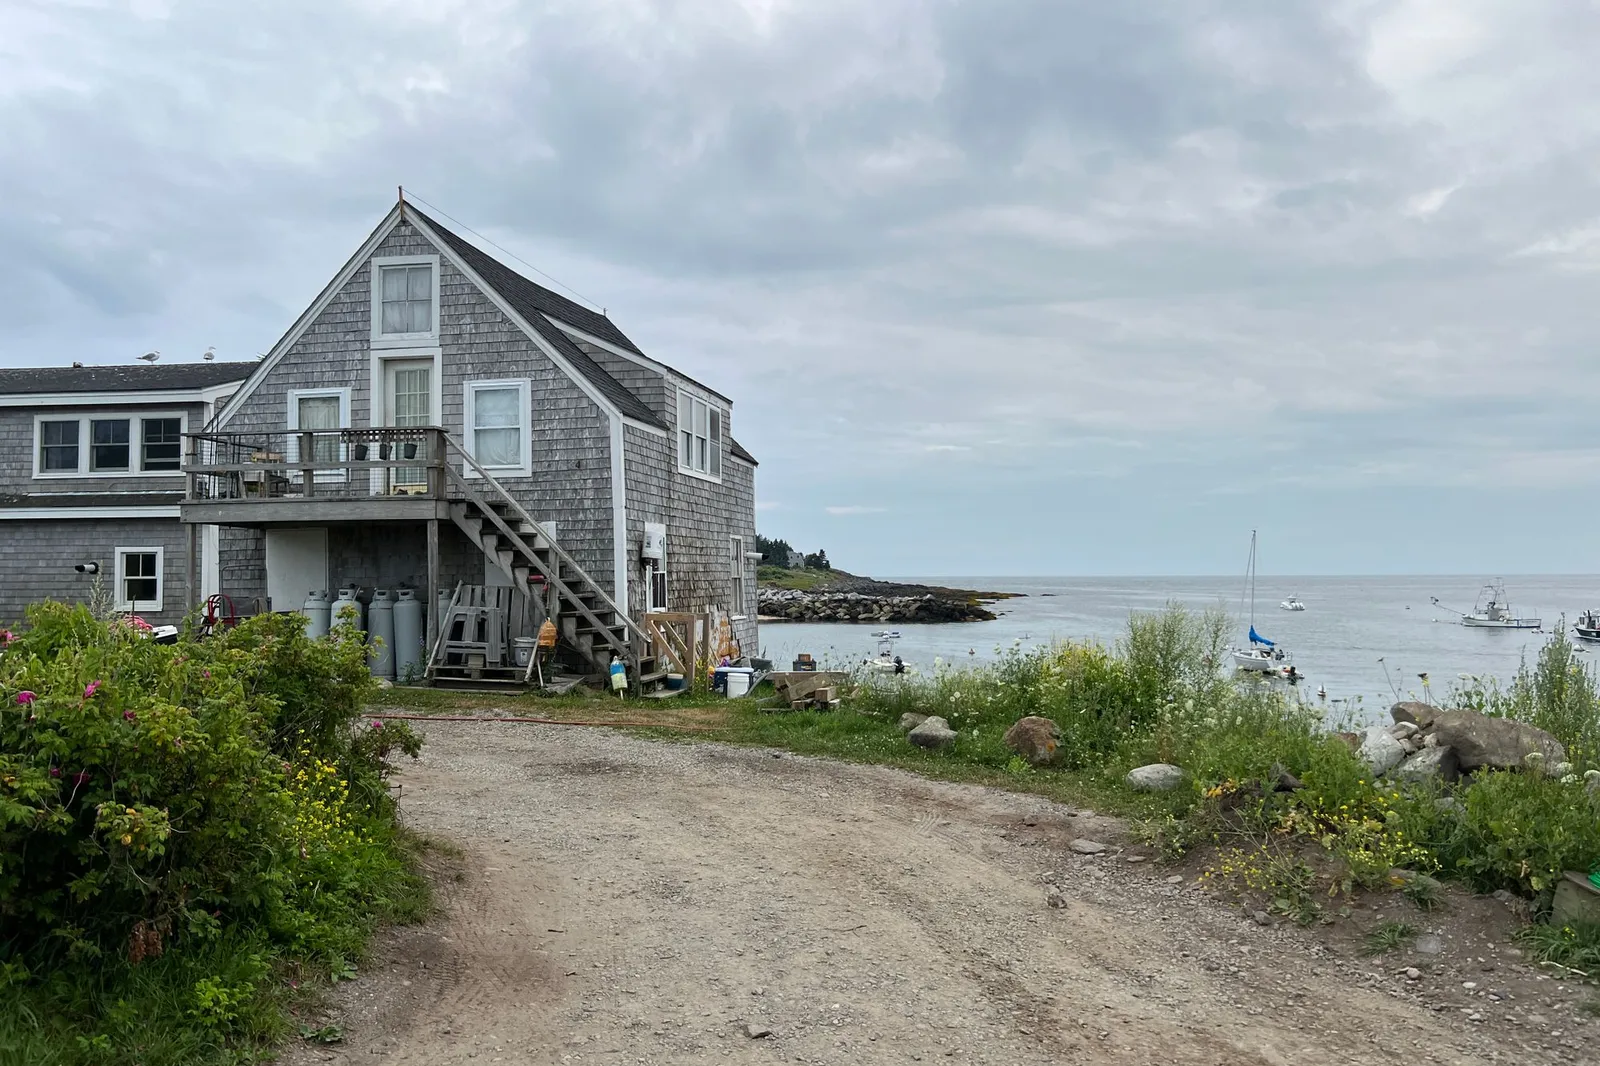
Out past Route 103, Kittery Point and Gerrish Island face the open Atlantic and the mouth of Portsmouth Harbor, while Chauncey Creek and Brave Boat Harbor reach in behind them. The Maine Bureau of Insurance lists proximity to the coast among the factors all insurers use, so a house on the water here can carry a higher premium or a percentage windstorm deductible figured on the dwelling limit. Docks, piers and seawalls are often limited or excluded, so ask how a policy treats yours.
Fewer carriers compete for homes directly on the water, which is where comparing 40+ carriers earns its keep. We also look at roof age and storm shutters, which underwriters ask about on exposed lots.
| Risk for a Kittery home | Usually covered by homeowners | Usually not covered | What to ask |
|---|---|---|---|
| Wind damage to roof and siding in a nor’easter | Yes | The part of the loss under your deductible | Is there a percentage windstorm deductible? |
| Storm surge or high-tide flooding | No | Yes | NFIP or private flood policy |
| Fire from old wiring or a wood stove | Yes | Damage from wear and tear | Updates to electrical and heating, and wood heat disclosure |
| Sewer or drain backup | No | Yes, unless added | Water backup endorsement |
| Frozen pipes in a closed-up cottage | Often, if the home was heated or properly winterized | If vacancy rules or heating conditions were not met | Vacancy terms and low-temperature alerts |
“Inflation keeps moving the goalposts on what it costs to rebuild, and older New England homes like many in Kittery feel it most. Plaster walls, old-growth trim and custom millwork are expensive to replace. A lot of these homes need much higher dwelling coverage than they carried even a few years ago. The good news is that carriers are expanding their appetite for higher-value homes, so owners have more good choices than they used to.”— Jon Merwin, Founder and CEO, Portsmouth Atlantic Insurance
Does homeowners insurance cover flooding in Kittery?
No. A homeowners policy will not pay for water that comes in from Portsmouth Harbor, Spruce Creek or a heavy rain. Look up the address on FEMA’s Flood Map Service Center; low spots along Spruce Creek, Chauncey Creek and the Foreside waterfront are worth checking even if they look dry most of the year.
We write NFIP policies and quote private flood where it is available for the property; see our flood insurance page. NFIP coverage generally starts 30 days after purchase, with some exceptions tied to a mortgage.
We’ll compare carriers for older homes, wind and flood, right from our office across the river.
Talk to our Portsmouth team: (603) 431-4020 · Start a Kittery home insurance quote
How much dwelling coverage does a Kittery home need?
Insure the cost to rebuild. The Maine Bureau of Insurance is clear that coverage is based on the estimated cost to rebuild, not market value, purchase price or tax assessment. Its guide also notes that inflation in building materials raises replacement cost even when market values fall, and that extended replacement cost coverage may add a cushion above the policy limit. For an older home with original details, ask how the replacement cost estimate handles them.
For higher-value homes on Kittery Point, Gerrish Island and the waterfront, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover. All six write in every state where we do business, including Maine, and we place Cincinnati in all 10 of our licensed states across nearly all personal lines. For larger homes, Openly and National General write up to about $5 million. Liberty Mutual may also fit Kittery homes up to $4 million in Coverage A, and higher amounts go to underwriting for approval. Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. Our Maine homeowners and second-home insurance page covers statewide details.
- Your current declarations page, including any windstorm deductible.
- The year the home was built and when the roof, heating, plumbing and wiring were last updated.
- How you heat the home, including any wood stove.
- Flood zone, elevation certificate and any current flood policy.
- Whether the home is your primary residence, a second home or a rental.
- Valuables kept at the house, like jewelry, art or a boat.
Shipyard families and military moves
Portsmouth Naval Shipyard on Seavey Island is one of Kittery’s largest employers, and many homeowners here are active-duty, civilian shipyard workers or veterans. A few insurance questions come up again and again:
- Transfers and rentals. If orders take you elsewhere and you rent the Kittery house, switch to a landlord policy before tenants move in.
- Deployments. If the house will sit empty for a long stretch, tell us. Vacancy rules can limit water and frozen-pipe claims.
- Base housing to ownership. Moving from renting to buying in Kittery means moving from renters insurance to a homeowners policy; we can line up both home and auto.
Kittery is home to many service members and veterans connected to Portsmouth Naval Shipyard, along with teachers, nurses and first responders. Hanover offers Maine group discounts on home and auto for military members and veterans, police and firefighters, nurses and medical professionals and teachers and educators. University of Maine graduates can also ask about our UMaine alumni insurance discount. We confirm eligibility when we quote.
Frequently asked questions
Can a Portsmouth, NH insurance agency insure my home in Kittery, Maine?
Yes. Portsmouth Atlantic Insurance is licensed in Maine, among 10 states, and our Portsmouth office is just across the Piscataqua River from Kittery. We insure homes in Kittery, Kittery Point, Kittery Foreside and Gerrish Island.
Does the age of my Kittery home affect my insurance?
Often, yes. The Maine Bureau of Insurance says premiums are often higher for older homes, though many insurers offer discounts if the roof, heating, plumbing and electrical systems have been updated within the past 10 to 20 years. About 46 percent of Kittery’s housing units were built before 1960, per Census estimates.
I work at Portsmouth Naval Shipyard and may be transferred. What happens to my Kittery home insurance if I rent it out?
Tell us before you move. Once tenants live in the house, a homeowners policy usually no longer fits, and you will need a landlord or dwelling policy. Your tenants should carry their own renters insurance.
Is a waterfront home on Kittery Point or Gerrish Island insured differently?
It can be. The Maine Bureau of Insurance lists proximity to the coast as a factor insurers use. Homes on the open water may carry a higher windstorm deductible, and docks and seawalls are often limited or excluded.
Sources
- Maine Bureau of Insurance, “A Consumer’s Guide to Homeowners Insurance”
- Maine Bureau of Insurance, “Factors Affecting Your Premium”
- Maine Bureau of Insurance, “Licensee Search”
- FEMA, “Flood Map Service Center”
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 “Year Structure Built”
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25004 “Vacancy Status”
This page is general information, not a policy. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Your policy documents control.
Year-round house, waterfront home or cottage, we’ll compare carriers from our Portsmouth office.
Talk to our Portsmouth team: (603) 431-4020 · Request a Kittery home insurance quote
By Jon Merwin, Founder and CEO
Portsmouth Atlantic has been an independent agency since 2005, is licensed in 10 states, works with 40+ carriers and has earned 1,000+ Google reviews and over 2,000 testimonials. Meet our team.