
By Jon Merwin, Founder and CEO · Updated October 29, 2026
Much of Rye’s high-value housing faces the open Atlantic. Shingle-style summer houses converted to year-round homes, newer oceanfront builds along Route 1A, harbor properties and large homes on inland acreage all sit within a few miles of each other. The ocean shapes how almost every one of them is insured.
Portsmouth Atlantic Insurance is an independent agency based in Portsmouth, a short drive from Rye, working with 40+ carriers. We shop most of our carriers for Rye homes, and we quote Cincinnati and Chubb, two similar high-value carriers that write homes at any dwelling limit. This page covers Rye’s neighborhoods, the coastal risks underwriters look at, and how carriers fit at different home values. For other towns, see our New Hampshire high-value home insurance hub. Have a high-value or collector car? See high-value auto insurance in New Hampshire.
This page is for owners and buyers of larger Rye homes, from oceanfront houses on Route 1A to harbor properties and inland homes on bigger lots.
Rye Neighborhoods and Home Types
Oceanfront along Route 1A
Homes facing the ocean along Route 1A are the most exposed properties in town. The Rockingham Planning Commission notes that Route 1A runs the length of Rye and that parts of it are highly susceptible to coastal flooding and damage during storms (Rockingham Planning Commission, Case Story: Rye). For an oceanfront home, expect underwriters to focus on elevation, flood zone, roof age and attachment, window and door protection, and how the house is secured when it is empty.
Rye Harbor
Rye Harbor and its marinas appear in the town’s Tides to Storms vulnerability assessment as areas affected by projected sea-level rise and storm-surge scenarios (Rockingham Planning Commission, Tides to Storms vulnerability assessment for Rye (2015)). Harbor-side homes often come with docks, boats and moorings, each of which needs to be addressed separately. A homeowners policy usually offers limited coverage for boats and waterfront structures, so we review those items one by one.
Wallis Sands and the Odiorne Point area
The northern shoreline near Wallis Sands and Odiorne Point mixes beach-adjacent homes with properties set back on higher ground. The same assessment lists Wallis Sands State Park and Odiorne State Park among the places affected under higher sea-level-rise plus storm-surge scenarios (Rockingham Planning Commission, Tides to Storms vulnerability assessment for Rye (2015)). Two homes a few hundred feet apart can have very different flood exposure here, so we check each address on the current map.
Rye Beach, Jenness Beach and inland Rye
Around Rye Beach and Jenness Beach, larger older homes sit close to newer construction. Many older homes have been renovated more than once, and the dwelling limit often lags behind. Farther inland, high-value homes on bigger lots face less surge exposure but the same wind, ice and winter-storm questions as the rest of the Seacoast, plus the usual focus on rebuild cost and water damage from inside the house.
Coastal Risks for Rye Homes, With Sources
- Flood zones and building rules: Rye’s floodplain ordinance adopts FEMA’s Rockingham County flood study and maps dated January 29, 2021, and covers Zones A, AE, AO and VE. New, substantially improved or substantially damaged structures in Zone VE must be elevated on pilings and columns (Town of Rye Code, Chapter 60: Floodplain Management).
- Sea-level rise and surge: The town’s Tides to Storms assessment found state and local culverts and five bridges affected by projected sea-level rise and storm surge, mostly supporting Routes 1A and 1B (Rockingham Planning Commission, Tides to Storms vulnerability assessment for Rye (2015)).
- Erosion and shoreline: Rye’s shoreline is protected by a mix of sand and cobble beaches, bedrock outcrops, marshes, seawalls and revetments (Rockingham Planning Commission, Case Story: Rye). Seawalls and similar structures are often limited or excluded on homeowners policies.
- Nor’easters: A state science panel found that the largest storm surges recorded at Fort Point since 2003 came from nor’easters rather than hurricanes (NH Coastal Risks and Hazards Commission science panel report (2014)).
- Flood limits: NFIP building coverage is capped at $250,000 and contents at $100,000 (FloodSmart.gov (NFIP)). Look up your address in the FEMA Flood Map Service Center.
Flood is excluded from homeowners policies. See our Seacoast NH flood insurance page for NFIP and private flood on the Seacoast, and our coastal home insurance in New Hampshire guide for how wind and flood coverage fit together.
Rebuild Cost, Not Market Value
Oceanfront land in Rye is expensive, so market value is a poor guide to rebuild cost. The dwelling limit should reflect the cost to rebuild the house itself, with like kind and quality materials, at today’s labor and material costs. On the coast that can include engineered foundations, elevation, storm-rated windows and site work that inland homes do not need. For a rough first look, see our home replacement cost estimator.
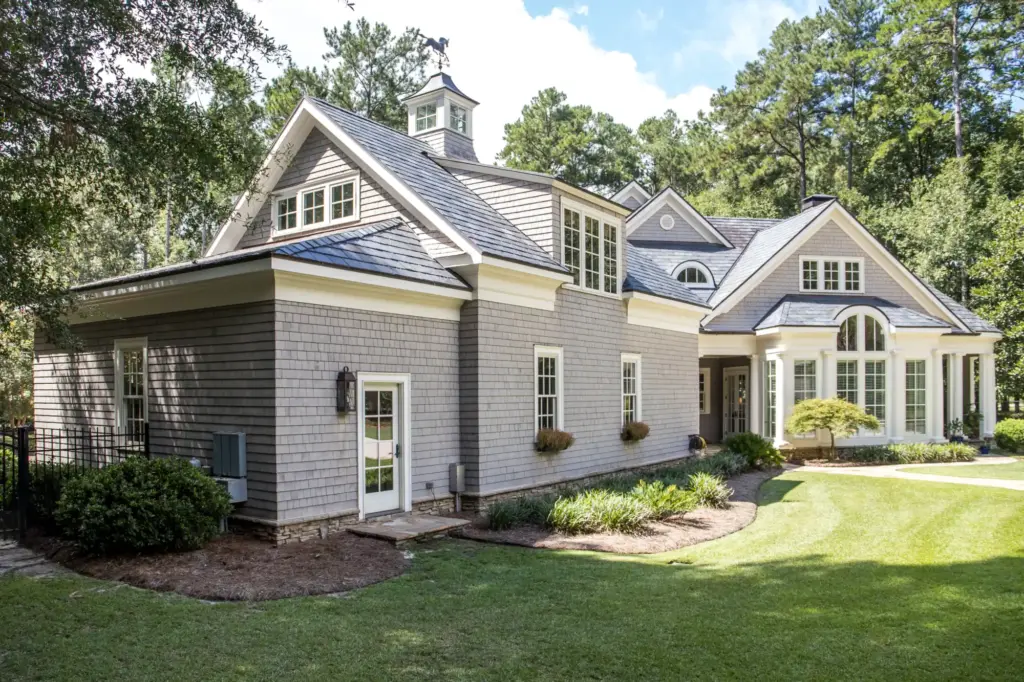
Ask about extended or guaranteed replacement cost above the dwelling limit, and about ordinance or law coverage. In Zone VE, a substantially damaged home may need to be rebuilt on pilings or columns to meet the town’s floodplain rules, which can add significant cost to a rebuild.
If you are unsure whether your current limit is right, send us your declarations page and we will compare it with a current rebuild estimate.
Wind, roofs and the wind deductible
On Rye’s open coastline, wind is the everyday risk and flood is the catastrophic one. Many coastal policies carry a separate wind or named-storm deductible, often a percentage of the dwelling limit, so on a high-value home it can be a large dollar amount. Roof age, covering and attachment, impact-rated or shuttered openings and a generator all matter to underwriters. Leak detection with automatic shutoff helps with the water risks inside the house, and carriers usually require it at higher values. Review these items each spring, before the late-summer and fall storm season begins.
Carriers We Compare for Rye Homes
Which carrier fits a Rye home depends on rebuild cost (Coverage A), distance to the ocean, and, for some carriers, how close the home is to a fire hydrant and fire station. Across our 40+ carriers, these are the ones we compare most often for larger Rye homes:
- Cincinnati and Chubb both write homes at any dwelling limit, so we quote both for Rye’s largest homes. See our Chubb review.
- Openly and National General can fit homes up to about $5 million; Openly writes up to $5 million in New Hampshire.
- Hanover can write homes up to $2 million.
- Andover can fit New Hampshire homes up to about $1.5 million, or about $1 million for homes far from a fire hydrant or fire station. See our Andover review.
- Flood is a separate policy. Beyond NFIP, we compare private flood from Neptune, Beyond Floods, Flow Flood, Aon Edge, CatCoverage and The Flood Insurance Agency. See Rye flood insurance.
Cincinnati for Rye homes
For Rye homes under about $2 million, we shop most of our 40+ carriers. Andover can fit homes up to about $1.5 million. For a Rye primary home, Hanover can write up to $2 million in dwelling coverage in New Hampshire through its Prestige and Platinum programs, subject to underwriting review. Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. It writes homes into the $10 million-plus range, so a Rye family does not have to switch carriers as a renovation pushes up the rebuild cost, and home, auto, umbrella and valuables can often sit with one company. Read our Cincinnati Insurance review.
What Changes Above $5 Million
Cincinnati and Chubb both write homes at any dwelling limit, so we quote both. Both are well-regarded high-value carriers. We quote Cincinnati and Chubb side by side when a home qualifies. Both typically inspect high-value homes inside and out, and water-leak detection is usually required. For coastal homes, expect close attention to elevation, flood zone, roof and openings, and how the house is protected when you are away. Bring your elevation certificate if you have one.
Docks, seawalls and boats
Many Rye harbor and shoreline properties include docks, floats, seawalls or revetments. These are often limited or excluded on homeowners policies, and flood policies have their own rules for structures outside the main building. List each one and confirm how it is covered for wind, flood and wave damage.
Boats kept in Rye Harbor or on a mooring usually need their own policy, and the boat’s liability coverage should line up with your umbrella. See our boat insurance and umbrella insurance pages.
Seasonal and rental use
Some Rye homes are used seasonally or rented for part of the year. A home that sits empty in winter is more exposed to frozen pipes and undetected leaks, and rental use can change what a homeowners policy covers. Tell us how the home is used so the policy matches.
If Rye is your second home, we can often coordinate it with your primary home through our 10-state licensing. See secondary and seasonal home insurance.
Elevation certificates
An elevation certificate shows your home’s elevation relative to the base flood elevation. It supports flood pricing, map amendment requests and rebuild planning. If you do not have one, a licensed surveyor can prepare it. For an oceanfront home it is one of the most useful documents you can keep on file.
Buying an oceanfront home in Rye
Before you close, ask the seller for the elevation certificate, any flood claims history, the roof’s age and covering, and records of seawall or foundation work. Ask your lender whether flood insurance will be required, and get a flood quote early, since excess or private flood can take longer to arrange than a homeowners policy.
Line up your homeowners, flood and umbrella coverage before the closing date so there is no gap. Our umbrella insurance calculator can help you think through a limit. If the house will be renovated soon after purchase, tell us now: a large project may call for builder’s risk coverage, and the dwelling limit will need to change when the work is finished.
Rye High-Value Coverage Checklist
- A rebuild-based dwelling limit that includes coastal foundation and elevation work.
- Extended or guaranteed replacement cost, since costs can spike after a regional storm.
- Ordinance or law coverage sized for Zone VE rebuild requirements.
- A wind or named-storm deductible you understand in dollars.
- NFIP plus excess or private flood for oceanfront and harbor homes.
- Written confirmation of how docks, seawalls and floats are covered.
- Separate boat coverage and an umbrella above home, auto and boat.
- Scheduled valuables for art, jewelry and wine.
- Additional living expense long enough for coastal permitting and a full rebuild.
About the author
Jonathan Merwin is the Founder and CEO of Portsmouth Atlantic Insurance and a licensed insurance agent. He started the agency in Portsmouth in 2005 and works with New Hampshire owners of larger and older homes on oceanfront and coastal homes. Read his full bio or see how we choose carriers.
Why Work With Portsmouth Atlantic
We are an independent, family-owned agency founded in 2005, with 1,000+ Google reviews and over 2,000 testimonials and access to 40+ carriers. Our Portsmouth office is at 601 Islington Street. Related pages: our Rye insurance agency page, Portsmouth high-value home insurance, our article on coastal high-value homes in Rye, New Castle and Hampton, and our New Castle high-value home insurance page. Just south along Route 1A, see North Hampton high-value home insurance.
A licensed agent will compare the carriers that fit your home’s value and review flood, wind, umbrella and valuables coverage.
Request My Rye Quote · Email insure@portsmouthatlanticins.com · Call (603) 431-4020
Rye High-Value Home Insurance FAQ
Is my Rye home in a flood zone?
Many shoreline and harbor homes are. Rye regulates FEMA Zones A, AE, AO and VE based on maps dated January 29, 2021. Check your address in the FEMA Flood Map Service Center.
What happens if my oceanfront Rye home is badly damaged?
In Zone VE, a substantially damaged home generally must be rebuilt elevated on pilings or columns under the town’s floodplain rules. Ordinance or law coverage helps pay for those added costs.
Which carriers write high-value homes in Rye?
Under about $2 million, most of our 40+ carriers are options. Andover can fit homes up to about $1.5 million, or about $1 million for homes far from a fire hydrant or fire station, Hanover up to $2 million, and Openly and National General up to about $5 million. Cincinnati and Chubb both write homes at any dwelling limit, so we quote both.
Are seawalls and docks covered?
Often only partly, or not at all. List each waterfront structure and confirm in writing how it is covered for wind, flood and wave damage.
Do I need an elevation certificate?
It is not always required, but for an oceanfront or harbor home it helps with flood pricing, map amendments and rebuild planning.
How is this page different from your Rye agency page?
Our Rye agency page covers everyday home, auto and business insurance in town. This page focuses on high-value and oceanfront homes.
By Jon Merwin, Founder and CEO. Meet our team.
Portsmouth Atlantic Insurance has been an independent agency since 2005, is licensed in 10 states and compares 40+ carriers.