
High-valueMA
Reviewed by Jon Merwin, licensed insurance agent · Updated October 2026
Key takeaways
- High-value home insurance on the Massachusetts coast is built around three things: the full cost to rebuild a custom home, how the policy handles wind and named storms, and a separate plan for flood.
- Most Massachusetts home insurers use mandatory wind deductibles near the coast, often a percentage of the dwelling limit. The Division of Insurance says the largest are in coastal Bristol, Plymouth, Barnstable, Dukes and Nantucket counties.
- Homeowners policies don’t cover flooding or storm surge. You need NFIP, excess or private flood coverage, and NFIP limits are often well below the rebuild cost of a waterfront home.
- Rebuilding in a flood zone can require meeting current flood-resistant building rules, so ordinance or law coverage and strong replacement cost terms matter.
- We compare high-value carriers including Chubb, Cincinnati, Hanover, Openly, National General and Andover, all of which write in Massachusetts.
Coastal Massachusetts high-value home insurance is a homeowners policy built for a waterfront or near-shore home whose rebuild cost, contents and liability exposure go beyond what a standard policy is designed for. A good one insures the home for what it would actually cost to rebuild to its original quality, explains the wind or named-storm deductible in plain numbers before you buy, schedules jewelry and art at agreed values, and sits next to a flood policy sized for the property. Portsmouth Atlantic Insurance is licensed in Massachusetts and works with coastal homeowners from the North Shore to the South Shore, Cape Cod and the Islands.
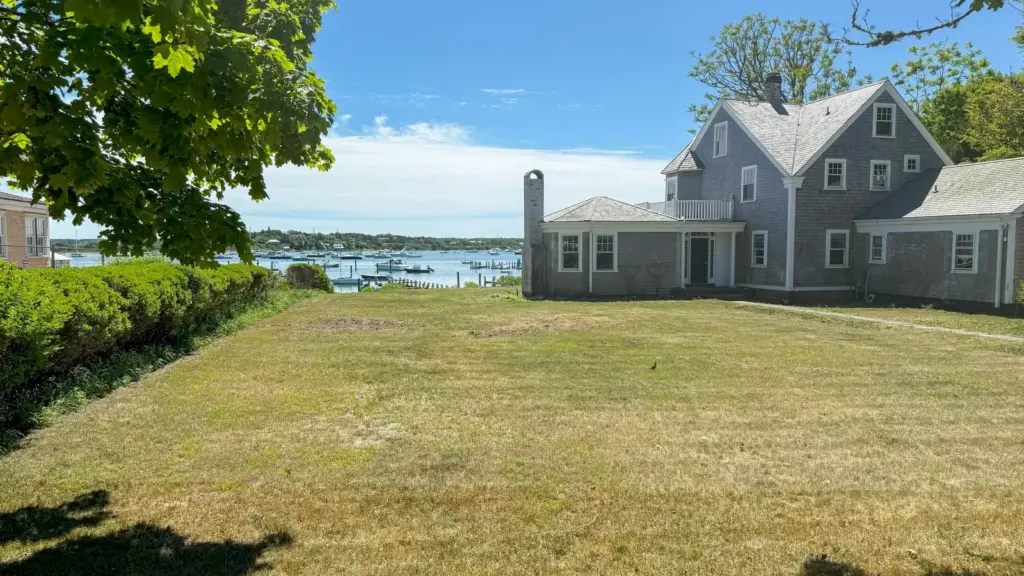
We’re an independent agency, open since 2005 and licensed in 10 states. We work with Massachusetts homeowners from our Portsmouth, NH office by phone, email or in person, and we compare 30+ carriers. For the statewide picture, start with our Massachusetts homeowners insurance page.
What makes a coastal Massachusetts home "high-value" to an insurer?
Carriers care less about the sale price and more about what it would take to rebuild. A shingle-style house on a Marblehead ledge, an antique captain’s house in Newburyport, a renovated Cohasset colonial and a newer build on a Chatham bluff can all land in high-value underwriting because of custom materials, size, historic detail or what’s inside. Underwriters usually look at:
- Rebuild cost, often set by an on-site appraisal that counts millwork, cedar shingle or slate roofs, stone, copper and specialty systems.
- Distance to the water and elevation, including the FEMA flood zone, exposure to wind off the open ocean and the age and condition of any seawall.
- Protective devices, such as central-station fire and burglar alarms, water-leak and low-temperature sensors, automatic water shutoffs and a generator.
- Occupancy, including seasonal vacancy, a caretaker, household staff or any rental use of a summer home.
How do wind and named-storm deductibles work on the Massachusetts coast?
Near the coast, most Massachusetts policies carry a second deductible for wind or named storms on top of the regular one. The Massachusetts Division of Insurance (DOI) says this deductible usually runs from 1% to 5% of the insured value of the home, can sometimes be a fixed amount instead, and may apply per event, per season or per calendar year. On a high-value home, a percentage deductible is a large number, so we show it to you in dollars on the quote.
In its report on the 2024 Massachusetts home insurance market, the DOI found that all but four of the top 25 home insurers reported mandatory wind deductibles, with deductibles up to 5% of the coverage on the main structure. The largest were in the coastal parts of Bristol, Plymouth, Barnstable, Dukes and Nantucket counties. The DOI requires insurers to disclose these deductibles clearly before you buy, and it encourages carriers to let homeowners reduce them through mitigation such as shutters, impact glass and roof and foundation anchoring.
| Location | FAIR Plan minimum named storm deductible for higher dwelling limits |
|---|---|
| Anywhere in Dukes or Nantucket County | 5% of the dwelling limit |
| Barnstable County, within half a mile of the coast | 5% of the dwelling limit |
| Barnstable County, more than half a mile from the coast | 2% of the dwelling limit |
| Rest of Massachusetts, within half a mile of the coast | 2% of the dwelling limit |
| Rest of Massachusetts, more than half a mile from the coast | A flat-dollar minimum instead of a percentage |
The table shows the FAIR Plan’s rules because they are published. Private carriers file their own, and two quotes on the same house can treat named storms very differently. That’s one of the first things we compare.
Does homeowners insurance cover storm surge or coastal flooding in Massachusetts?
No. The DOI reminds homeowners that flood damage isn’t included in a standard home insurance policy, and storm surge is flood. You can buy flood coverage from the National Flood Insurance Program (NFIP) or from a private insurer. NFIP building and contents coverage are capped at federal limits that are often well below the rebuild cost and contents of a waterfront home, so many owners add excess flood coverage over the NFIP policy or use a private flood policy with higher limits.
- Waiting period. NFIP coverage usually starts 30 days after purchase, with limited exceptions such as a loan closing. Many private flood policies have shorter waiting periods.
- Program status. As of October 5, 2026, FEMA says the NFIP is authorized through December 11, 2026.
- Your zone. Look up the property on FEMA’s Flood Map Service Center, and ask for an elevation certificate if you don’t have one.
- Private options. Private flood carriers we work with include Neptune Flood, Flow Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Which ones can write a particular Massachusetts home depends on the property.
Read more on our flood insurance page.
Own a home on the Massachusetts coast?
Ask us for a high-value home, wind deductible and flood review: (603) 431-4020.
What if a coastal home has to be rebuilt to current code?
This is where waterfront homes can get expensive after a claim. FEMA says that when a building in a mapped flood hazard area is damaged and the cost to repair it equals or exceeds 50% of its pre-damage market value, it is considered substantially damaged and must be brought into compliance with current local floodplain management standards. That can mean elevating the home. The damage can come from any cause, including wind or fire, not just flood.
Massachusetts also sets construction standards for buildings in flood hazard (A) zones, high-hazard (V) zones and coastal dunes through the state building code, and coastal projects often need review by the local conservation commission. The state’s Office of Coastal Zone Management (CZM) publishes guidance on who to contact before building or rebuilding. For insurance, this points to a few questions worth asking:
- Replacement cost terms. Is the dwelling covered at extended or guaranteed replacement cost, and how is the limit set?
- Ordinance or law coverage. How much does the policy pay toward code upgrades, demolition of undamaged parts and rebuilding to current rules?
- Loss of use. Does additional living expense last long enough for a permitted coastal rebuild?
 Expert tip from Jon Merwin, licensed insurance agent
“With the inflation of the past few years, the cost to replace a home has gone up. The goal posts have moved, and the dwelling coverage we see today is much higher than it was in the past. Insurance companies are adjusting too, and expanding their appetite for higher-value homes.”
— Jon Merwin, licensed insurance agent, Portsmouth Atlantic Insurance
Which carriers write high-value coastal homes in Massachusetts?
For high-value homes, the carriers we work with include Chubb, Cincinnati, Hanover, Openly, National General and Andover, and all six write in Massachusetts. The right one depends on the home’s value, construction, distance to the water and the coverage you want.
| Home and household | Carriers we compare |
|---|---|
| Most high-value coastal homes | Chubb, Cincinnati, Hanover, Openly, National General, Andover |
| Homes valued up to about $5 million | Chubb, Cincinnati, Openly, National General |
| Homes valued at $10 million and above | Chubb, Cincinnati |
Our carrier reviews go deeper on Chubb and Cincinnati, and our guides to insuring a $5 million home and a $10 million home cover what changes at the top of the market.
What if no insurer will write the home?
Because we work with 30+ carriers, one decline doesn’t end the search. If no company in the regular market will write a coastal property, the DOI points homeowners to the Massachusetts Property Insurance Underwriting Association, known as the FAIR Plan. FAIR Plan coverage is usually narrower than a high-value policy and carries the named storm deductibles shown above, so we walk through the differences before you decide.
Do you insure a Cape or Islands home alongside a home in another state?
Yes. Many of our clients own a primary home in New Hampshire or Massachusetts and a summer place on the Cape, the Islands or the North Shore. We’re licensed in 10 states, so one agent can line up the policies, liability limits, umbrella and renewal dates. See our page on secondary and seasonal home insurance for how vacancy and seasonal use change coverage.
Before renewal: a coastal Massachusetts high-value checklist
- Find the wind or named storm deductible on the declarations page, as a percentage and in dollars.
- Ask whether it applies per event, per season or per year.
- Get a current rebuild cost estimate, especially after renovations.
- Check ordinance or law coverage and replacement cost terms.
- Compare NFIP, excess and private flood limits with the home’s value.
- Schedule jewelry, art, wine and collections.
- Match home and auto liability to your umbrella.
- Tell your agent about seasonal vacancy, rentals, a caretaker or staff.
Frequently asked questions
What is a wind deductible on a Massachusetts homeowners policy?
It is a separate deductible that applies only to damage from wind or named storms. The Massachusetts Division of Insurance says it is usually 1% to 5% of the insured value of the home, though it can be a fixed amount, and it may apply per event, per season or per year.
Where are wind deductibles largest in Massachusetts?
The Division of Insurance reported that the largest wind deductibles are in the coastal parts of Bristol, Plymouth, Barnstable, Dukes and Nantucket counties.
Does homeowners insurance cover storm surge in Massachusetts?
No. Standard homeowners policies exclude flood, and storm surge is flood. You need a separate flood policy from the NFIP or a private insurer.
Is NFIP flood insurance enough for a high-value waterfront home?
Often not. NFIP building and contents coverage are capped at federal limits that are often below the rebuild cost of a waterfront home, so many owners add excess flood coverage or use a private flood policy with higher limits.
Which carriers insure high-value coastal homes in Massachusetts?
The carriers we work with for high-value homes include Chubb, Cincinnati, Hanover, Openly, National General and Andover, and all six write in Massachusetts. For homes valued at $10 million and above, we work with Chubb and Cincinnati.
What is the Massachusetts FAIR Plan?
The Massachusetts Property Insurance Underwriting Association, known as the FAIR Plan, is where the Division of Insurance points homeowners who can’t get coverage in the regular market. Its coverage is usually narrower than a high-value policy.
Sources
- Massachusetts Division of Insurance, "Division of Insurance Reminds Massachusetts Residents to Prepare Now for a Hurricane" (Aug. 8, 2024)
- Massachusetts Division of Insurance, "The 2024 Massachusetts Market for Home Insurance"
- Massachusetts Division of Insurance, "Resilient Homes"
- Massachusetts Property Insurance Underwriting Association, "Producer Quick Reference" (Named Storm Quick Reference)
- FEMA, "Congressional Reauthorization for the National Flood Insurance Program"
- FloodSmart.gov (NFIP), "Buy a Flood Insurance Policy"
- FEMA, "Substantial Damage Estimator Tool"
- Mass.gov, "Protecting Coastal Property from Major Storm Damage"
- Massachusetts Office of Coastal Zone Management, "StormSmart Coasts: Who to Contact and What to Do Before Building or Rebuilding"
- FEMA, "FEMA Flood Map Service Center"
Review your coastal Massachusetts home coverage
Talk to our Portsmouth team: (603) 431-4020. We compare high-value home, flood and umbrella options from 30+ carriers.
Jon Merwin, licensed insurance agent · Portsmouth, NH
Reviewed by Jon Merwin, licensed insurance agent. Meet our team.
Portsmouth Atlantic Insurance is the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews across our two offices.