
Home · Second Home · Flood · High-Value · Massachusetts
By Jon Merwin, Founder and CEO
Published October 2026 · Updated October 8, 2026
- Portsmouth Atlantic Insurance is licensed in Massachusetts and insures Nantucket homes from our Portsmouth, NH office.
- Census data counts about 57 percent of Nantucket’s housing units as held for seasonal, recreational or occasional use, compared with about 4 percent statewide. More than half of the island’s homes are second homes.
- The whole island is a local historic district. Exterior work needs Historic District Commission approval, which affects how and how fast a damaged house gets rebuilt.
- Nantucket’s FEMA flood maps are effective June 9, 2014 and include Zone AE and coastal high-hazard Zone VE. Homeowners policies exclude flood, and most policies don’t cover erosion.
- Short-term rentals need a town certificate, and state and town rules both call for at least $1 million in liability coverage.
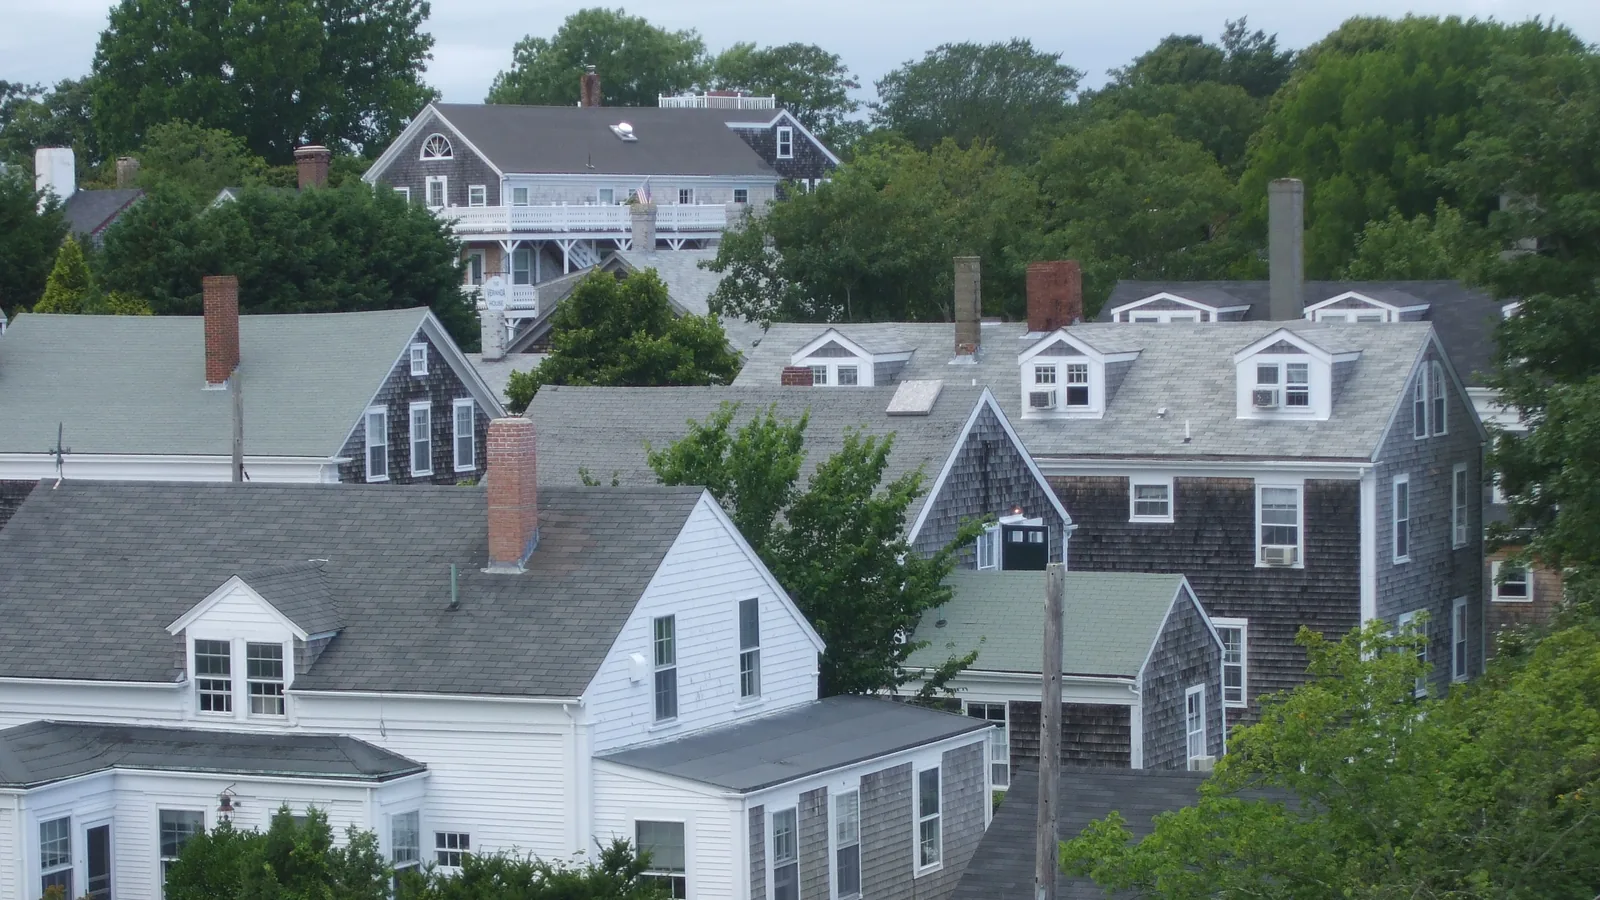
Looking for home insurance on Nantucket? Portsmouth Atlantic Insurance is licensed in Massachusetts and writes a lot of Massachusetts business from our office in Portsmouth, NH. On Nantucket we work with owners of shingled houses in town, cottages in Sconset, summer homes in Madaket and Surfside, and larger waterfront homes. As an independent agency, we compare 40+ carriers instead of selling one company’s policy. That matters on an island about 30 miles off Cape Cod, because island appetite changes from company to company, so we check which of our carriers will write your address before we quote.
Can a Portsmouth agency insure a home on Nantucket?
Yes. We hold a Massachusetts license and work with clients by phone and email, which suits owners who are often off-island. Many second-home owners keep a primary home in Boston, New Hampshire or out of state, and one agent for both homes, the cars and the umbrella keeps the coverage lined up. We also insure homes on the Cape in Chatham and Falmouth, and on Martha’s Vineyard in Edgartown. For statewide notes, see our Massachusetts second-home and vacation home insurance guide and our Massachusetts homeowners insurance page.
What does Nantucket’s housing look like?
Nantucket had 12,449 housing units in the Census Bureau’s 2019-2023 American Community Survey. About 56.7 percent of them, 7,053 units, were vacant because they are held for seasonal, recreational or occasional use, compared with about 3.8 percent statewide. Only about 40.5 percent were occupied as someone’s usual home, and owners occupied about 76.5 percent of those, compared with about 62.6 percent statewide. About 83.7 percent of all units are single-family detached houses (about 51.4 percent statewide).
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 (year structure built), from the ACS summary file. Our calculation. Estimates carry margins of error. Very small bars are drawn at a minimum width so the label stays readable.
About 17.1 percent of units were built in 1939 or earlier, many in the town core and Sconset. Much of the island is newer: about 33.5 percent of units date from 1980 through 1999 (about 18.3 percent statewide), and about 21.0 percent from 2000 or later (about 13.5 percent statewide). Old or new, every house falls under Historic District Commission review, covered below.
| Housing measure | Nantucket | Massachusetts |
|---|---|---|
| Units held for seasonal, recreational or occasional use | 56.7% | 3.8% |
| Occupied homes that are owner-occupied | 76.5% | 62.6% |
| Single-family detached houses | 83.7% | 51.4% |
| Built 1980 through 1999 | 33.5% | 18.3% |
| Built 1939 or earlier | 17.1% | 30.7% |
What changes when a Nantucket home sits empty part of the year?
Carriers ask how many months the home is occupied, who checks on it and how it is heated in winter. A house closed up from fall to spring can face freeze, water and theft risks that nobody notices for weeks, and some policies limit coverage after a stretch of vacancy. We look for policies written for seasonal homes and ask about what carriers like to see: low-temperature and leak monitoring, an automatic water shutoff, and a caretaker who checks the house on a schedule. A water backup endorsement can cover water that backs up through a drain or sump. Our page on second and seasonal home insurance covers the basics.
| Risk on Nantucket | Usually covered by homeowners | Usually not covered | What to ask |
|---|---|---|---|
| Wind damage to a roof or windows in a hurricane or nor’easter | Yes | The part under your wind or named storm deductible | Is the wind deductible a percentage, and per event or per season? |
| Storm surge or wave action into the house | No | Yes | Flood zone (AE or VE) and an NFIP or private flood policy |
| A bluff or bank eroding toward the house | No (earth movement is generally excluded) | Gradual erosion under homeowners and flood | Erosion history, setbacks, and what the flood policy’s definition of flood includes |
| A frozen pipe in an empty winter house | Often, if you took reasonable care | Can be limited if the home was vacant or unheated | Vacancy wording, heat and monitoring requirements |
| Rebuilding under Historic District Commission review | Yes, up to your limits | Code upgrades beyond ordinance or law limits | Rebuild estimate, ordinance or law limit, additional living expense |
Does homeowners insurance cover flooding on Nantucket?
No. The Massachusetts Division of Insurance (DOI) reminds homeowners that flood damage isn’t included in a standard home insurance policy. You can buy flood coverage from the National Flood Insurance Program (NFIP) or from a private insurer.
Nantucket is mapped on FEMA’s Nantucket County Flood Insurance Rate Map. When we checked FEMA’s National Flood Hazard Layer in October 2026, all 36 map panels covering the island carried an effective date of June 9, 2014, and the town’s zoning defines its Flood Hazard Overlay District by that same June 9, 2014 map. The maps show Zone AE, some Zone A and coastal high-hazard Zone VE, where FEMA expects wave action on top of the flood, and FEMA’s data for the island also include a Limit of Moderate Wave Action line along parts of the shore. Look up your address on FEMA’s Flood Map Service Center.
Nantucket’s 2021 Coastal Resilience Plan covers all 88 miles of the island’s coastline and estimates that, without mitigation, 2,373 structures are at risk from coastal flooding and erosion between now and 2070.
- Lender requirements. FloodSmart says flood insurance is required if you own a home in a Special Flood Hazard Area and have a government-backed mortgage.
- Waiting period. FloodSmart says NFIP coverage generally takes effect 30 days after purchase, with some exceptions.
- Second homes. FEMA’s NFIP coverage summary says building claims are settled at replacement cost only for a principal residence insured to at least 80% of its replacement cost. A second home is generally settled at actual cash value, which deducts depreciation, and contents are always settled at actual cash value.
- Program status. As of early October 2026, the Congressional Research Service reports that the NFIP is authorized through December 11, 2026. Our post on the December 11 flood insurance deadline explains what to do now.
- NFIP policies. We place NFIP flood policies through Selective, an NFIP Write Your Own carrier. NFIP building coverage has a federal cap and doesn’t pay for temporary housing during repairs.
- Private flood. For larger or waterfront homes we also compare private flood carriers: Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Which ones can write a particular Nantucket home depends on the property.
Our flood insurance page explains the options in more detail.
We’ll check which of our carriers will write your address and line up home, flood, auto and umbrella coverage.
Talk to our Portsmouth team: (603) 431-4020 · Start a Nantucket home insurance quote
How does erosion affect insurance on Nantucket?
Erosion is the island risk insurance handles least well. A 2021 Baxter Road planning memo prepared for the town found that the Sconset bluffs eroded more than 100 feet in places between 1990 and 2014, an average of more than four feet a year. A 2025 article in the journal Frontiers in Climate reports that 27 homes along Baxter Road have already been relocated and others demolished. At Madaket, the Massachusetts Municipal Association reported in 2025 that the coastal bank had lost 19 feet in three years.
Standard homeowners policies generally exclude earth movement, so a bank or bluff wearing away isn’t a homeowners claim. NFIP flood policies define flood to include collapse or subsidence of land along the shore caused by erosion or undermining from waves or currents exceeding anticipated cyclical levels, when that results in a flood. That is narrower than it sounds: it isn’t coverage for slow, year-by-year retreat, and neither policy pays to move a house back from the edge. If your home sits near a bluff or eroding bank, tell us at the start and have its erosion history and any survey work on hand.
How do wind and named storm deductibles work on Nantucket?
The DOI says some Massachusetts policies have a separate deductible that applies only when a named storm or wind causes damage. It is usually a percentage of the home’s insured value, generally from 1% to 5%, and may apply per event, per season or per calendar year. In its report on the 2024 Massachusetts home insurance market, the DOI said the largest wind deductibles were in the coastal parts of Bristol, Plymouth, Barnstable, Dukes and Nantucket counties.
The FAIR Plan’s published rules treat Nantucket differently from the mainland. For all of Dukes and Nantucket counties, its minimum named storm deductible is 2% at the lowest dwelling limits and 5% at higher limits, wherever the house sits on the island. Elsewhere in the state, distance from the coast changes the minimum. Private carriers file their own rules, so ask us to translate any percentage into a dollar figure for your home before you choose.
What if no insurer will write a Nantucket home?
With 40+ carriers, one decline doesn’t end the search. If no regular-market company will write the home, the DOI says the market of last resort is the Massachusetts Property Insurance Underwriting Association (MPIUA), known as the FAIR Plan, which offers basic property coverage and doesn’t cover flood. The DOI also says that as of 2025, a new FAIR Plan policy for a property in a Special Flood Hazard Area in a community overseen by the Office of Coastal Zone Management requires a separate flood policy, and CZM lists Nantucket among the communities its Cape Cod and Islands office serves.
How does the Historic District Commission affect your home insurance?
It shapes the rebuild. The town says Nantucket, with Tuckernuck and Muskeget, is a National Historic Landmark district with more than 5,000 contributing structures, and the whole island is a local historic district. Anywhere on the island, no building or structure may be built or altered in a way that affects its exterior architectural features until the Nantucket Historic District Commission (HDC) reviews and approves it with a Certificate of Appropriateness. That includes exterior equipment and driveways, and work without approval is subject to fines.
The HDC is busy. In its 2024-2025 Certified Local Government report, the town said the Commission reviewed about 2,110 certificate applications that year and often continues applications past meeting deadlines because its agendas are full.
For insurance, that points to three things: insure the house for what it would cost to rebuild with the materials and design the HDC is likely to approve, ask how much the policy pays under ordinance or law coverage for code upgrades, and check how long additional living expense coverage lasts, because review and approval add time before a builder can start. Our guide to historic home insurance goes deeper.
How much dwelling coverage does a Nantucket home need?
Enough to rebuild it on the island. The DOI notes that labor and construction costs have risen, so you may need to raise your dwelling coverage (Coverage A) to rebuild at today’s prices. On Nantucket, a rebuild estimate also has to account for getting materials, equipment and trades to the island by boat, on Steamship Authority freight boats or by barge, and for the time HDC review can add. We compare extended or guaranteed replacement cost options and set the limit with you rather than starting from a sale price.
“On Nantucket, I start with what it would take to rebuild the house on the island, not what it would sell for. Materials and crews have to come over by boat, and that can take a while. So we set the dwelling limit and the additional living expense coverage with that in mind, and then we check which of our carriers will be a good fit to insure your home.”— Jon Merwin, Founder and CEO, Portsmouth Atlantic Insurance
For higher-value homes, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover. Which ones fit depends on the home’s value and on whether a carrier will write that address.
| Home value | High-value carriers we compare |
|---|---|
| Any dwelling limit | Chubb and Cincinnati |
| Up to about $2 million | Hanover, Openly, National General and Andover |
| Up to about $3 million | Hanover, Openly and National General |
| Up to about $5 million | Openly and National General |
We also look at scheduling jewelry, art and collections at agreed values. Our coastal Massachusetts high-value home insurance page and our high net worth insurance page go deeper.
Can you rent a Nantucket home short term?
Yes, with a town certificate. Under Nantucket’s short-term rental bylaw (Chapter 123 of the Town Code) and the Board of Health and Select Board regulations (Chapter 338, last rewritten in March 2026), no one may operate a short-term rental without a certificate of registration from the Board of Health. The certificate has to be renewed every year by November 1, each rental unit needs its own certificate even on the same property, and the certificate and visitor emergency information must be posted in the unit. Rentals of 14 days or less in a calendar year, and rentals longer than 31 days, don’t count as short-term rentals. The town opened a new online registration system on October 1, 2026.
The town’s rules also reach insurance and ownership. Chapter 338 requires a certificate of insurance showing short-term rental liability coverage of at least $1 million per claim, unless the rental is offered through a hosting platform that maintains equal or greater coverage. Operators must name a local designated person, and an LLC or S corporation can register only if all of its members or shareholders are natural persons who meet the town’s ownership conditions.
Zoning is now settled, according to local news reports. The Nantucket Current reported that the November 4, 2025 Special Town Meeting approved Article 1, which allows short-term rentals in all zoning districts except a commercial-industrial district near the airport, and that the Attorney General approved it in May 2026. Some subdivisions, deed-restricted homes and associations still bar them, so check your deed and association documents.
State law applies on top of the town rules. Under Massachusetts General Laws Chapter 175, Section 4F, a short-term rental operator must carry at least $1 million in liability coverage for each short-term rental, unless the rental is offered through a hosting platform that maintains equal or greater coverage. The operator must notify the homeowners insurer, which may exclude short-term rental claims. Operators also register with the Department of Revenue. If the home is on the FAIR Plan, its rules allow occasional rental of up to 12 weeks a year for a year-round home and up to 4 weeks for a seasonal property. Tell us before you rent so the coverage fits.
What about condos, auto, boats and umbrella?
For a Nantucket condo, a unit-owner (HO-6) policy works alongside the master policy, so we read the master deductible, including any wind deductible, and add loss assessment coverage. Every carrier we write with insures condos except Progressive and Openly. Our guides to condo insurance vs. homeowners insurance and HOA master policies explain the difference. If you own a Massachusetts condo, our guide to condex insurance in Massachusetts explains how the HO-6 and the master policy fit together.
The DOI notes that homeowners and flood insurance don’t cover cars, but auto comprehensive coverage will likely cover flood damage. For collector and high-value cars we compare Cincinnati, Hagerty, Hanover and Progressive. Homeowners policies offer limited protection for watercraft, so most boats need their own policy; see our boat and watercraft insurance page.
An umbrella policy adds liability limits over your homes, cars and boat. It is worth a close look if you rent the house, host guests all summer, have a pool or own more than one home, and we check that the umbrella carrier accepts any rental exposure.
- Your flood zone from FEMA’s map (AE, VE or other) and any elevation certificate
- Your current declarations page, including any wind or named storm deductible, as a percentage and in dollars
- How many months a year the home is occupied, and who checks on it when it is empty
- Heat, water shutoff and any leak monitoring; distance to any bluff or eroding bank, and any erosion history or coastal permits
- Rental plans, your Nantucket short-term rental certificate and your state registration
- Your cars, any boat, and your current liability and umbrella limits
Nantucket home insurance FAQs
Can an insurance agency in New Hampshire insure my home on Nantucket?
Yes, if the agency is licensed in Massachusetts. Portsmouth Atlantic Insurance is, and we work with Nantucket owners by phone or email from our Portsmouth, NH office. We check which of our carriers will write your address.
Do I need flood insurance on Nantucket?
If the home is in a Special Flood Hazard Area, such as Zone AE or VE on Nantucket’s June 9, 2014 FEMA map, and has a government-backed mortgage, flood insurance is required. Outside those zones it is optional, but homeowners policies don’t cover flood, and NFIP coverage generally starts 30 days after purchase.
Does insurance cover erosion on Nantucket?
Usually not. Homeowners policies generally exclude earth movement. NFIP flood policies include collapse of shoreline land caused by waves or currents exceeding anticipated cyclical levels when that results in a flood, but they don’t cover gradual erosion, and neither policy pays to relocate a house.
What is a named storm deductible on a Nantucket home?
It is a separate deductible that applies when a named storm or wind causes damage. The Division of Insurance says these generally run from 1% to 5% of the home’s insured value. On the FAIR Plan, the minimum anywhere on Nantucket is 2% at the lowest dwelling limits and 5% at higher limits.
Do I need a certificate to rent my Nantucket home short term?
Yes. Nantucket requires a Board of Health certificate for each rental unit, renewed every year by November 1, and proof of at least $1 million in liability coverage per claim unless the hosting platform carries equal or greater coverage. State law also requires notice to your insurer.
Does the Historic District Commission affect insurance on a Nantucket home?
It can affect the rebuild. The whole island is a local historic district, and exterior changes need a Certificate of Appropriateness from the Historic District Commission. Ask about rebuild cost with approved materials, ordinance or law coverage and how long additional living expense coverage lasts.
Sources
- Massachusetts Division of Insurance, “Division of Insurance Reminds Massachusetts Residents to Prepare Now for a Hurricane” (Aug. 8, 2024)
- Massachusetts Division of Insurance, “The 2024 Massachusetts Market for Home Insurance”
- Massachusetts Division of Insurance, “Massachusetts Property Insurance Underwriting Association”
- Massachusetts Property Insurance Underwriting Association, producer reference (named storm deductible and occasional rental rules)
- Massachusetts Office of Coastal Zone Management, “CZM Cape Cod and Islands Region”
- FEMA, National Flood Hazard Layer map service (Nantucket panel effective dates and flood zones, checked October 2026)
- FEMA, “Flood Map Service Center”
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- FEMA, “National Flood Insurance Program Summary of Coverage” (definition of flood; replacement cost and actual cash value)
- Congressional Research Service, “What Happens If the National Flood Insurance Program (NFIP) Lapses?” (updated Sept. 11, 2026)
- Town of Nantucket, Zoning Bylaw amendment, Flood Hazard Overlay District (FIRM dated June 9, 2014)
- Town and County of Nantucket, “Nantucket Coastal Resilience Plan” (2021)
- Arcadis for the Town of Nantucket, “Baxter Road Long-Term Planning” final memo (Oct. 20, 2021)
- Frontiers in Climate, “Retreat in real time: Nantucket’s balancing act along a changing coast” (2025)
- Massachusetts Municipal Association, “Nantucket pilot program seeks to mitigate coastal erosion” (2025)
- Town of Nantucket, “Historic District Commission”
- Town of Nantucket, Certified Local Government Report, July 2024 to June 2025
- Town of Nantucket, “Short-Term Rentals”
- Town of Nantucket, Short-Term Rentals FAQs
- Town of Nantucket Code, Chapter 123, Short-Term Rentals
- Town of Nantucket Regulations, Chapter 338, Short-Term Rental Property (amended March 19, 2026)
- Nantucket Current, “Island Voters Legalize Short-Term Rentals Without Restrictions” (Nov. 4, 2025)
- Nantucket Current, “Attorney General Upholds Nantucket’s Vote To Legalize Short-Term Rentals, Rejecting Legal Challenge” (May 18, 2026)
- Nantucket Current, Select Board decision on short-term rental restrictions in the Richmond development (2026)
- Massachusetts General Laws, Chapter 175, Section 4F
- Massachusetts Division of Insurance, “Short-Term Rental Insurance”
- Massachusetts Department of Revenue, “Room Occupancy Excise Tax” (updated April 8, 2026)
- Steamship Authority (Hyannis to Nantucket passenger and freight service)
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, tables B25004 “Vacancy Status”, B25034 “Year Structure Built”, B25024 “Units in Structure” and B25003 “Tenure”
This page is general information, not a policy or legal advice. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Local rules change, so check current town rules before you build or rent. Your policy documents control.
Town house, Sconset cottage or waterfront home, we’ll check which carriers will write it from our Portsmouth office.
Talk to our Portsmouth team: (603) 431-4020 · Request a Nantucket home insurance quote
By Jon Merwin, Founder and CEO
Portsmouth Atlantic has been an independent agency since 2005, works with 40+ carriers, has earned 1,000+ Google reviews and over 2,000 testimonials from client surveys. We don’t charge agency or broker fees. Meet our team.