
Flood · NH + CT
Reviewed by Jon Merwin, Founder and CEO
Published: October 7, 2026 · Updated: October 7, 2026
- As of Oct. 6, 2026, FEMA says the National Flood Insurance Program is authorized through 11:59 p.m. on December 11, 2026.
- A lapse would stop new NFIP policies and renewals, but existing policies would stay in force through their one-year terms.
- Valid claims could still be paid from available funds, though a drained fund could slow payments.
- New NFIP coverage typically has a 30-day wait, with exceptions for coverage tied to certain mortgage transactions.
- Private flood insurance is a second route. Compare it with NFIP before a December closing or renewal.
Congress has extended the National Flood Insurance Program’s authority through December 11, 2026. If it doesn’t act again, FEMA would have to stop issuing and renewing NFIP policies after that deadline. Policies already in force wouldn’t disappear, and valid claims could still be paid from available funds.
So what does that mean if you own a house near the water in Rye or Hampton, or you’re closing on a Stratford shoreline home in December? Don’t assume another extension will land in time. Start the insurance and lender conversation now, while there’s still room on the calendar.
December 11, 2026
As of Oct. 7, 2026, that’s 65 days away.
FEMA says authorization ends at 11:59 p.m. on December 11, 2026, unless Congress acts.
When does the NFIP expire for New Hampshire and Connecticut homeowners?
As of Oct. 6, 2026, FEMA’s congressional reauthorization page says the NFIP is authorized until 11:59 p.m. on December 11, 2026. The president signed that extension on Sept. 2, 2026. Congress could move the date again, but you can’t plan a closing around a vote that hasn’t happened.
The deadline is national, but the timing feels local. On the Seacoast, homes near tidal water, the Piscataqua River, low roads and salt marsh often need a flood review. Along Long Island Sound, buyers in Stratford, Milford and Stamford usually need the lender’s flood determination before closing. The coverage requirement and the policy’s effective date have to line up with the loan.
Not sure where to start? Look over PAI’s flood insurance options for New Hampshire and Connecticut, or reach out to our Portsmouth, NH insurance team or Stratford, CT insurance team. We can check the address, the lender’s requirements and which policy routes are open.
Recent NFIP extensions and lapses
The Congressional Research Service tracks every short-term extension since 2017, including two lapses in the past year. That record is why the Dec. 11 date deserves attention, even though Congress has extended the program many times.
| Law or event | Authorization result |
|---|---|
| P.L. 118-158 | Extended through March 14, 2025 |
| P.L. 119-4 | Extended through Sept. 30, 2025 |
| NFIP lapse | Oct. 1 through Nov. 12, 2025 |
| P.L. 119-37 | Extended through Jan. 30, 2026 |
| NFIP lapse | Feb. 1 through Feb. 3, 2026 |
| P.L. 119-75 | Extended through Sept. 30, 2026 |
| P.L. 119-103 | Extended through Dec. 11, 2026 |
Source: Congressional Research Service, IN10835, updated Sept. 11, 2026; checked Oct. 6, 2026.
What would an NFIP lapse stop, and what would still work?
A lapse wouldn’t cancel every NFIP policy at midnight. CRS says flood insurance contracts entered into before the expiration would continue until the end of their one-year terms. FEMA would keep its authority to adjust and pay valid claims using available premium and reserve funds.
The real problem is getting new or renewed NFIP coverage. FEMA says it would stop selling and renewing policies, and CRS notes the program’s Treasury borrowing authority would be cut sharply. If the money available for claims ran out, claims could have to wait until Congress added funding or raised the limit.
| What would still work | What would stop or be limited |
|---|---|
| Existing NFIP policies stay in force through their current one-year terms. | FEMA stops issuing new NFIP policies. |
| Valid claims can be adjusted and paid while funds are available. | NFIP renewals stop during the lapse. |
| The federal flood insurance requirement for mortgages stays in place, and a lender may accept qualifying private flood insurance. | Some closings, refinances and coverage increases that depend on NFIP coverage may be delayed. |
| Other NFIP activities technically remain authorized. | Borrowing authority drops, which could slow claim payments after a severe storm. |
Congress has made some past extensions retroactive. Even so, a lender won’t treat a law that hasn’t passed as if it already exists, and it’s the lender, not FEMA, that enforces the flood insurance requirement on your loan.
Ask us to compare NFIP and private flood options for your address before the closing calendar gets tight. Request a flood quote or call (603) 431-4020.
Why should NH and CT homeowners start before December?
FEMA says a new NFIP policy typically has a 30-day waiting period from the date of purchase before it takes effect. There are exceptions. The most common one for buyers: there’s no wait when the coverage is bought in connection with making, increasing, extending or renewing a loan secured by the property, as long as the application and payment rules are met.
So a December buyer shouldn’t just count back 30 days and stop there. Confirm three things: what your lender requires, whether the loan exception applies, and whether the NFIP will still have authority to issue the policy on the date you need it. If you already own your home and want ordinary new NFIP coverage in effect by Dec. 11, plan to start around Nov. 11, and confirm the exact effective date with your agent.
Is private flood insurance an option if the NFIP lapses?
Yes, for many homes. A private flood policy doesn’t depend on Congress, so a lapse wouldn’t stop it from being written. PAI quotes private flood through Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge, and we put those options next to an NFIP quote so you can compare coverage, deductibles and start dates side by side. When the right fit is the National Flood Insurance Program itself, we place NFIP policies through Selective as a write-your-own carrier.
Private policies set their own eligibility rules, terms and waiting periods, and not every home will qualify for every program. Federal rules let a lender accept a private policy for the mortgage requirement when it meets certain conditions, but the lender decides whether a particular policy qualifies. Send the policy to your lender early.
New Hampshire’s own insurance officials make the same point. In an Aug. 4, 2023 New Hampshire Bulletin story carried by Seacoastonline, Insurance Department staff suggested owners of higher-value homes look at private flood options and encouraged Granite Staters to work with a local independent agent. That’s our everyday work: we’re an independent agency with 40+ carriers, and we don’t charge agency or broker fees on personal lines.
How many NFIP policies are in force in NH and CT?
FEMA’s official Policy Information by State and Community workbook shows 7,175 NFIP policies in force in New Hampshire and 30,672 in Connecticut as of July 31, 2026. These are point-in-time NFIP counts. They don’t include private flood policies, and they aren’t estimates of how many homes face flood risk.
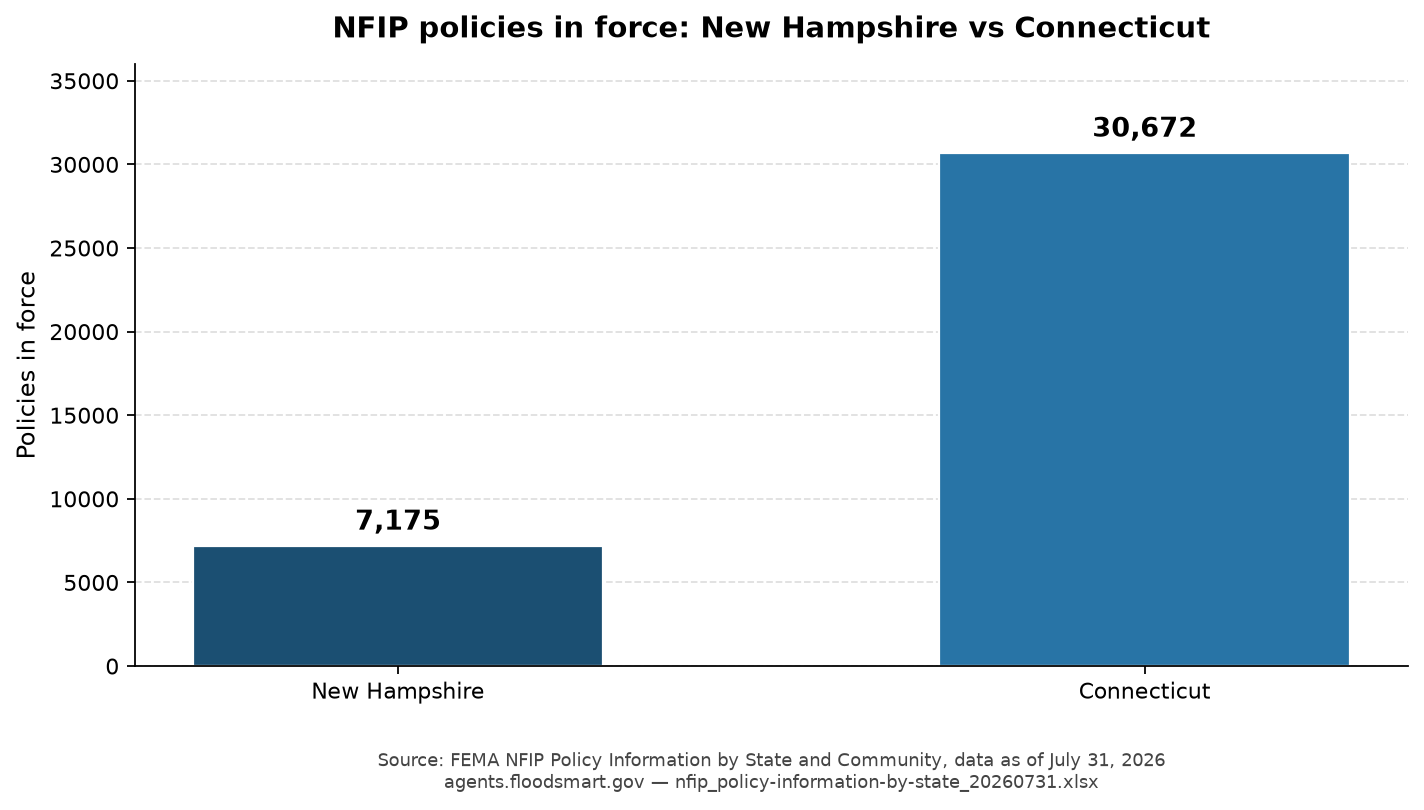
Connecticut’s larger total doesn’t mean every Connecticut home is riskier than every New Hampshire home. It reflects how many policies are in force in each state. Your own decision still comes down to the address, the building, the limits you want and your lender’s rules.
“If you’re closing or renewing in December, don’t wait to see what Congress does. Call us early with your address, closing date and lender’s requirements, and we’ll put an NFIP option next to private flood options so you can compare coverage and start dates. Then send whichever policy you choose to your lender early, so there are no surprises in closing week.”
What should a December home buyer do now?
- Ask your lender whether the property is in a Special Flood Hazard Area and what coverage has to be in place for closing.
- Send your agent the address, closing date, loan details and any elevation certificate or flood-zone paperwork you have.
- Compare an NFIP quote with private flood options your lender will accept.
- Confirm the policy’s effective date, and who will send proof of insurance to the lender and by when.
A quote isn’t the same as bound coverage, and a website form doesn’t bind insurance. For more on New Hampshire specifically, read PAI’s 2026 guide to flood insurance in New Hampshire. Connecticut shoreline buyers should call our Stratford office early enough to sort out lender questions before the walk-through and closing week.
Frequently asked questions
When does the NFIP’s current authorization expire?
As of Oct. 6, 2026, FEMA says the NFIP is authorized through 11:59 p.m. on December 11, 2026. Congress could extend it again, so re-check the FEMA reauthorization page before making a time-sensitive decision.
Would an NFIP lapse cancel my existing policy?
No. The Congressional Research Service says an NFIP contract entered into before the expiration would continue until the end of its current one-year term.
Would FEMA still pay flood claims during a lapse?
FEMA would keep its authority to adjust and pay valid claims with available funds. If those funds ran low, payments could be delayed unless Congress provided more money or raised the program’s borrowing limit.
Can I buy or renew an NFIP policy during a lapse?
FEMA says it would stop selling and renewing NFIP policies during a lapse. That could hold up a closing or a renewal that depends on NFIP coverage.
Does every new NFIP policy have a 30-day waiting period?
No. FEMA says there is typically a 30-day wait from purchase, but it lists exceptions, including qualifying coverage bought when a mortgage loan is made, increased, extended or renewed.
Can private flood insurance satisfy my lender?
It can, if the policy meets the federal requirements and your lender accepts it. Ask the lender to review the specific policy rather than assuming every private contract qualifies.
Sources
- FEMA, “Congressional Reauthorization for the National Flood Insurance Program”, last updated Sept. 28, 2026; checked Oct. 6, 2026.
- Congressional Research Service, “What Happens If the National Flood Insurance Program (NFIP) Lapses?” IN10835, updated Sept. 11, 2026; checked Oct. 6, 2026.
- FEMA, “Waiting Period for Activating Flood Policy?”, checked Oct. 6, 2026.
- FEMA, “Policy Information by State and Community,” data as of July 31, 2026.
- Seacoastonline / New Hampshire Bulletin, “1 inch of water, $25K in damage: Time to consider flood insurance, NH officials say,” Aug. 4, 2023.
- CT Mirror / Connecticut Public, “CT home flood repair costs are the highest in the nation, study finds,” Jan. 24, 2025.
Related guides
- Flood insurance in New Hampshire and Connecticut
- Flood Insurance in New Hampshire: Coverage and Options (2026)
Next step: Request a flood insurance quote for a New Hampshire or Connecticut property.
Founder and CEO · Portsmouth, New Hampshire
Reviewed by Jon Merwin, Founder and CEO.
Portsmouth Atlantic Insurance has served clients since 2005 from offices in Portsmouth, NH and Stratford, CT.
For a Seacoast home, talk to our Portsmouth team. For a Connecticut property, call our Stratford office. Start a flood quote or call (603) 431-4020.
For more on coverage across the state, visit our Connecticut insurance agency page, or call our Stratford office at (603) 431-4020.