
Home · Flood · Historic · High-Value · Massachusetts
By Jon Merwin, Founder and CEO
Published October 2026 · Updated October 9, 2026
- Portsmouth Atlantic Insurance is licensed in Massachusetts and insures Manchester-by-the-Sea homes, condos, cars and boats from our Portsmouth, NH office.
- Manchester-by-the-Sea housing stock is old: Census data put about 41 percent of its housing units in buildings built in 1939 or earlier, compared with about 31 percent statewide. Rebuild cost and code upgrades matter here.
- The town floodplain overlay district uses the Essex County Flood Insurance Rate Map and Flood Insurance Study dated July 8, 2025. Homeowners policies exclude flood.
- Coastal Massachusetts policies often carry a separate wind or named storm deductible, which the Division of Insurance says generally runs from 1% to 5% of insured value.
- Manchester-by-the-Sea has a local historic district (adopted 1975). Short-term rentals need a Select Board license, are limited to owner-occupied homes, and state law requires at least $1 million in liability coverage for each one.
Looking for home insurance in Manchester-by-the-Sea, Massachusetts? Portsmouth Atlantic Insurance is licensed in Massachusetts and writes a lot of Massachusetts business from our office in Portsmouth, NH. On the North Shore we insure older homes near the harbor, houses in and around the local historic district, Singing Beach and Magnolia-side waterfront places, condos and larger coastal homes. As an independent agency, we compare 40+ carriers instead of selling one company’s policy. In Manchester-by-the-Sea that matters, because the right carrier depends on the age of the house, how close it is to the water and whether part of it is rented.
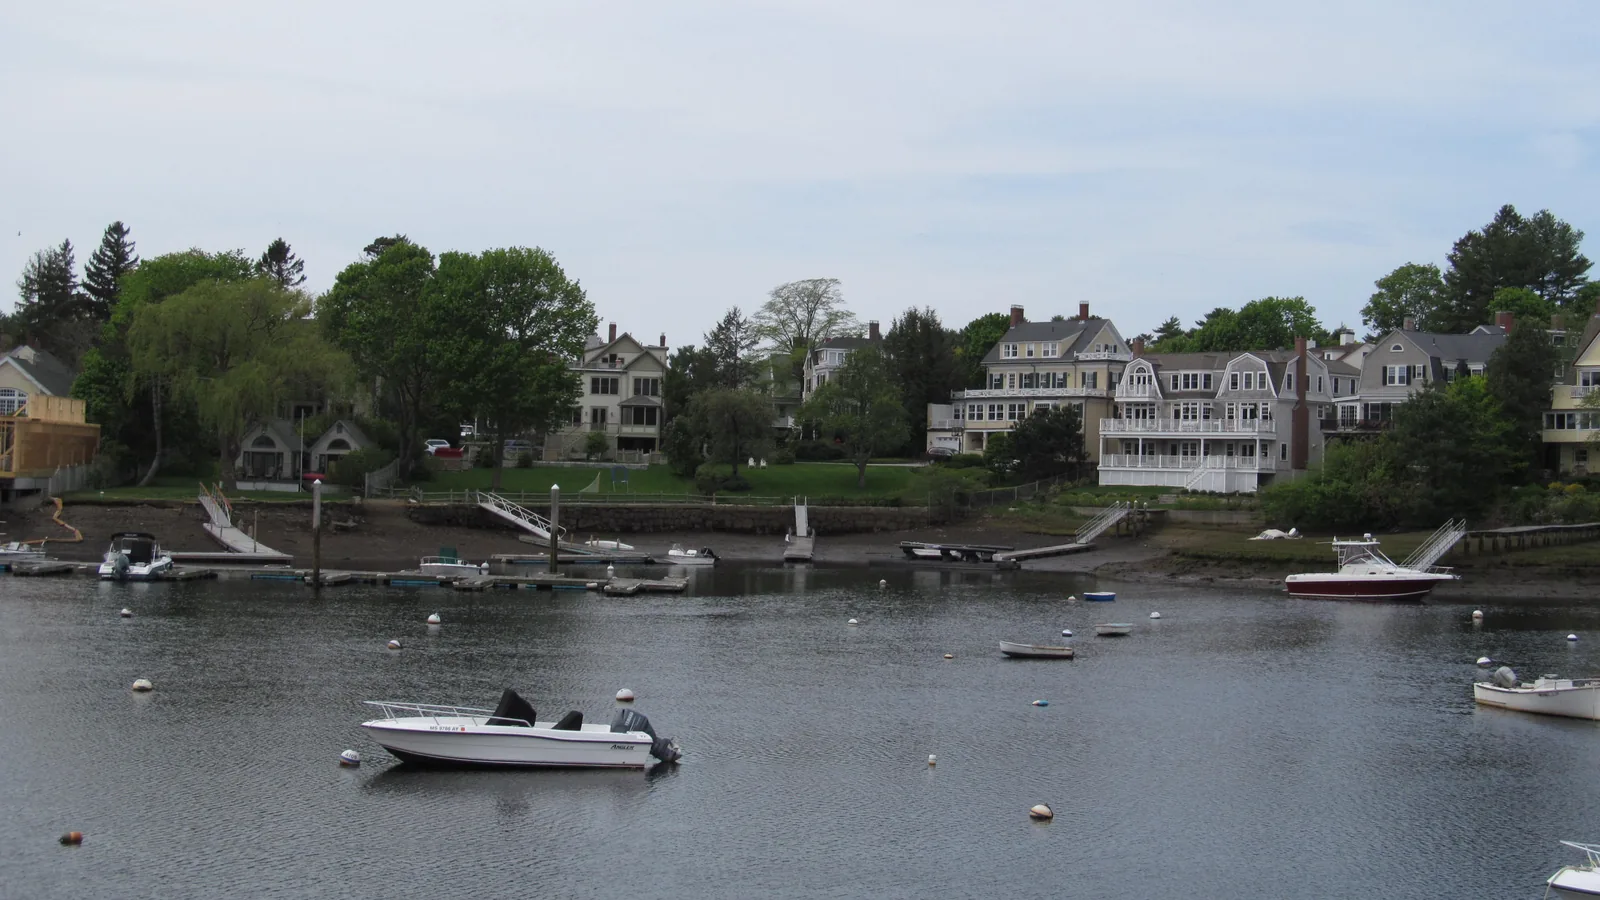
Can a Portsmouth agency insure a home in Manchester-by-the-Sea, Massachusetts?
Yes. We hold a Massachusetts license and work with clients by phone, email and video. Many North Shore owners also have a home in New Hampshire, Maine or elsewhere in Massachusetts. One agent for the homes, the cars, the boat and the umbrella keeps the coverage lined up. Along the North Shore we also insure homes in Marblehead, Gloucester and Newburyport, and on the South Shore in Cohasset. For statewide notes, see our Massachusetts homeowners insurance page.
What does Manchester-by-the-Sea housing look like?
Manchester-by-the-Sea had 2,281 housing units in the Census Bureau’s 2019-2023 American Community Survey. About 97.0 percent were occupied as someone’s usual home, and owners occupied about 70.0 percent of those, above the statewide 62.6 percent. About 3.0 percent of all units were held for seasonal, recreational or occasional use (about 3.8 percent statewide); that estimate is small and carries a large margin of error, so treat it as a rough guide. About 69.9 percent of units are single-family detached houses (about 51.4 percent statewide), and about 12.1 percent are in buildings with two to four units, compared with about 20.0 percent statewide.
Source: U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, table B25034 (year structure built), from the ACS summary file. Our calculation. Estimates carry margins of error. Very small bars are drawn at a minimum width so the label stays readable.
Age is what stands out. About 41.2 percent of the town’s units were built in 1939 or earlier, against about 30.7 percent statewide, and about 51.2 percent were built before 1960 (about 47.0 percent statewide). Older homes can be harder to rebuild to match, may have older wiring, plumbing or heating, and often need code upgrades after a loss. If you own an older house near Central Street, Bridge Street or the harbor, also check whether it falls under the local historic district, covered below. If yours is a second home, see our pages on second and seasonal home insurance and Massachusetts second-home and vacation home insurance.
| Housing measure | Manchester-by-the-Sea | Massachusetts |
|---|---|---|
| Built 1939 or earlier | 41.2% | 30.7% |
| Built before 1960 | 51.2% | 47.0% |
| Units in buildings with 2 to 4 units | 12.1% | 20.0% |
| Single-family detached houses | 69.9% | 51.4% |
| Occupied homes that are owner-occupied | 70.0% | 62.6% |
| Units held for seasonal, recreational or occasional use | 3.0% | 3.8% |
How do vacancy, wind and coastal risks show up on a Manchester-by-the-Sea policy?
Even when a home is mostly year-round, coastal exposure still shapes the policy. Wind, named storms, flood (sold separately) and rebuild cost for older waterfront houses are the usual questions. Use this table as a starting point when you review a quote.
| Risk in Manchester-by-the-Sea | Usually covered by homeowners | Usually not covered | What to ask |
|---|---|---|---|
| Wind damage to a roof or windows in a hurricane or nor’easter | Yes | The part under your wind or named storm deductible | Is the wind deductible a percentage, and per event or per season? |
| Storm surge or coastal flooding into the house | No | Yes | Flood zone (AE, VE, AO or other) and an NFIP or private flood policy |
| Water backing up through a basement drain or sump | Only with a water backup endorsement | Groundwater seepage and flood | Water backup endorsement and its limit |
| Rebuilding in the local historic district | Yes, up to your limits | Extra time and cost beyond your limits | Ordinance or law limit and how long additional living expense lasts |
| A rental guest injured on the property | Depends on the rental endorsement | Short-term rental claims if excluded | Rental endorsement or separate policy; the $1 million state minimum |
| Your car flooded in a coastal storm | No (homeowners or flood) | Yes, without comprehensive | Comprehensive coverage on the auto policy |
Does homeowners insurance cover flooding in Manchester-by-the-Sea?
No. The Massachusetts Division of Insurance (DOI) reminds homeowners that flood damage isn’t included in a standard home insurance policy. You can buy flood coverage from the National Flood Insurance Program (NFIP) or from a private insurer.
Manchester-by-the-Sea is FEMA community 250090 on the Essex County Flood Insurance Rate Map. When we checked FEMA’s National Flood Hazard Layer in October 2026, about 96 percent of the town’s area fell on map panels revised effective July 8, 2025, with a small share still on a July 16, 2014 panel. The maps show Zone AE (including some floodway), coastal high-hazard Zone VE, Zone AO and Zone A, plus areas of Zone X outside the Special Flood Hazard Area. At the April 28, 2025 Annual Town Meeting, voters adopted a new Zoning By-Law Section 10.2 Floodplain that defines the overlay district by the Essex County FIRM and Flood Insurance Study dated July 8, 2025, covering Zones A, AE, AO and VE. If you haven’t looked since 2025, check your address on FEMA’s Flood Map Service Center.
Development in the floodplain overlay district needs a town permit. The bylaw also requires the proponent to show that all other local, state and federal permits have been obtained, and it follows state rules for floodways, dunes and elevation. See the town’s floodplain bylaw text and the April 28, 2025 Town Meeting minutes.
- Lender requirements. FloodSmart says flood insurance is required if you own a home in a Special Flood Hazard Area and have a government-backed mortgage.
- Waiting period. FloodSmart says NFIP coverage generally takes effect 30 days after purchase, with exceptions such as a policy bought with a new or changed mortgage.
- Program status. As of early October 2026, the Congressional Research Service reports that the NFIP is authorized through December 11, 2026. Our post on the December 11 flood insurance deadline explains what to do now.
- NFIP policies. We place NFIP flood policies through Selective, an NFIP Write Your Own carrier. NFIP building coverage has a federal cap, and FloodSmart says NFIP policies don’t cover temporary housing during repairs.
- Private flood. For larger or waterfront homes we also compare private flood carriers: Flow Flood, Neptune Flood, Beyond Floods, The Flood Insurance Agency, CatCoverage and Aon Edge. Which ones can write a particular Manchester-by-the-Sea home depends on the property.
Water from below is separate. Standard homeowners policies generally don’t cover flood or groundwater seeping in. A water backup endorsement can cover water that backs up through drains or overflows a sump. Our flood insurance page explains the flood options in more detail.
We’ll compare carriers for older, historic and waterfront homes and line up flood, auto, boat and umbrella coverage.
Talk to our Portsmouth team: (603) 431-4020 · Start a Manchester-by-the-Sea home insurance quote
How do wind and named storm deductibles work in Manchester-by-the-Sea?
The DOI says some Massachusetts policies have a separate deductible that applies only when a named storm or wind causes damage. It is usually a percentage of the home’s insured value, generally from 1% to 5%, and may apply per event, per season or per calendar year.
The FAIR Plan’s published rules treat homes near the water differently. Outside Barnstable, Dukes and Nantucket counties, its minimum named storm deductible for a home within half a mile of the coast is 1% of the dwelling limit, rising to 2% at higher limits. Farther inland, the minimum is a flat deductible amount rather than a percentage. Private carriers file their own rules, so ask us to translate any percentage into a dollar figure for your home before you choose.
What if no insurer will write a Manchester-by-the-Sea home?
With 40+ carriers, one decline doesn’t end the search. If no company in the regular market will write the home, the DOI says the market of last resort is the Massachusetts Property Insurance Underwriting Association (MPIUA), known as the FAIR Plan, which offers basic property coverage and doesn’t cover flood. The DOI also says that as of 2025, a new FAIR Plan policy for a property in a Special Flood Hazard Area in a community overseen by the Office of Coastal Zone Management requires a separate flood policy. CZM lists Manchester-by-the-Sea among the communities its North Shore regional office serves.
Does Manchester-by-the-Sea historic district affect your home insurance?
It can affect the rebuild. The Manchester Historic District was established under Massachusetts General Laws Chapter 40C by town meeting in 1975. The bylaw covers lots facing Ashland Avenue, Bridge Street, Central Street, Church Street, Union Street and Washington Street, among others, as shown on the March 24, 1975 district plan. The Historic District Commission reviews exterior architectural features visible from a public way. Under Chapter 40C, Section 6, no building permit for an exterior alteration and no demolition permit in a local historic district can be issued until the commission issues its certificate. See the town’s historic district map and the Commission’s June 2023 design guidelines to check your address. A larger area is also listed on the National Register of Historic Places (1990); National Register listing alone does not create local design review unless other permits or funding trigger it.
Inside the local district, the guidelines say demolition of a building 50 years or older that the Commission finds valuable for its architecture may be approved only if retention is a public-safety hazard that cannot be eliminated by economic means available to the owner. Outside the district, Manchester-by-the-Sea does not yet have a townwide demolition delay bylaw. The Historic District Commission and Planning Board discussed a proposed delay bylaw in 2026 (common options under review included a 100-year age threshold and a 6- to 12-month pause), but as of our October 2026 check it had not been adopted at Town Meeting. Check current town rules before you plan a teardown. See the May 14, 2026 Historic District Commission minutes and July 27, 2026 Planning Board minutes.
For insurance, that points to three things: insure the house for a rebuild with the materials and details reviewers are likely to expect, ask how much the policy pays under ordinance or law coverage for code upgrades, and check how long additional living expense coverage lasts, because reviews add time. Our guide to historic home insurance goes deeper.
How much dwelling coverage does a Manchester-by-the-Sea home need?
Enough to rebuild it. The DOI notes that labor and construction costs have risen, so you may need to raise your dwelling coverage (Coverage A) to rebuild at today’s prices, and additions or remodeling can raise the rebuild cost too. For an older Manchester-by-the-Sea house, the estimate should account for original details, today’s code and, near the water, flood-zone construction rules. We compare extended or guaranteed replacement cost options and set the limit with you.
“Inflation over the past few years has moved the goalposts on what it costs to rebuild, and that hits hard in a town with as many older coastal homes as Manchester-by-the-Sea. We’re seeing much higher dwelling coverage than in the past. Insurance companies are adjusting too, and expanding their appetite for higher-value homes, so North Shore owners have more options than they used to.”— Jon Merwin, Founder and CEO, Portsmouth Atlantic Insurance
For higher-value and waterfront homes, we compare our six high-value home carriers: Chubb, Cincinnati, Hanover, Openly, National General and Andover. For the very largest homes, we look to Chubb and Cincinnati. We also schedule jewelry, art and collections at agreed values. Our coastal Massachusetts high-value home insurance page and our high net worth insurance page go deeper.
Can you rent a Manchester-by-the-Sea home short term?
Yes, with limits. Under General By-Law Article X, Section 20C (Short Term Paying Guest in Homes), rentals to short-term paying guests are allowed only in owner-occupied residential premises and only after the owner obtains an annual license from the Select Board. Short-term paying guests are defined as guests staying for less than six consecutive nights. Licenses expire December 31 and must be renewed each year. The application asks for the number of rooms to be rented, whether meals will be served, and a local authorized agent who can act if the owner is away; owners also agree to keep a guest registry. See the town’s General By-Laws.
Zoning rules added at the April 28, 2025 Annual Town Meeting also matter. Standard and large accessory dwelling units may not be used as short-term rentals, and accessory dwelling units may not be leased for less than six months. Check the current Zoning By-Law and Select Board license rules before you list.
State law applies everywhere. Under Massachusetts General Laws Chapter 175, Section 4F, a short-term rental operator must carry at least $1 million in liability coverage for each short-term rental, unless the rental is offered through a hosting platform that maintains equal or greater coverage. The operator must also notify the homeowners or renters insurer, and insurers may exclude short-term rental claims from a regular homeowners policy. If the home is on the FAIR Plan, its rules allow occasional rental of up to 12 weeks a year for a year-round home and up to 4 weeks for a seasonal property. Tell us before you rent so the coverage fits.
What about condos, boats, auto and umbrella?
For a Manchester-by-the-Sea condo, a unit-owner (HO-6) policy works alongside the association’s master policy. We read the master policy and its deductible, including any wind deductible, before quoting, and add loss assessment coverage. Every carrier we write with insures condos except Progressive and Openly. Our guides to condo insurance vs. homeowners insurance and HOA master policies explain the difference. If you own a Massachusetts condo, our guide to condex insurance in Massachusetts explains how the HO-6 and the master policy fit together. Next door, see Beverly, MA home insurance. Also nearby: our Essex and Hamilton pages.
For boats, Manchester Harbor and the town’s waterfront landings are busy in season. Homeowners policies offer limited protection for watercraft, so most boats need their own policy; see our boat and watercraft insurance page. Ask about liability limits that line up with your dock, tender and umbrella.
For cars, the DOI notes that homeowners and flood insurance don’t cover vehicles, but an auto policy with comprehensive coverage will likely cover flood damage. For collector and high-value cars we compare Cincinnati, Hagerty, Hanover and Progressive. Chubb and Cincinnati can also package auto with a high-value home.
An umbrella policy adds liability limits over your homes, cars and boat. It is worth a close look if you rent rooms, have a dock or pool, or own more than one home, and we check that the umbrella carrier accepts any rental exposure.
- Your flood zone from FEMA’s current map (AE, VE, AO or other), checked since the July 8, 2025 revision
- Your current declarations page, including any wind or named storm deductible, as a percentage and in dollars
- The year the house was built and the age of the roof, wiring, plumbing and heating
- Whether the home is in the Manchester Historic District (Central Street, Bridge Street, harbor-area streets and nearby lots)
- Rental plans, your Select Board short-term guest license and notice to your insurer
- For condos: the master policy, the master deductible and the bylaws
- Boats and moorings, your cars, and your current liability and umbrella limits
Manchester-by-the-Sea home insurance FAQs
Can an insurance agency in New Hampshire insure my home in Manchester-by-the-Sea, MA?
Yes, if the agency is licensed in Massachusetts. Portsmouth Atlantic Insurance is, and insures Manchester-by-the-Sea homes, condos, cars and boats from our Portsmouth, NH office, by phone, email or video.
Do I need flood insurance in Manchester-by-the-Sea?
If the home is in a Special Flood Hazard Area, such as Zone AE, VE, AO or A on FEMA’s current Essex County map, and has a government-backed mortgage, flood insurance is required. Most of the town’s map panels were revised in July 2025, so check your address again. Outside those zones flood insurance is optional, but standard homeowners policies don’t cover flood, and NFIP coverage generally starts 30 days after purchase.
What is a named storm deductible on a Manchester-by-the-Sea home?
It is a separate deductible that applies when a named storm or wind causes damage. The Massachusetts Division of Insurance says these generally run from 1% to 5% of the home’s insured value. On the FAIR Plan, the minimum for a home within half a mile of the coast outside the Cape and Islands is 1%, rising to 2% at higher dwelling limits.
Does the historic district affect my insurance?
It can affect the rebuild. Homes in the Manchester Historic District need Historic District Commission approval for many exterior changes and for demolition. Ask about rebuild cost, ordinance or law coverage and how long additional living expense coverage lasts.
Do I need a license to rent my Manchester-by-the-Sea home short term?
Yes. Short-term paying guests are allowed only in owner-occupied homes with an annual Select Board license, and stays are under six consecutive nights. Accessory dwelling units may not be used as short-term rentals. State law also requires short-term rental operators to notify their insurer and carry at least $1 million in liability coverage for each rental.
Does Portsmouth Atlantic insure boats in Manchester Harbor?
Yes. Most boats need their own watercraft policy rather than relying on a homeowners policy. We compare boat coverage alongside home, auto and umbrella so the liability limits line up.
Sources
- Massachusetts Division of Insurance, “Division of Insurance Reminds Massachusetts Residents to Prepare Now for a Hurricane” (Aug. 8, 2024)
- Massachusetts Division of Insurance, “Massachusetts Property Insurance Underwriting Association”
- Massachusetts Property Insurance Underwriting Association, producer reference (named storm deductible, eligibility and occasional rental rules)
- Massachusetts Office of Coastal Zone Management, “CZM North Shore Region”
- FEMA, National Flood Hazard Layer map service (Manchester-by-the-Sea CID 250090 panel effective dates and flood zones, checked October 2026)
- FEMA, “Flood Map Service Center”
- FEMA FloodSmart, “Buy a Flood Insurance Policy”
- Congressional Research Service, “What Happens If the National Flood Insurance Program (NFIP) Lapses?” (updated Sept. 11, 2026)
- Town of Manchester-by-the-Sea, Zoning By-Law Section 10.2 Floodplain (July 8, 2025 FIRM and FIS)
- Town of Manchester-by-the-Sea, Annual Town Meeting Minutes (April 28, 2025), Article 7 (floodplain bylaw adopted)
- Town of Manchester-by-the-Sea, Article XVI Historic District By-Law (adopted 1975)
- Manchester-by-the-Sea Historic District Commission, Design Guidelines (June 2023)
- Town of Manchester-by-the-Sea, Historic District Map
- Town of Manchester-by-the-Sea, Historic District Commission
- Massachusetts General Laws, Chapter 40C, Section 6
- Manchester-by-the-Sea Historic District Commission, meeting minutes (May 14, 2026) on a proposed demolition delay bylaw
- Manchester-by-the-Sea Planning Board, meeting minutes (July 27, 2026) on demolition delay bylaw mechanics
- Town of Manchester-by-the-Sea General By-Laws, Article X, Section 20C (Short Term Paying Guest in Homes); updated July 15, 2026
- Massachusetts General Laws, Chapter 175, Section 4F
- U.S. Census Bureau, American Community Survey 2019-2023 5-year estimates, tables B25004 “Vacancy Status”, B25034 “Year Structure Built”, B25024 “Units in Structure” and B25003 “Tenure”
This page is general information, not a policy or legal advice. Coverage, forms and availability vary by state, carrier and property, and every policy is subject to underwriting. Local rules change, so check current town rules before you build, demolish or rent. Your policy documents control.
Older house, condo or waterfront home, we’ll compare carriers from our Portsmouth office.
Talk to our Portsmouth team: (603) 431-4020 · Request a Manchester-by-the-Sea home insurance quote
By Jon Merwin, Founder and CEO
Portsmouth Atlantic has been an independent agency since 2005, works with 40+ carriers, has earned 1,000+ Google reviews across our two offices and over 2,000 testimonials from client surveys. We don’t charge agency or broker fees. Meet our team.