
Home · CT
Reviewed by Jon Merwin, licensed insurance agent
Published: [SET AT PUBLISH] · Updated: October 6, 2026
- As of Oct. 6, 2026, Connecticut treats hurricane deductibles differently from windstorm or hail deductibles.
- A hurricane deductible may apply only during a statutory window tied to a National Hurricane Center hurricane warning for any part of Connecticut, and only if the storm produced max sustained surface winds of 74 mph or more for any part of the state.
- The percentage is of Coverage A (dwelling limit), not of the loss amount. CID Bulletin PC-33 asked carriers to show both the percent and the dollar amount on the declarations page.
- Wind damage and flood damage are separate. Homeowners typically covers wind; flood needs a separate NFIP or private flood policy.
- Pull your declarations page before November 30 and confirm which deductible would apply if a named storm reaches Long Island Sound.
A hurricane deductible in Connecticut is not the same as your ordinary deductible, and it is not the same as a windstorm or hail deductible. As of Oct. 6, 2026, the Connecticut Insurance Department says an insurer may impose a hurricane deductible in lieu of the overall policy deductible only if the damage happened during a narrow statutory window and the hurricane produced maximum sustained surface winds of 74 mph or more for any part of the state. If your policy has one, both the percentage and the dollar amount should appear on the declarations page.
For owners in Stratford, Milford, Fairfield, Greenwich and other Long Island Sound towns, that distinction matters before season ends on November 30. Here is the trigger, where it shows on your declarations page, and a worked EXAMPLE using a Greenwich Coverage A limit.
What is a hurricane deductible on a Connecticut homeowners policy?
Many Connecticut homeowners policies use a flat overall deductible. A hurricane deductible is different: it is often a percentage of Coverage A (the dwelling limit), and it can replace the overall deductible when Connecticut’s statutory hurricane conditions are met.
That percentage is not a share of the damage. Bulletin PC-33 (January 2000) flagged this confusion: if Coverage A is $800,000 and the hurricane deductible is 2%, the deductible is $16,000 — not 2% of the repair bill. CID asked carriers to show both the percent and the dollar amount on the declarations page. Not every policy has a hurricane deductible; confirm your forms with your agent.
When does a hurricane deductible apply in Connecticut?
As of Oct. 6, 2026, CID’s homeowners storm-claims page sets two conditions. First, the damage must occur during a defined window tied to National Hurricane Center (NHC) warnings for Connecticut. Second, the hurricane must produce maximum sustained surface winds of 74 mph or more for any part of the state.
The statutory window:
- (A) Start: commencing not earlier than when the NHC issues a hurricane warning for any part of Connecticut; and
- (B) End: the earlier of (i) 24 hours after the NHC terminates the last hurricane warning for any part of Connecticut, or (ii) 24 hours after the NHC last downgrades the hurricane from hurricane status for any part of Connecticut.
If those conditions are not met, the hurricane deductible should not replace your overall deductible under the rule CID describes. Windstorm coverage can still respond under other deductible terms; confirm with your agent.
CT Mirror’s May 24, 2024 hurricane-season insurance piece and Connecticut Post coverage of Milford’s Woodmont Beach storms are useful local reminders to check your own declarations page.
How do I find my hurricane deductible on the declarations page?
CID says to review the declarations page for your coverages and deductibles. It is usually the first or second page of the policy packet. If a hurricane deductible applies, both the percentage and the dollar amount must be listed there.
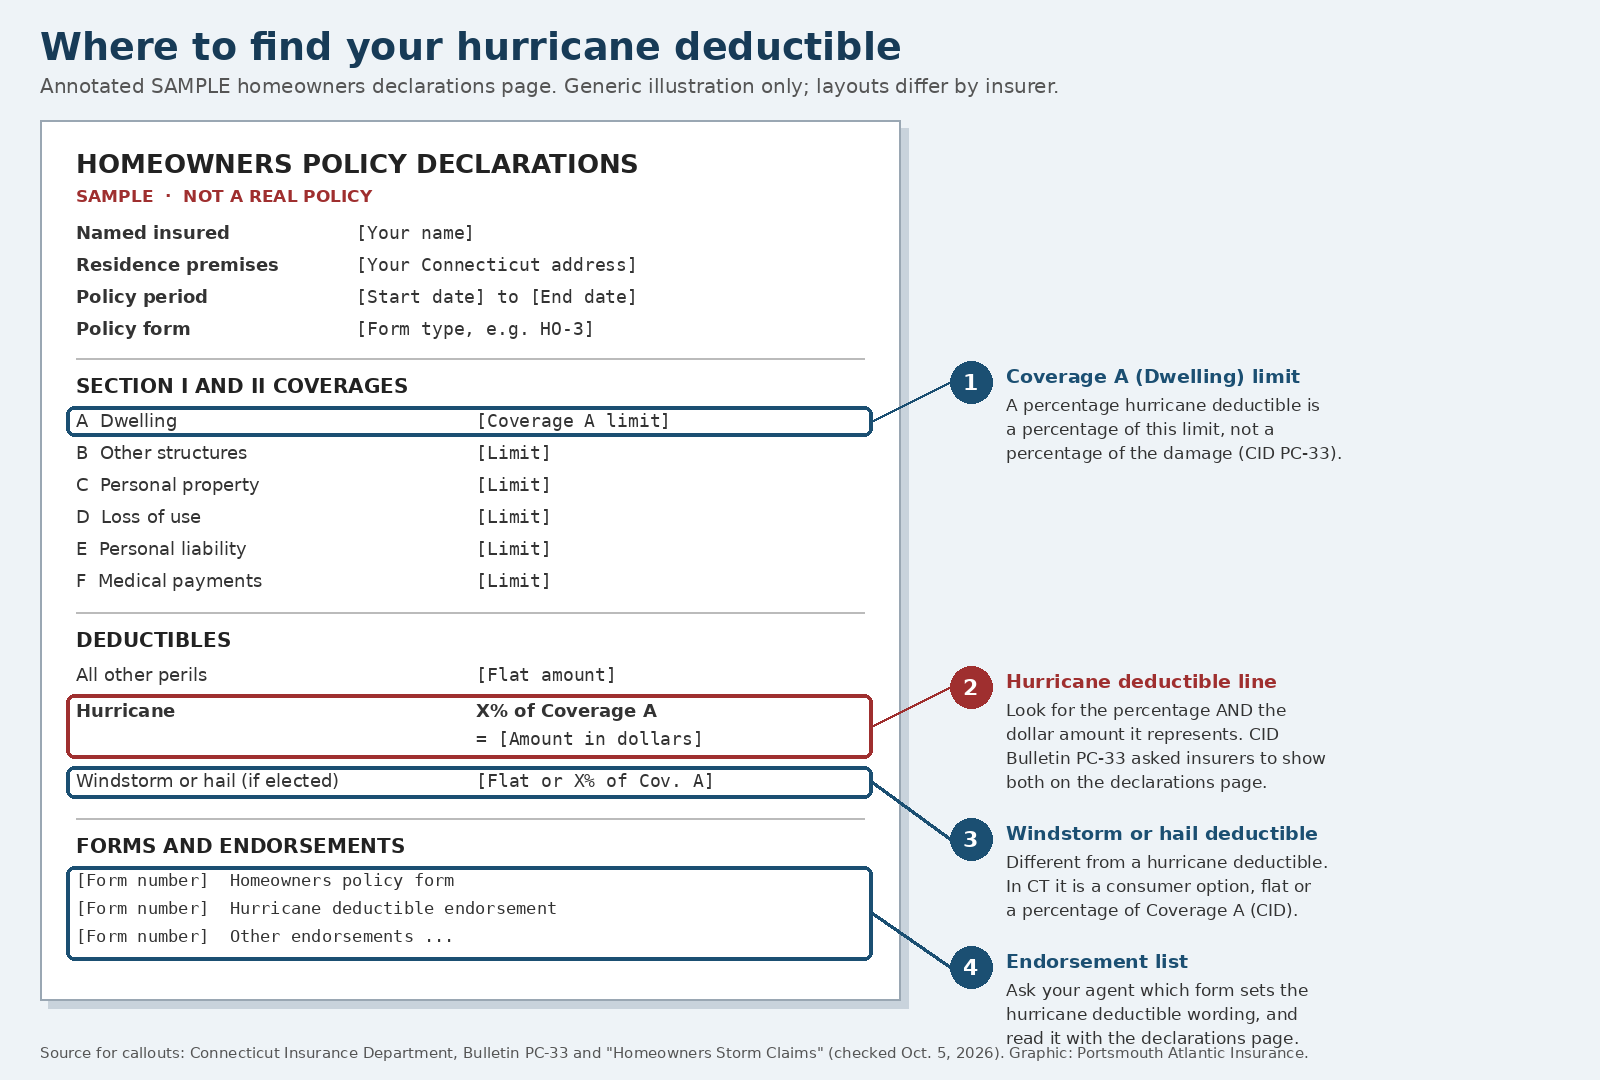
Check Coverage A, the hurricane deductible (percent plus dollars), and any separate windstorm or hail deductible. If you only see a flat “all other perils” deductible, ask whether a hurricane endorsement is on the policy.
How much could a percentage hurricane deductible be? (EXAMPLE)
Here is a worked EXAMPLE for a homeowner in Greenwich, Connecticut. These numbers are illustrative only — not a quote, premium, rate, or anyone’s real claim.
- Town: Greenwich, CT (illustrative)
- Coverage A (dwelling) limit: $800,000
- Hurricane deductible: 2% of Coverage A
- Hurricane deductible in dollars: $16,000 (2% × $800,000)
If a covered hurricane loss met Connecticut’s trigger rules, this EXAMPLE policy would apply the $16,000 hurricane deductible instead of a smaller overall deductible. Your real figures come from your declarations page.
At the same 2% with Coverage A of $1,200,000, the EXAMPLE deductible is $24,000. The hard part is confirming which deductible your forms use when the NHC has a hurricane warning for Connecticut.
How is a hurricane deductible different from a windstorm or hail deductible?
CID draws a bright line. Windstorm or hail deductibles may be a flat dollar amount or a percentage of Coverage A. In Connecticut, insurers may not mandate them; consumers may choose them in lieu of the overall deductible. Hurricane deductibles may replace the overall deductible only under the statutory warning-window and 74 mph rules above.
| Topic | Windstorm / hail | Hurricane |
|---|---|---|
| Form | Flat dollar or % of Coverage A | Often % of Coverage A; percent and dollars on declarations |
| Who chooses | Consumer may choose; not mandated in CT | May replace overall deductible only under statutory trigger |
| Trigger | Per policy / endorsement | NHC hurricane warning window for CT + 74 mph for any part of CT |
Does a homeowners policy cover flood the same way it covers wind?
No. CID says flood damage is excluded from standard homeowners, condo and renters policies. Wind from a storm can still be a homeowners claim under the policy’s wind terms and deductibles. Flood needs a separate flood policy through the National Flood Insurance Program (NFIP) or a private flood insurer. Portsmouth Atlantic places NFIP policies through Selective as a write-your-own (WYO) carrier across the agency, including for Connecticut homes. See our coastal home insurance in Connecticut guide and flood insurance page for more.
How often do named storms pass near Bridgeport and Long Island Sound?
Named-storm history does not set your deductible, but it helps explain why Fairfield County owners ask about hurricane wording. Using NOAA HURDAT2, we counted named storms within 65 nautical miles of Bridgeport from 1900 through 2025.
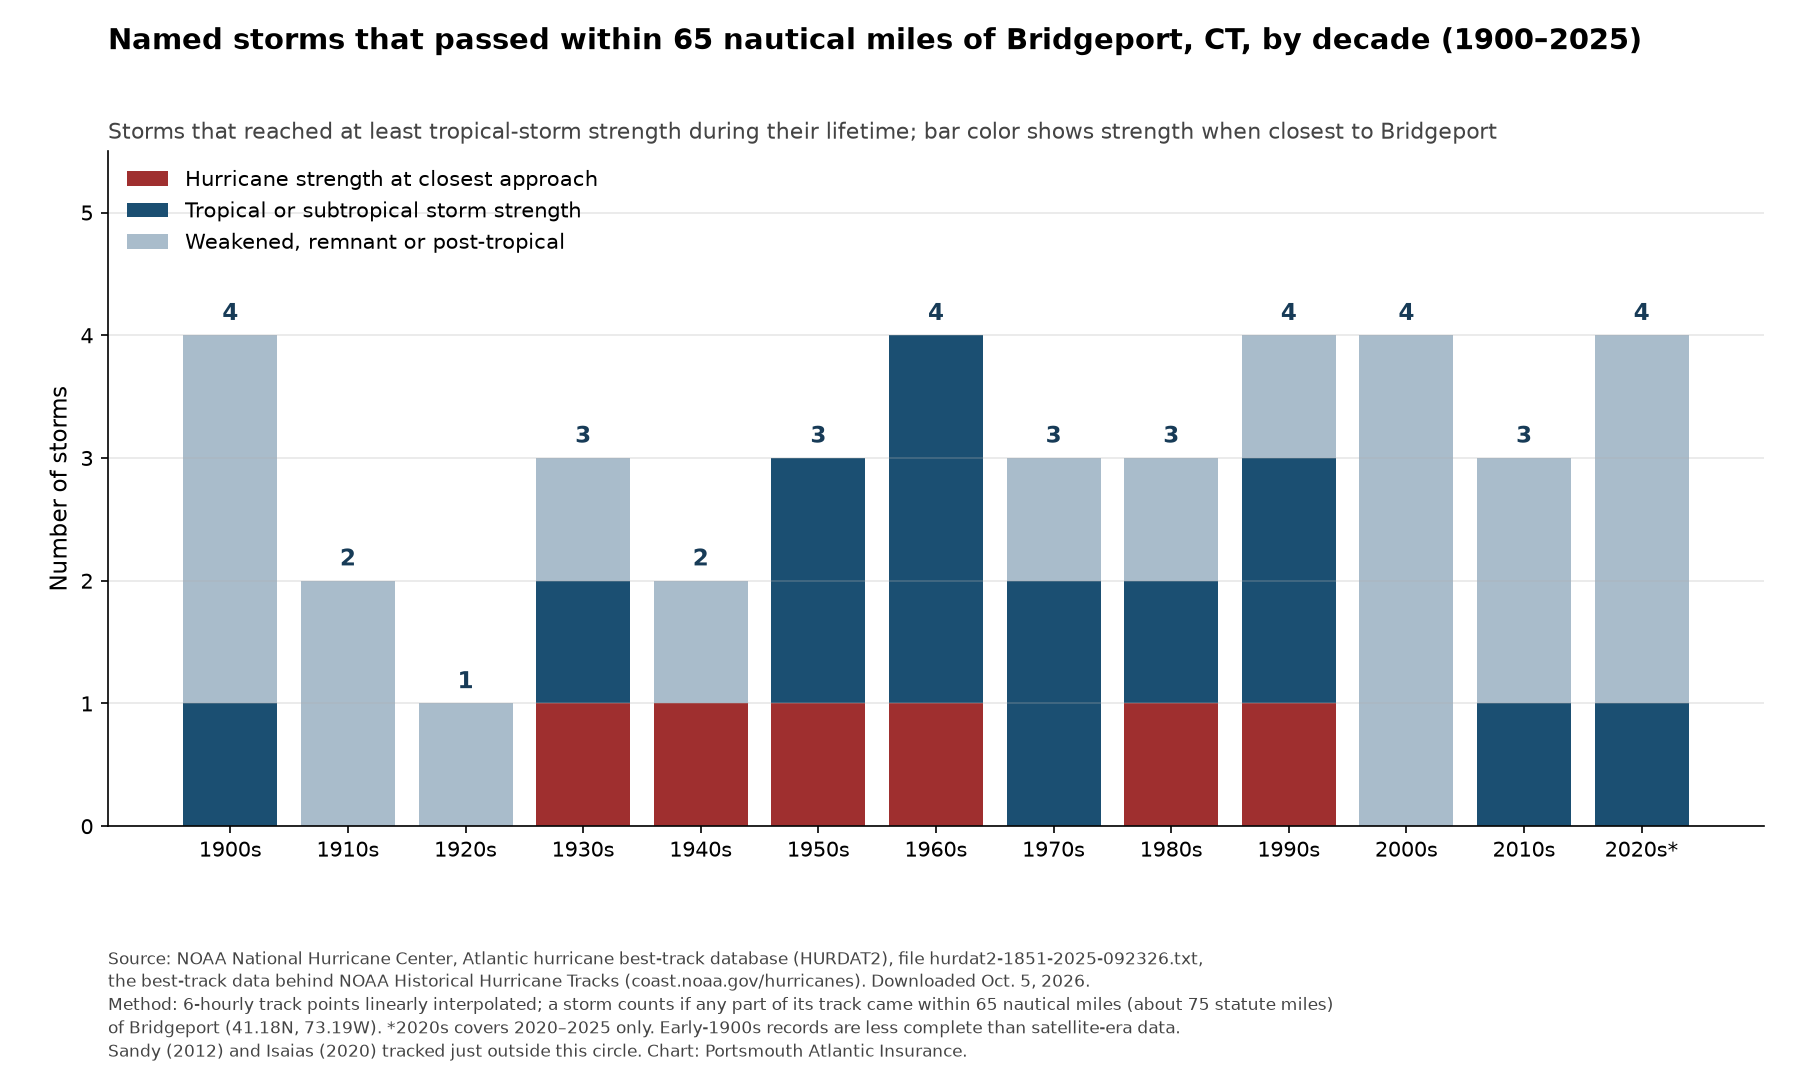
Decade totals: 1900s 4, 1910s 2, 1920s 1, 1930s 3, 1940s 2, 1950s 3, 1960s 4, 1970s 3, 1980s 3, 1990s 4, 2000s 4, 2010s 3, 2020s 4 (through 2025), including tropical storms and post-tropical named systems. Proximity to Bridgeport alone does not trigger Connecticut’s hurricane deductible rules.
Bring your declarations page to our Stratford office team. We work with 40+ carriers and charge no agency or broker fees on personal lines. Call (603) 431-4020 or start from our Connecticut homeowners insurance page.
What should Connecticut shoreline owners do before November 30?
Atlantic tropical storm season runs June 1 through November 30. CID recommends reviewing the policy yearly and especially before the season. Before November 30:
- Save a PDF or photo of the deductible section on your current declarations page.
- Confirm whether you have a hurricane deductible, a windstorm/hail deductible, both, or neither.
- Note Coverage A and the hurricane percent and dollar amount if listed.
- If you need flood coverage, start early; NFIP policies often have a waiting period.
- Milford and nearby owners can start at our Milford, Connecticut insurance agency page.
“A Connecticut hurricane deductible applies only when the state’s trigger rules are met: a National Hurricane Center hurricane warning for part of Connecticut and maximum sustained winds of 74 mph or more. When it does apply, the percentage is of your Coverage A dwelling limit, not of the damage. Pull your declarations page now and look for both the percent and the dollar amount, so you know your number before a storm reaches Long Island Sound.”
Frequently asked questions
What is a hurricane deductible in Connecticut?
A deductible—often a percentage of Coverage A—that may replace the overall deductible when Connecticut’s statutory hurricane conditions are met. As of Oct. 6, 2026, CID says the percent and dollar amount must appear on the declarations page if the policy has one.
When can an insurer apply a hurricane deductible in Connecticut?
Only if the damage occurred during the NHC hurricane-warning window for any part of Connecticut and the hurricane produced maximum sustained surface winds of 74 mph or more for any part of the state, per CID’s homeowners storm-claims page (checked as of Oct. 6, 2026).
Is a hurricane deductible the same as a windstorm or hail deductible?
No. Windstorm or hail deductibles may be flat dollar or percent of Coverage A, and in Connecticut they may not be mandated by insurers. Hurricane deductibles follow separate statutory trigger rules.
Is the percentage based on the loss or on Coverage A?
On Coverage A (dwelling limit), not on the loss amount. Bulletin PC-33 asked insurers to show both the percent and the dollar amount on the declarations page.
Does homeowners insurance cover flood damage from a hurricane?
No. Flood is excluded from standard homeowners policies. You need a separate flood policy (NFIP or private). Portsmouth Atlantic places NFIP policies through Selective as a write-your-own carrier, including for Connecticut.
When does Atlantic tropical storm season end?
CID notes that Atlantic tropical storm season runs from June 1 through November 30. Review your declarations page before the season ends and again if a hurricane warning is issued for any part of Connecticut.
Sources
- Connecticut Insurance Department, “Homeowners Storm Claims” / Understanding Your Coverage (page dated August 21, 2025; facts checked as of Oct. 6, 2026).
- Connecticut Insurance Department, Bulletin PC-33, Homeowners Insurance Wind and Hurricane Deductibles (January 2000).
- NOAA Historical Hurricane Tracks / HURDAT2 (named storms within 65 nmi of Bridgeport, CT, 1900–2025).
- CT Mirror, “Major hurricane season predicted: What to know about insurance,” May 24, 2024.
- Connecticut Post, barges aground at Milford’s Woodmont Beach.
Related guides
Next step: Talk with our Connecticut team about your homeowners deductibles, or call (603) 431-4020.
Licensed insurance agent, Portsmouth Atlantic Insurance · Stratford, Connecticut
Portsmouth Atlantic Insurance has served clients since 2005 from offices in Portsmouth, NH and Stratford, CT, with 1,000+ Google reviews across our two offices.
Call our Stratford office team at (603) 431-4020. We compare options across 40+ carriers and charge no agency or broker fees on personal lines. Review Connecticut homeowners coverage.