
By Jon Merwin, Founder and CEO, Licensed Insurance Advisor
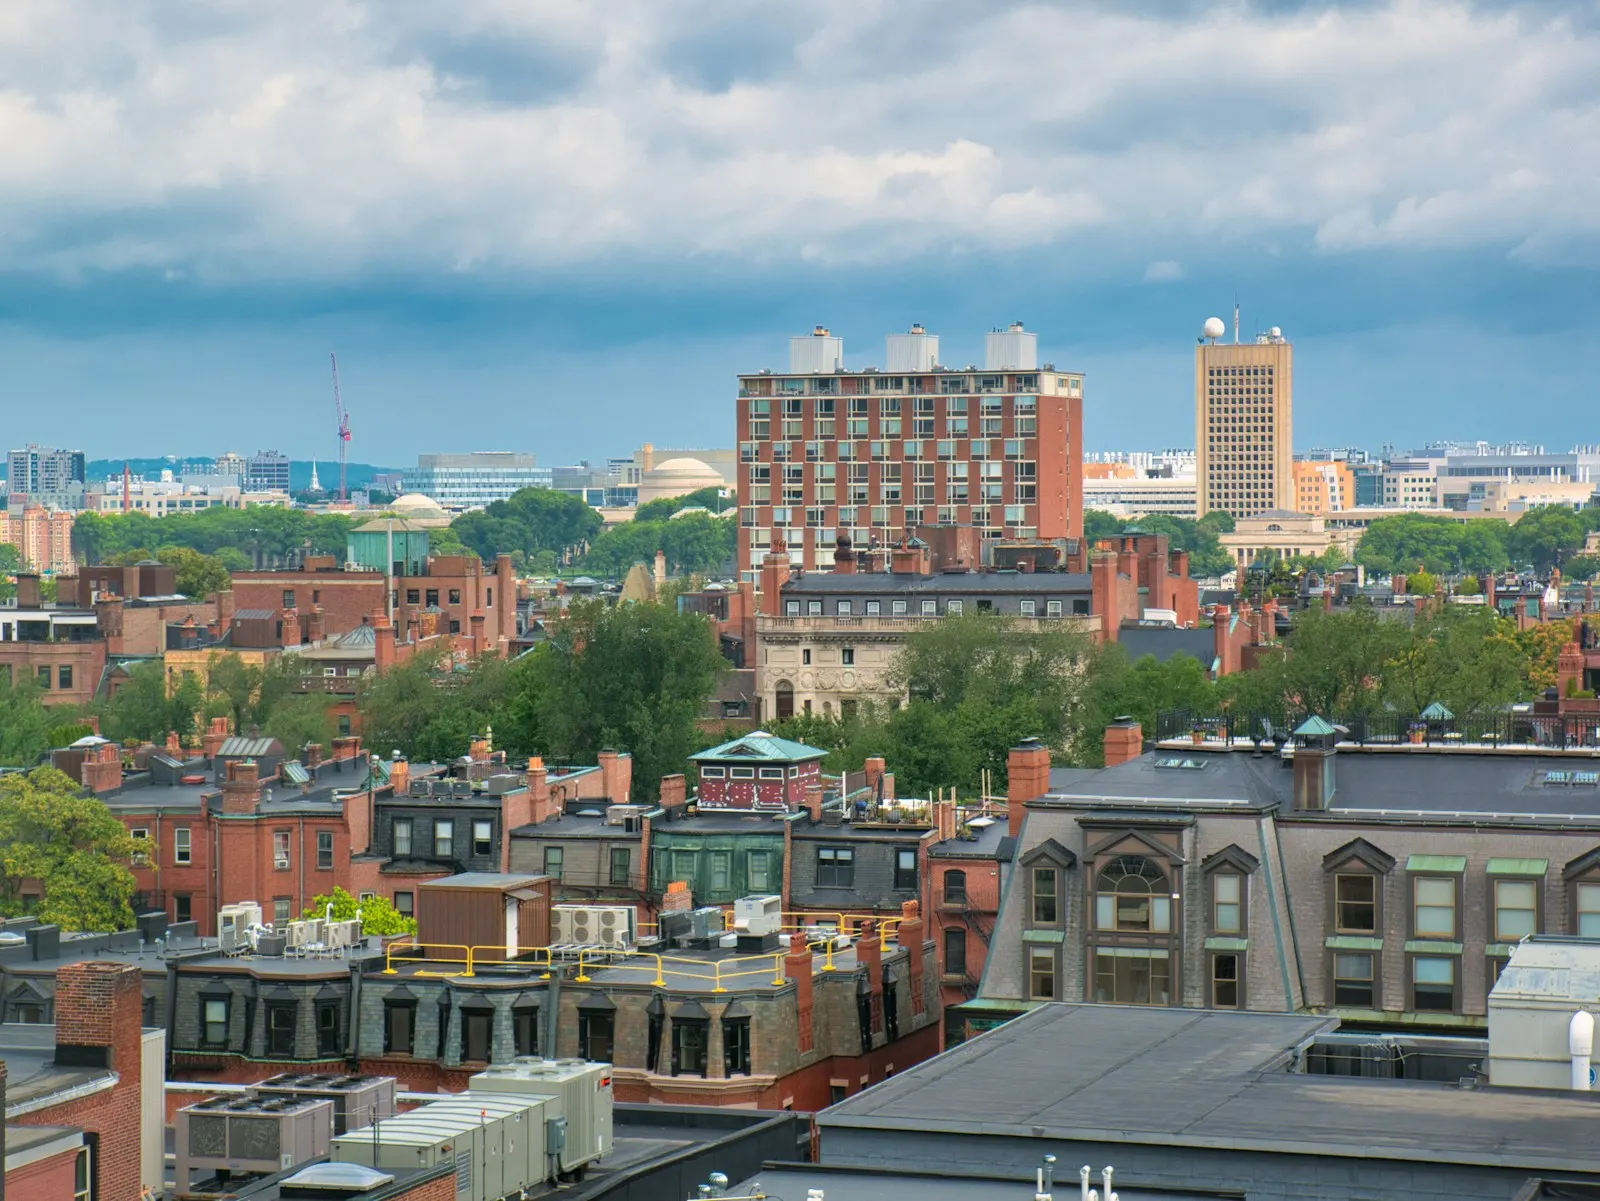
Portland packs a lot of rental housing onto a small peninsula. About 57% of occupied homes are rented, nearly half of the city’s housing units were built before 1940, and about 35% of units sit in buildings with five or more units (U.S. Census Bureau, American Community Survey 2024 1-year estimates). Brick blocks in the West End, wood-frame multi-families on Munjoy Hill, mixed-use buildings near the Old Port and newer waterfront projects all raise different underwriting questions, and they all have to get through Maine winters.
Portsmouth Atlantic Insurance is a family-owned independent agency licensed in Maine. We compare 40+ carriers, and for Maine apartment buildings we place coverage with Vermont Mutual, Concord Group, Safety, Andover Companies and Providence Mutual. We don’t have a Maine office; Portland owners work with us from our Portsmouth, NH office by phone, email and online. We don’t charge any fees. Call (603) 431-4020 or start a quote.
Key facts for Portland apartment owners
- Renter share: about 56.9% of occupied homes in Portland are renter-occupied (ACS 2024 1-year).
- Age: about 47% of the city’s housing units were built in 1939 or earlier.
- Building size: about 26% of units are in two- to four-unit buildings, and about 35% are in buildings with five or more units.
- Registration: Portland requires long-term rental units to be registered with the city. See the Long-Term Rental Registration page for current rules.
- Policy form: one to four units usually goes on a dwelling policy; five or more usually goes on a commercial habitational policy.
Census figures are survey estimates with margins of error. We use them to describe the housing stock, not any one building.
Portland’s rental stock, by building type
Two- to four-family houses and small walk-ups
Wood-frame two-, three- and four-families fill parts of Munjoy Hill, the West End, Parkside and Bayside. Many are more than a century old. Carriers want to know about the roof, the electrical service, the heating system, and whether plumbing has been updated. Stacked porches and exterior stairs come up often, because they’re a common source of injury claims. If you live in one unit, some carriers can write the building on an owner-occupied form. If you don’t, it goes on a landlord (dwelling) policy. Our Maine landlord insurance page covers one- to four-family rentals in detail.
Mid-size and mixed-use buildings (5 to 49 units)
Brick blocks, converted older commercial buildings and mid-size walk-ups make up much of the five-plus market on and around the peninsula. These buildings usually need a commercial habitational policy with building coverage, loss of rents, general liability and, often, equipment breakdown for boilers. A store, restaurant or office on the ground floor changes the risk, and we need to know about it up front.
Larger and waterfront buildings
Newer and larger buildings downtown and along the working waterfront often come with elevators, garages, amenity spaces and lender-driven insurance requirements. Tell us the size and the lender’s requirements early, and we’ll tell you honestly which of our markets fit.
Five or more units: what a habitational policy should include
A commercial apartment building policy is built from several parts. These are the ones we review on every Portland building:
- Building coverage at replacement cost. Insure what it would cost to rebuild, not what the building would sell for or its assessed value. Older masonry and ornate woodwork can cost more to replace than square-footage averages suggest.
- Building ordinance or law. After a large loss, the city can require the rebuilt portion (and sometimes the undamaged portion) to meet current code: fire separation, egress, electrical and accessibility. Standard building coverage doesn’t pay for most of that.
- Loss of rents. If a fire or a burst pipe empties the building, the mortgage, taxes and heat don’t stop. Check the limit and the time period against a real Portland rebuild, including winter.
- General liability. Icy walks, stairs, porches and common areas drive most claims. Check exclusions for assault and battery and for habitability-related claims.
- Equipment breakdown and water backup. Steam and hot-water boilers are common in older buildings. Sewer and drain backup usually needs its own endorsement.
- Umbrella. A commercial umbrella or excess policy sits over the liability limit. Many lenders expect one. See umbrella insurance in Maine.
Our Maine apartment building insurance guide explains the 2-4 vs. 5+ line statewide. This page focuses on what’s specific to Portland.
Portland rules and winter conditions that touch your insurance
Long-term rental registration
The city requires owners of long-term rental units to register with Portland. The Long-Term Rental Registration page lists the current rules, deadlines and fees. Registration itself isn’t an insurance requirement, but underwriters do ask about code compliance and how the building is managed. Open violations can make a building harder to place, and an inspection or registration record can help show that the systems are in order.
Winter: heat, ice dams, vacant units and frozen pipes
Portland’s heating season is long. A vacant unit, a failed boiler or a thermostat set too low can lead to frozen pipes and a water loss that takes several apartments out of service. Ice dams and heavy snow on older roofs are recurring risks. Tell us how the building is heated, whether units stay occupied year-round, and who responds after hours if the heat goes down.
Short-term and student or workforce turnover
Some Portland buildings mix year-round tenants with short-term or seasonal use, and some turn over with the student and hospital workforce. Carriers may ask about that occupancy. Be upfront about it; a policy that doesn’t match how the building is used can lead to a coverage dispute after a loss.
Flood and wind on the peninsula
Parts of Portland sit low along the harbor, the working waterfront and Back Cove. A standard apartment building policy doesn’t cover flood. If the building has a federally backed mortgage and sits in a FEMA high-risk zone, the lender will require flood coverage. Even outside those zones, coastal storms and nor’easters can push water into low-lying streets and basements.
We write new NFIP flood policies through Selective and can compare private flood options, which can matter for larger buildings where NFIP building limits may fall short of replacement cost. See flood insurance in Maine and coastal home insurance in Maine. Check your building on the FEMA Flood Map Service Center before you renew.
Why owners compare with an independent agency
Habitational underwriting changes from year to year, and one carrier’s appetite for a 1910 West End block can be very different from another’s. As an independent agency, we can put Vermont Mutual, Concord Group, Safety, Andover and Providence Mutual side by side on a five-plus building, and compare a wider group on one- to four-family rentals. We’ll explain the differences in deductibles, ordinance or law, loss of rents and liability exclusions before you decide. See how we choose carriers.
- Family-owned, licensed in 10 states, serving Maine from our Portsmouth, NH office
- 40+ carriers and no fees of any kind
- 1,000+ Google reviews and over 2,000 testimonials, and an A+ BBB rating
What to have ready for a quote
- Address, number of units, stories and square footage
- Year built and the years the roof, electrical, plumbing and heating were updated
- Construction (wood frame, joisted masonry, brick) and whether there are sprinklers or a monitored fire alarm
- Rent roll or total annual rents, and any vacant, furnished or short-term units
- Any commercial tenant on the ground floor
- Three to five years of loss history and your current declarations pages
- Your lender’s insurance requirements, if you have a mortgage
- City rental registration status
Get a quote for your Portland building
Send us the basics and a licensed agent will review your building and your current coverage, then compare the carriers that fit. There’s no obligation to buy, and we don’t charge any fees. Call (603) 431-4020, email insure@portsmouthatlanticins.com or start your quote online.
More for Maine owners: Maine insurance agency, southern Maine insurance agency, Maine landlord insurance, Maine condo association insurance and Cape Elizabeth high-value home insurance.
Where this fits: this page is part of our apartment building insurance hub, which sits under our landlord and apartment building insurance guide for New England.
Frequently asked questions
When does a Portland rental need a commercial apartment building policy?
Most carriers write one- to four-family rentals on a dwelling (landlord) policy and move five or more units to a commercial habitational policy. Mixed-use buildings with a shop on the ground floor, and owners with several smaller buildings, can also end up on a commercial form. We look at the building and your other properties before recommending a form.
Which carriers do you use for Portland apartment buildings?
For Maine apartment buildings and condo association master policies, we place coverage with Vermont Mutual, Concord Group, Safety, Andover Companies and Providence Mutual. Which one fits depends on the building’s age, construction, updates, location, occupancy and loss history.
Do I have to register a Portland rental with the city?
Yes, for long-term rental units. Portland requires owners to register long-term rentals with the city. See the city’s Long-Term Rental Registration page for current rules, deadlines and fees. Registration isn’t an insurance requirement, but open code issues and missing registrations can make a building harder to place.
Is loss of rents included on an apartment building policy?
Usually it’s available, but the limit and time period vary. Some policies cover a set number of months; others cover actual loss sustained for up to a year. In an older Portland building, winter, permits and contractor schedules can stretch a rebuild, so the time limit matters as much as the dollar amount.
Do I need flood insurance for a building on the peninsula or the waterfront?
A standard apartment building policy doesn’t cover flood. If the building is in a FEMA high-risk zone and has a federally backed mortgage, your lender will require it. Even outside those zones, low-lying parts of the peninsula, the working waterfront and areas around Back Cove can flood. Check the FEMA Flood Map Service Center, then ask us to compare NFIP and private flood options.
Do you have a Maine office, and do you charge fees?
We don’t have a Maine office, and we don’t charge any fees. We serve Portland owners from our office at 601 Islington St, Unit 206, in Portsmouth, NH, about an hour down the Maine Turnpike, by phone, email and online. Call (603) 431-4020 or start a quote.
Sources
- U.S. Census Bureau, American Community Survey 2024 1-year estimates: tables B25003 (tenure), B25024 (units in structure) and B25034 (year built), Portland city.
- City of Portland, Permitting & Inspections: Long-Term Rental Registration.
- FEMA Flood Map Service Center.