
By Jon Merwin, Founder and CEO, Licensed Insurance Advisor
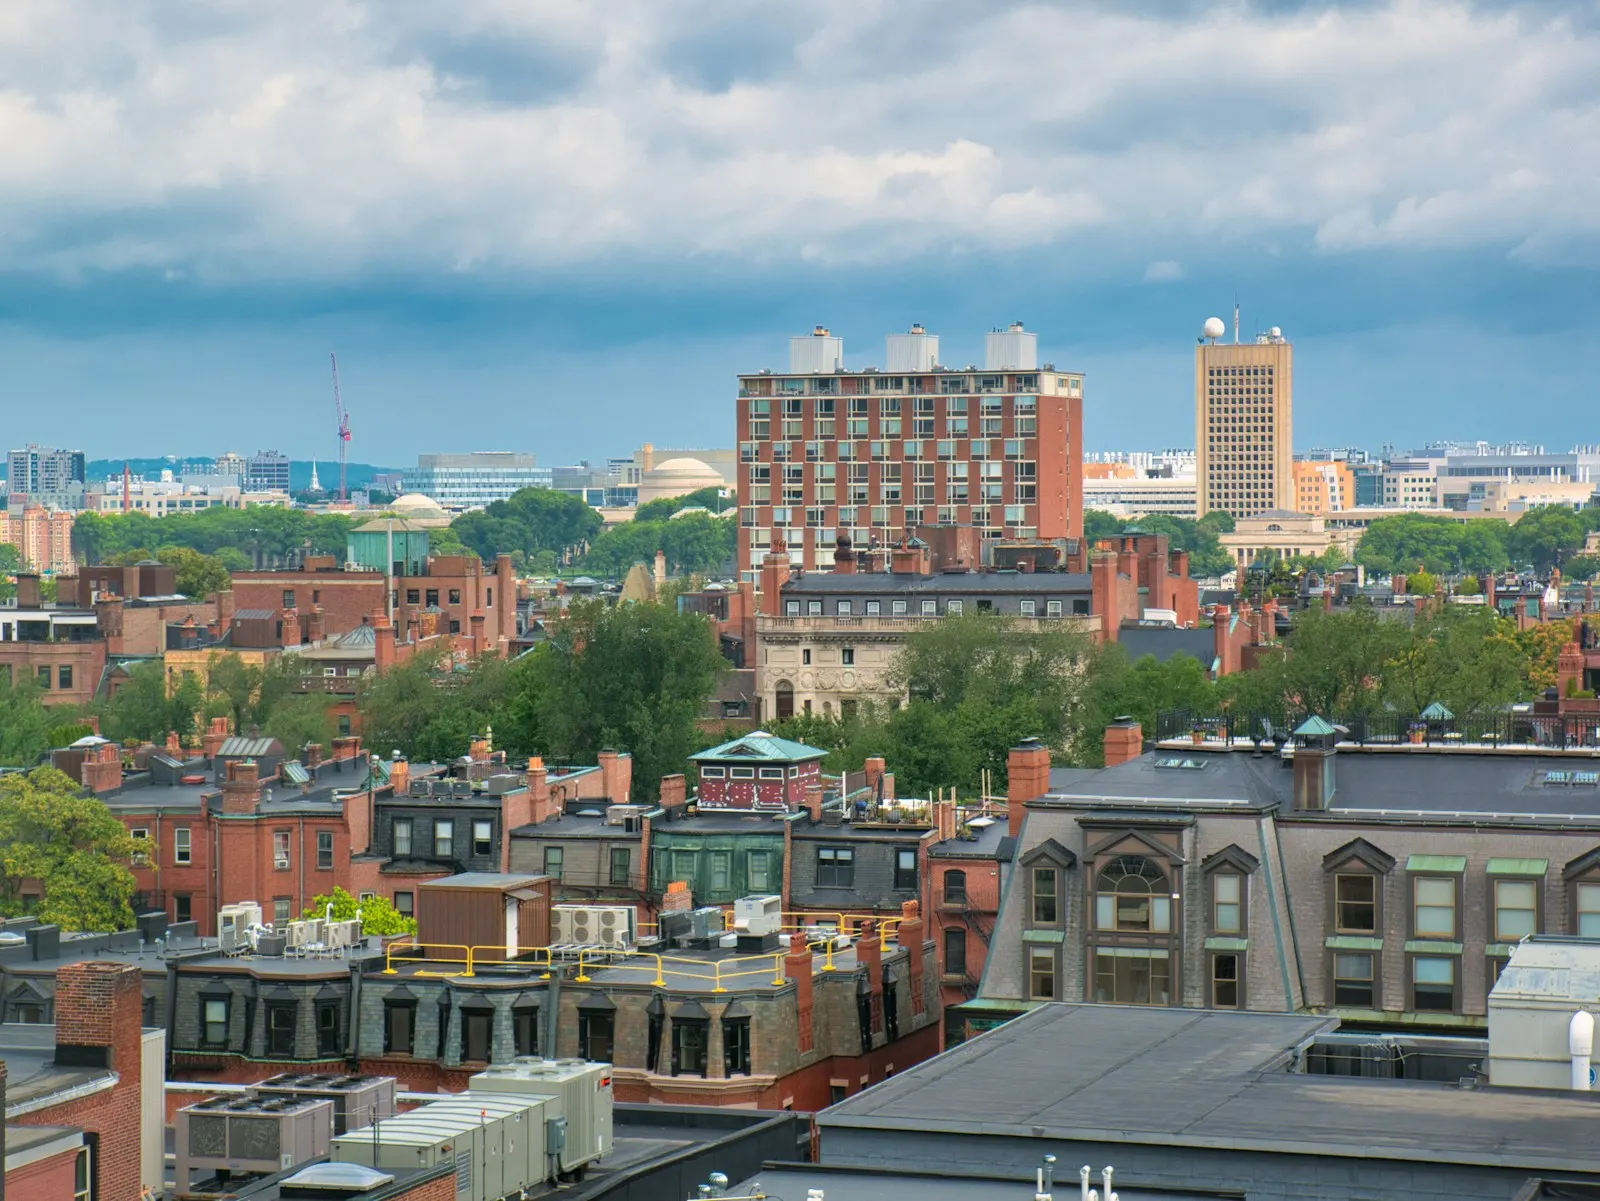
Lynn’s rental housing is older, denser and closer to the water than most of the North Shore. About 56% of occupied homes are rented, about half of the city’s housing units were built before 1940, and about 35% of units are in two- to four-unit buildings (U.S. Census Bureau, American Community Survey 2024 1-year estimates). Triple-deckers, brick walk-ups and mixed-use blocks, some of them near Lynn Harbor, raise lead, wind, flood and registry questions that a generic apartment policy won’t sort out on its own.
Portsmouth Atlantic Insurance is a family-owned independent agency licensed in Massachusetts. We compare 40+ carriers, and for Massachusetts apartment buildings we place coverage with Vermont Mutual, Concord Group, Safety, Andover Companies and Providence Mutual. We don’t have a Massachusetts office; Lynn owners work with us from our Portsmouth, NH office by phone, email and online. We don’t charge any fees. Call (603) 431-4020 or start a quote.
Key facts for Lynn apartment owners
- Renter share: about 56.5% of occupied homes in Lynn are renter-occupied (ACS 2024 1-year).
- Age: about 50.4% of the city’s housing units were built in 1939 or earlier.
- Building size: about 35% of units are in two- to four-unit buildings, and about 31% are in buildings with five or more units.
- Registration: Lynn requires annual registration of private rental units and an inspection every five years (Lynn Rental Ordinance).
- Policy form: one to four units usually goes on a dwelling policy; five or more usually goes on a commercial habitational policy.
Census figures are survey estimates with margins of error. We use them to describe the housing stock, not any one building.
Lynn’s rental stock, by building type
Triple-deckers and two- to four-family houses
Wood-frame two-, three- and four-families, including North Shore triple-deckers, make up a large share of Lynn’s rentals. Many are more than a century old. Carriers want to know about the roof, electrical service, heating, plumbing updates, and stacked porches. If you live in one unit, some carriers can write the building on an owner-occupied form. If you don’t, it goes on a landlord (dwelling) policy. Our Massachusetts landlord insurance page covers these 1-4 unit buildings in detail.
Walk-ups and mid-size buildings (5 to 49 units)
Brick and masonry walk-ups and mid-size apartment buildings usually need a commercial habitational policy with building coverage, loss of rents, general liability and, often, equipment breakdown. The age of the systems, how close the building sits to the water, and how it’s managed usually decide which carrier is the best fit.
Coastal and harbor-adjacent buildings
Buildings closer to Lynn Harbor and the shoreline pick up wind and flood questions that inland blocks don’t. Tell us the address early so we can look at FEMA maps, any wind deductible, and whether a lender will require flood coverage.
Five or more units: what a habitational policy should include
- Building coverage at replacement cost. Insure what it would cost to rebuild, not sale price or assessed value.
- Building ordinance or law. After a large loss, current fire-separation, egress, electrical and accessibility rules can apply to the rebuilt portion and sometimes to undamaged parts of the building.
- Loss of rents. Permits, lead work and contractor schedules can stretch a rebuild. Check the time period as well as the dollar limit.
- General liability. Icy walks, stairs, porches and common areas drive most claims. Check how the policy treats lead, assault and battery, and habitability-related claims.
- Equipment breakdown and water backup. Boilers and older plumbing are common. Sewer and drain backup usually needs its own endorsement.
- Umbrella. A commercial umbrella or excess policy sits over the liability limit. See umbrella insurance in Massachusetts.
Our Massachusetts apartment building insurance guide explains the 2-4 vs. 5+ line statewide. This page focuses on Lynn and the North Shore coast.
Lynn and Massachusetts rules that touch your insurance
Annual rental registration and five-year inspections
Lynn’s Rental Ordinance requires owners of private residential rental housing units, including condominium units, to register each year with Inspectional Services and to have the property inspected every five years. See the city’s page for current applications, inspection checklists and fees. Registration isn’t an insurance requirement, but open violations can make a building harder to place, and a current inspection report can help show a carrier that the systems are in order.
The lead law and lead liability coverage
Under M.G.L. c. 111, § 197, when a child under six lives in a pre-1978 unit, the owner must have lead hazards abated or brought under interim control. The insurance side is set by M.G.L. c. 175, § 111H: a liability policy that covers an owner whose property has a Letter of Interim Control or a Letter of Full Compliance must cover claims for lead injury, except gross or willful negligence. If the property isn’t in compliance, a carrier that chooses to write it must make lead liability coverage available. Have your lead letters on hand when you ask for a quote.
State Sanitary Code
The State Sanitary Code, 105 CMR 410.000, sets minimum standards for heat, water, pests, mold and moisture, and safe conditions in rental housing. After a fire or water loss, units can’t be re-rented until they meet these standards.
Wind and flood on the North Shore
Lynn sits on the coast. Parts of the city along the harbor and the shoreline are in or near FEMA high-risk flood zones, and coastal storms can bring both storm surge and high wind. A standard apartment building policy doesn’t cover flood. If the building has a federally backed mortgage and sits in a high-risk zone, the lender will require flood coverage. Wind deductibles, when they apply, are worth reviewing at every renewal.
We write new NFIP flood policies through Selective and can compare private flood options, which can matter for larger buildings where NFIP building limits may fall short of replacement cost. See flood insurance in Massachusetts and North Shore home insurance. Check your building on the FEMA Flood Map Service Center before you renew.
Why owners compare with an independent agency
Habitational underwriting changes from year to year, and one carrier’s appetite for a coastal triple-decker can be very different from another’s. As an independent agency, we can put Vermont Mutual, Concord Group, Safety, Andover and Providence Mutual side by side on a five-plus building, and compare a wider group on one- to four-family rentals. See how we choose carriers.
- Family-owned, licensed in 10 states, serving Massachusetts from our Portsmouth, NH office
- 40+ carriers and no fees of any kind
- 1,000+ Google reviews and over 2,000 testimonials, and an A+ BBB rating
What to have ready for a quote
- Address, number of units, stories and square footage
- Year built and the years the roof, electrical, plumbing and heating were updated
- Construction and whether there are sprinklers or a monitored fire alarm
- Rent roll or total annual rents, and any vacant or furnished units
- Any commercial tenant on the ground floor
- Lead letters and Lynn rental registration and inspection status
- Three to five years of loss history and your current declarations pages
- Your lender’s insurance requirements, if you have a mortgage
Get a quote for your Lynn building
Send us the basics and a licensed agent will review your building and your current coverage, then compare the carriers that fit. There’s no obligation to buy, and we don’t charge any fees. Call (603) 431-4020, email insure@portsmouthatlanticins.com or start your quote online.
More for North Shore owners: Lynn insurance agency, Salem insurance agency, condo association insurance in Salem, Peabody insurance agency and Massachusetts condo association insurance.
Where this fits: this page is part of our apartment building insurance hub, which sits under our landlord and apartment building insurance guide for New England.
Frequently asked questions
When does a Lynn rental need a commercial apartment building policy?
Most carriers write one- to four-family rentals, including many triple-deckers, on a dwelling (landlord) policy and move five or more units to a commercial habitational policy. Mixed-use buildings with a store on the ground floor can also land on a commercial form. We look at the building before recommending a form.
Which carriers do you use for Lynn apartment buildings?
For Massachusetts apartment buildings and condo association master policies, we place coverage with Vermont Mutual, Concord Group, Safety, Andover Companies and Providence Mutual. Which one fits depends on the building’s age, construction, updates, location, occupancy and loss history.
Does Lynn require rental registration?
Yes. The city’s Lynn Rental Ordinance requires owners of private residential rental housing units, including condominium units, to register each year and to have the property inspected every five years through Inspectional Services. See the city’s page for current applications and fees.
Does my liability policy cover lead paint claims?
It depends on the building’s lead status. Under M.G.L. c. 175, § 111H, a liability policy covering a pre-1978 property with a Letter of Interim Control or Letter of Full Compliance must cover lead injury claims, except gross or willful negligence. If the property isn’t in compliance, a carrier that writes it must make lead liability coverage available. Have your lead letters ready when you ask for a quote.
Do I need flood or special wind coverage near Lynn Harbor?
A standard apartment building policy doesn’t cover flood. Parts of Lynn along the harbor and the shoreline sit in or near FEMA flood zones, and coastal storms bring both surge and wind. If the building has a federally backed mortgage and is in a high-risk flood zone, the lender will require flood coverage. Check the FEMA Flood Map Service Center, then ask us to compare NFIP and private flood options and to review any wind deductible.
Do you have a Massachusetts office, and do you charge fees?
We don’t have a Massachusetts office, and we don’t charge any fees. We serve Lynn owners from our Portsmouth, NH office by phone, email and online, and a licensed agent reviews every policy. Call (603) 431-4020 or start a quote.
Sources
- U.S. Census Bureau, American Community Survey 2024 1-year estimates: tables B25003, B25024 and B25034, Lynn city.
- City of Lynn, Inspectional Services: Rental Ordinance (annual registration and five-year inspections; official page fetched Nov 15 2026).
- M.G.L. c. 111, § 197; M.G.L. c. 175, § 111H; Massachusetts Department of Public Health, 105 CMR 410.000.
- FEMA Flood Map Service Center.