
By Jon Merwin, Founder and CEO
Homeowners · Auto · Umbrella · Flood · Statewide in New Hampshire
- We start a New Hampshire bundle with the house, because the homeowners policy usually decides which carrier makes sense for the whole package.
- As an independent agency we compare home and auto together across 40+ carriers, instead of offering one company’s bundle.
- New Hampshire doesn’t require auto insurance, but the state’s financial responsibility rules still apply after a crash. We recommend it for every homeowner.
- Flood is never part of a home and auto bundle. Seacoast and riverfront owners need a separate flood policy.
- We serve every New Hampshire town from our Portsmouth office, by phone, email and online, and we charge no fees on any policy.
Portsmouth Atlantic Insurance is an independent agency founded in 2005 and licensed in 10 states. We are the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews and over 2,000 testimonials, and we bundle home and auto for families in every part of the state, from the Seacoast to the Lakes Region and the North Country. We compare 40+ carriers and charge no fees. Call (603) 431-4020 or request a quote online.
Why we start with the homeowners policy
Most people think of a bundle as a car policy with a house added on. We do it the other way around. The home is usually the bigger risk and the harder policy to place, so we find the right homeowners coverage first, then see which of those carriers also writes a strong auto policy for your household.
- Rebuild cost comes first. We set the dwelling limit on what it would cost to rebuild your house today, not its sale price or assessed value.
- The house shapes the carrier list. Roof age, heating system, a wood stove, a finished basement, distance to the coast and the age of the home all affect which carriers want it.
- Then the cars. Once we know which carriers fit the home, we quote auto with those same carriers so the bundle credit is real and the coverage still fits your drivers.
- Liability limits that match. We line up the liability on the home and the auto so an umbrella can sit on top of both without a gap.
Read more on our New Hampshire homeowners insurance page.
How an independent agency compares bundles
A captive agent can only offer one company’s bundle. We work with 40+ carriers, so we can compare several bundles side by side, and we can also tell you when splitting home and auto between two carriers works out better than bundling. That happens, and we would rather show you than hide it.
- You tell us about the house, the drivers and the cars. Your current declarations pages for home and auto help us compare like for like.
- We shop the carriers that fit your home and quote auto with each of them.
- We lay the options out together: coverage, deductibles, liability limits and any wind or water terms, along with the multi-policy credit, so you can see what you’re actually getting.
- You pick, and we handle the switch, including your mortgage company, the effective dates and the cancellation of your old policies, so nothing lapses.
For most New Hampshire homes, those valued under $2 million, almost all of our carriers are a fit, so there is real competition for your bundle. For homes over $3 million, we also look at carriers like Cincinnati and Chubb, which are built for larger homes, broader coverage and higher liability limits. See high-value home insurance in New Hampshire.
What’s different about bundling in New Hampshire
Auto insurance isn’t required, but financial responsibility is
New Hampshire is the one state that doesn’t require most drivers to carry auto insurance. That doesn’t mean you’re off the hook. Under the state’s financial responsibility law, if you cause a crash you still have to be able to pay for the damage and injuries, and the NH Division of Motor Vehicles can suspend an uninsured at-fault driver’s license and registration. After certain convictions or crashes, the DMV can also require you to carry insurance and file an SR-22.
If you do buy a policy, New Hampshire law sets minimum liability of 25/50/25 and requires medical payments coverage and uninsured motorist coverage equal to your liability limits (RSA 264:15). Those minimums are low for anyone who owns a home. A serious crash can easily run past them, and your house and savings are what a claim would come after. That is why we usually recommend higher auto liability as part of a home and auto bundle. See our auto insurance page.
Umbrellas and uninsured motorist coverage
New Hampshire has an unusual rule for umbrella policies: they must include uninsured motorist coverage up to the umbrella limit unless you reject it in writing. If someone without enough insurance hurts you, that extra layer can matter. Most umbrella carriers require certain liability limits on both your home and auto, which is one more reason to set them up together. Learn more about a personal umbrella policy.
Coastal and flood risk on the Seacoast
In Portsmouth, Rye, New Castle, Hampton and the other Seacoast towns, Nor’easters that line up with a high tide can push seawater into streets, yards and basements. Storm surge and rising water are flood, and homeowners policies exclude flood, so a home and auto bundle won’t cover it. We write NFIP flood through Selective and compare private flood options, and new NFIP policies generally have a 30-day waiting period (see FloodSmart). Inland, rivers and ponds can flood too. Check your address on the FEMA Flood Map Service Center and see our flood insurance page.
Many coastal homeowners policies also carry a separate wind or named-storm deductible, often a percentage of the dwelling limit. We show it to you in dollars before you buy.
Winter claims: ice dams, frozen pipes and fallen trees
A lot of New Hampshire homeowners claims happen between December and March. Ice dams back water up under shingles and into ceilings and walls. Pipes freeze and burst when the heat fails or a house sits empty. Heavy, wet snow brings down limbs and power lines. Sudden water damage from an ice dam or a burst pipe is generally a homeowners claim, subject to your deductible and policy terms, but carriers treat long vacancies, worn roofs and ongoing leaks differently. If a house will sit empty for part of the winter, tell us before you leave.
Winter matters for the auto side too. Icy roads mean more fender benders and more comprehensive claims from falling ice and branches. When we compare bundles, we look at the auto deductibles alongside the home deductible so one bad week in February doesn’t hit you twice.
What a New Hampshire home and auto bundle usually includes
- Homeowners (or condo, if you own a unit): the house, other structures, your belongings, loss of use and personal liability.
- Auto for every car and driver in the household, with liability limits that match the home.
- Optional add-ons such as water backup, scheduled jewelry or valuables, and equipment breakdown.
- A personal umbrella on top of both, if your carrier and limits allow it.
- Flood, quoted separately if you are near the coast, a river, a pond or a mapped flood zone.
Bundles often work for second homes too. Many New Hampshire families have a lake house or a ski place, and some carriers will put more than one home and the cars on the same account.
Own a home in New Hampshire? We’ll compare home and auto bundles across our carriers and walk you through the options in plain English. No fees. Call (603) 431-4020.
What our clients say
From our client surveys. Comments are lightly edited for typos only.
Jon is super helpful and amazingly communicative. He responds fast with well thought out answers making the process of getting insurance for my home and car super simple.
Very informative, responsive, and helpful with answering any questions we had. Helped us get the best deal and coverage, explained the differences between coverage options, and let us choose what worked best for us. Highly recommend!
Excellent guidance on insurance options and fantastic quoting and onboarding experience. We trust their recommendations and feel that we have best coverage for peace of mind at best possible cost.
Where we work in New Hampshire
Our office is in Portsmouth; see our Portsmouth, NH insurance agency page for the address and hours. We insure homes and cars in every county and town in the state by phone, email and online. Find your town on our New Hampshire insurance agency page.
Frequently asked questions
Can an independent agent bundle home and auto insurance in New Hampshire?
Yes. Portsmouth Atlantic Insurance is an independent agency, and we compare home and auto bundles from 40+ carriers for homeowners anywhere in New Hampshire. Call (603) 431-4020.
Is a home and auto bundle always cheaper?
Not always. Most carriers give a multi-policy credit, but sometimes one company has the best home policy and another has the best auto policy. Because we compare many carriers, we can show you both options and let you decide.
Do I need auto insurance in New Hampshire?
New Hampshire doesn’t require most drivers to carry auto insurance, but you must meet the state’s financial responsibility rules if you cause a crash, and the DMV can require insurance after certain violations or accidents. If you own a home, we recommend auto liability well above the state minimums.
Does a home and auto bundle cover flood?
No. Homeowners policies exclude flood, including storm surge on the Seacoast. Flood is a separate NFIP or private flood policy, and new NFIP policies generally have a 30-day waiting period.
Are ice dam leaks covered by homeowners insurance?
Sudden water damage from an ice dam is generally covered, subject to your deductible and policy terms. Damage from long-term leaks, wear or a lack of maintenance usually isn’t. We can walk you through how your carrier handles it.
Which carriers do you use for a bundle?
We work with 40+ carriers. For homes under $2 million, almost all of them are a fit. For homes over $3 million, we also look at carriers like Cincinnati and Chubb.
Do you charge fees?
No. We don’t charge fees on any policy we write, personal or business.
Sources
- NH Division of Motor Vehicles, Accident Records FAQs
- NH Division of Motor Vehicles, Insurance Requirements / SR-22
- NH RSA 264:20, Amount of Proof of Financial Responsibility
- NH RSA 264:15, Uninsured or Hit-and-Run Motor Vehicle Coverage
- FloodSmart, buying a flood policy
- FEMA Flood Map Service Center
Get a New Hampshire home and auto quote
Send us your current declarations pages, or just tell us about your house and cars, and we’ll compare bundles and follow up with options, including flood if you need it. Start your quote or call (603) 431-4020.
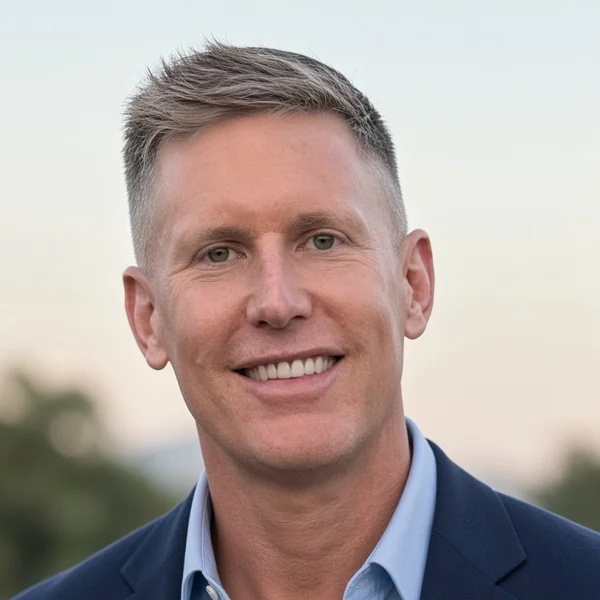
By Jon Merwin, Founder and CEO
Jon founded Portsmouth Atlantic Insurance in 2005. We are an independent agency licensed in 10 states, we compare coverage from 40+ carriers, and we are the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews and over 2,000 testimonials. Meet our team.