
By Jon Merwin, Founder and CEO
- The number of carriers an agency works with decides how many real options you’ll see.
- Read reviews for how people describe service and claims, not just the star rating.
- Check that the agency and its agents are licensed in New Hampshire.
- Local knowledge matters here: flood on the Seacoast, winter claims statewide and the state’s auto insurance rules.
- Ask who will answer the phone after the sale, and whether the agency charges any fees.
Independent agencies don’t work for one insurance company. They work with many and shop your coverage across them. That’s the main advantage, but agencies vary a lot in how many carriers they actually use, how they treat clients after the sale and how well they know New Hampshire. Here is the checklist I’d use if I were picking an agency for my own family.
If you want the short version of how independent and captive agents differ, read independent vs captive insurance agents.
The checklist
1. How many carriers do they work with?
An agency with three or four carriers can only show you three or four answers. One with dozens can usually find a carrier that wants your house, your cars and your driving record, and can move you if a carrier raises rates or stops writing in your area. Ask how many carriers the agency uses for homeowners and auto in New Hampshire specifically, and whether they include carriers for larger homes, older homes and coastal homes.
- Ask: “How many carriers will you actually quote for me?”
- Ask: “If my renewal goes up next year, will you re-shop it?”
2. What do their reviews say?
Look at reviews on Google and on the agency’s own site, and read the words, not just the stars. You want people describing quick answers, clear explanations and help during a claim. A handful of reviews tells you little. A large number collected over many years tells you how the agency treats people day to day. Watch for agencies that only show a few hand-picked quotes.
3. Are they licensed in New Hampshire?
Every agency and agent selling insurance in New Hampshire must hold a New Hampshire license from the New Hampshire Insurance Department. You can look up a producer’s license through NIPR. If you have homes or cars in more than one state, such as a lake house in New Hampshire and a home in Massachusetts, ask whether the agency is licensed in those states too so one team can handle everything.
4. Do they know New Hampshire?
Insurance here has its own quirks. A good agency should be able to talk you through these without looking them up:
- Auto rules. New Hampshire doesn’t require most drivers to buy auto insurance, but its financial responsibility law still applies after a crash, and policies that are bought must include uninsured motorist and medical payments coverage.
- Flood. Seacoast storm surge and inland river and pond flooding are excluded from homeowners policies and need a separate flood policy.
- Winter. Ice dams, frozen pipes and snow load are some of the most common home claims in the state.
- Older homes. Historic houses in towns like Portsmouth, Exeter and Concord can cost more to rebuild than they would sell for.
- Umbrellas. New Hampshire umbrella policies include uninsured motorist coverage unless you reject it in writing.
5. Who will help you after the sale?
The quote is the easy part. Ask who handles changes, certificates for your mortgage company, new drivers and claims. Is there a service team, or one person who may be on vacation when your basement floods? Can you reach them by phone and email? Do they review your policies at renewal, or only when you call?
6. Do they charge fees?
Some agencies add broker or policy fees on top of the premium. Ask directly, and ask about every line of coverage, home, auto, umbrella, flood and business, not just one. You should know before you sign whether anything is added to what the carrier charges.
Questions to ask on the first call
- How many carriers will you quote for my home and auto?
- Will you compare a bundle with splitting home and auto between carriers?
- Do you write flood, and do you compare NFIP and private flood?
- Who do I call if I have a claim, and what do you do to help?
- Will you re-shop my policies at renewal?
- Are you licensed in New Hampshire and in any other states where I own property?
- Do you charge any fees on any policy?
How Portsmouth Atlantic Insurance answers that checklist
Since you’re reading this on our site, here are our answers. We’re an independent agency founded in 2005, with our office in Portsmouth. We compare 40+ carriers. We’re licensed in 10 states. We’re the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews and over 2,000 testimonials, which you can read on our client testimonials page. Our service team handles changes and claims help after the sale, and we charge no fees on any policy, personal or business.
If you’re comparing agencies for a home and auto bundle, see bundling home and auto insurance in New Hampshire. You can also read our New Hampshire homeowners insurance page, our auto insurance page, our Portsmouth office page, or find your town on our New Hampshire insurance agency page.
What our clients say
From our client surveys. Comments are lightly edited for typos only.
Jon is super helpful and amazingly communicative. He responds fast with well thought out answers making the process of getting insurance for my home and car super simple.
Very informative, responsive, and helpful with answering any questions we had. Helped us get the best deal and coverage, explained the differences between coverage options, and let us choose what worked best for us. Highly recommend!
Excellent guidance on insurance options and fantastic quoting and onboarding experience. We trust their recommendations and feel that we have best coverage for peace of mind at best possible cost.
Want to see how we compare? Send us your current policies and we’ll shop them across our carriers. No fees. Call (603) 431-4020.
Frequently asked questions
What is an independent insurance agency?
An independent agency is licensed to sell policies from many insurance companies rather than just one. It compares carriers for you and can move your coverage if another carrier is a better fit.
How many carriers should an independent agency have?
There is no set number, but more carriers mean more real options, especially for older homes, coastal homes and larger homes. Ask how many carriers the agency will actually quote for you.
How do I check if an insurance agent is licensed in New Hampshire?
Insurance producers in New Hampshire are licensed by the New Hampshire Insurance Department. You can look up a license through NIPR.
Should an insurance agency charge fees?
Some do. Ask before you sign, and ask about every line of coverage. Portsmouth Atlantic Insurance doesn’t charge fees on any policy, personal or business.
Does it matter if the agency is local?
It helps. An agency that knows New Hampshire understands Seacoast flood, winter claims, older homes and the state’s auto insurance rules, and can still serve you by phone and email anywhere in the state.
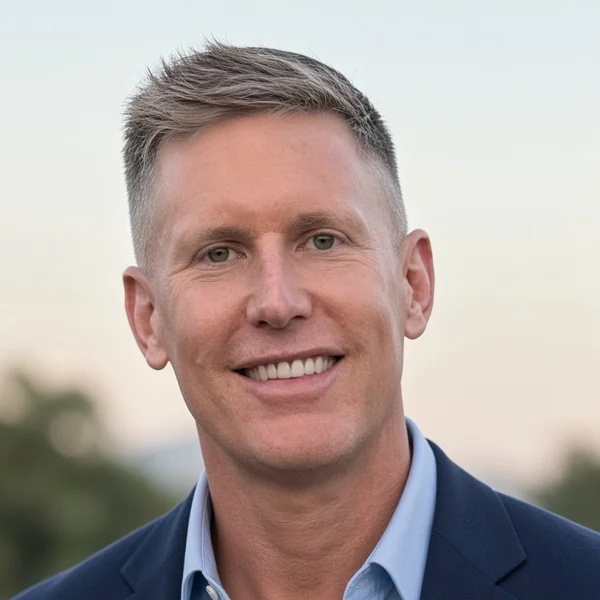
By Jon Merwin, Founder and CEO
Jon founded Portsmouth Atlantic Insurance in 2005. We are an independent agency licensed in 10 states, we compare coverage from 40+ carriers, and we are the most-reviewed independent insurance agency in New Hampshire, with 1,000+ Google reviews and over 2,000 testimonials. Meet our team.