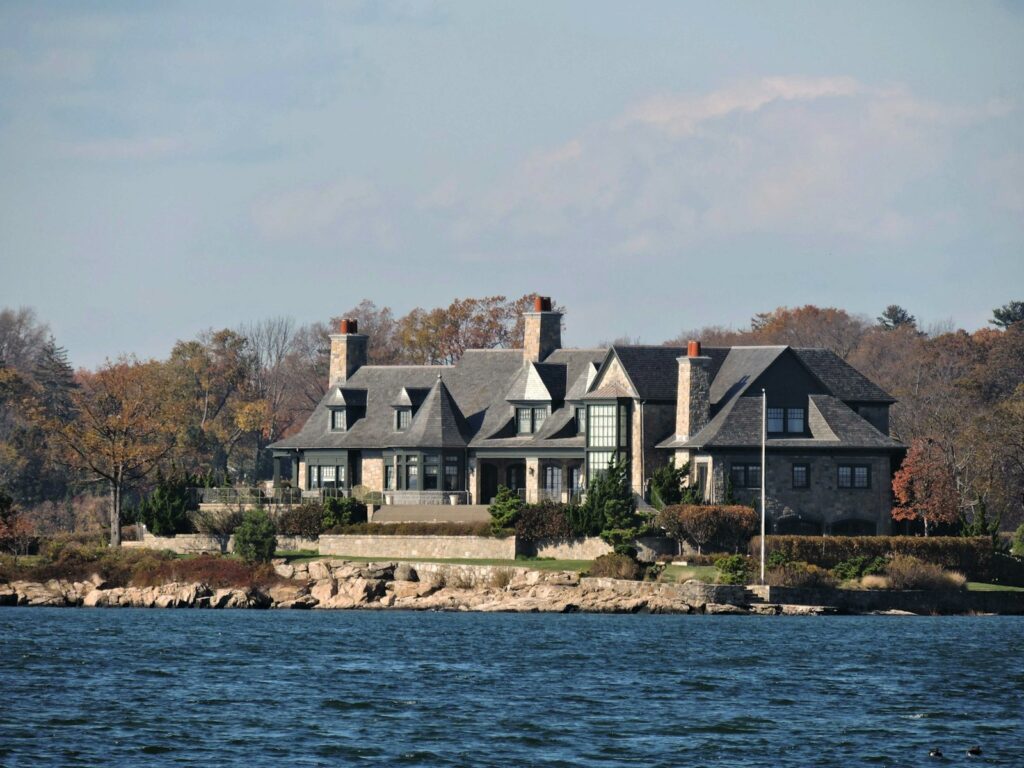
The Fairfield County shoreline has some of the most valuable homes in New England, and some of the most exposed. A colonial in Lordship a block from Long Island Sound, a renovated home near Fairfield’s beaches, a property on the water in Westport or a larger estate in the Greenwich area all need more than a standard homeowners policy. Portsmouth Atlantic Insurance has an office in Stratford, and we help shoreline homeowners compare high-value home carriers including Chubb, Cincinnati, Hanover, Openly, National General and Andover, all of which write in Connecticut.
We’ve been an independent agency since 2005, we’re licensed in 10 states, we work with 30+ carriers, and we have over 2,000 client testimonials.
Insuring Homes Along the Fairfield County Shoreline
Shoreline homes in Stratford, Fairfield and Westport share a few challenges. Many are older homes that have been expanded and renovated, so the cost to rebuild is higher than the purchase price suggests. Neighborhoods near Stratford Point, the Housatonic River, Fairfield Beach and Westport’s harbor face wind and storm surge from Long Island Sound. And the contents inside, from art to wine to jewelry, often outgrow a standard policy’s limits long before anyone notices.
Connecticut Hurricane Deductibles Explained
Hurricane deductibles in Connecticut follow specific rules. The Connecticut Insurance Department explains that an insurer may apply a hurricane deductible instead of your regular deductible only when the National Hurricane Center has issued a hurricane warning for any part of the state and the hurricane brings maximum sustained winds of 74 miles per hour or more to any part of Connecticut. The deductible period ends 24 hours after the last hurricane warning for the state is lifted, or 24 hours after the storm is last downgraded from hurricane status, whichever comes first. These rules are set out in Connecticut General Statutes section 38a-316a.
The Department also explains that wind or hail deductibles are different, and insurers can’t mandate them in Connecticut. They can be a flat amount or a percentage of your dwelling limit. If your policy has a hurricane deductible, the percentage and the dollar amount will be shown on your declarations page. On a high-value home, a percentage deductible can be a large number, so we always walk through the dollar figure with you.
Flood Insurance for Stratford, Fairfield and Westport Homes
The Connecticut Insurance Department’s hurricane and tropical storm guidance is direct: flood damage isn’t covered under standard homeowners policies, flood insurance requires a separate policy, and storm surge is generally considered flood damage. FEMA’s NFIP caps residential building coverage at $250,000 and contents at $100,000, and according to FloodSmart, a new policy usually takes effect 30 days after purchase. Don’t wait for a storm in the forecast.
For larger shoreline homes, private flood insurance can provide higher limits and broader coverage. We work with private flood markets including Neptune Flood, Beyond Floods and The Flood Insurance Agency. Read more on our flood insurance page and our coastal home insurance in Connecticut page.
Replacement Cost and Rebuilding a Custom Home
- An accurate dwelling limit. Many high-value carriers appraise the home in person so the limit reflects the real cost to rebuild with like kind and quality materials.
- Extended or guaranteed replacement cost. Depending on the carrier and the home, coverage can stretch above the dwelling limit if rebuilding costs more than expected.
- Code upgrades. Rebuilding along the shoreline can come with elevation and building code requirements, and the right coverage helps pay for them.
- Cash settlement options. Some high-value policies let you take a settlement instead of rebuilding after a total loss.
- Water backup. Backup through sewers and drains is usually excluded unless you add it, which matters for finished basements and wine storage.
Art, Jewelry, Wine and Collections
Standard homeowners policies cap coverage for jewelry, watches, silver and similar items, especially for theft. Scheduling them on their own, usually with an appraisal, gives each piece dedicated coverage. We help Fairfield County clients schedule art, antiques, wine, jewelry and other collections and keep the values current.
Umbrella Liability and Multiple Properties
A shoreline home with a pool, a dock, frequent guests or household staff carries real liability exposure. A personal umbrella adds a layer of protection over your home and auto policies; see our umbrella insurance page. If you also own a second home, perhaps on the New Hampshire Seacoast or elsewhere in New England, our licenses in 10 states let us coordinate the properties and keep them under one umbrella. Our high net worth insurance page covers the bigger picture.
For standard coverage, see our homeowners insurance page, or visit our Stratford, CT insurance agency page. Our Stratford office is at 160 1st Ave, Stratford, CT 06615.
Reviewed by Jon Merwin, owner of Portsmouth Atlantic Insurance. Last reviewed October 2026.
Insuring a home elsewhere in the state? Our guide to high-value home insurance in Connecticut covers the same questions for homes across Connecticut.
Talk to Us About Your Shoreline Home
Every household is different, so the best next step is a conversation. Call us at (603) 431-4020, email insure@portsmouthatlanticins.com, or start your high-value home insurance quote online. We’ll compare your options and explain them in plain English.
High-Value Home Insurance FAQs for Stratford, CT
When does a hurricane deductible apply in Connecticut?
Only during the period that starts when the National Hurricane Center issues a hurricane warning for any part of Connecticut and the hurricane brings sustained winds of 74 mph or more to any part of the state. It ends 24 hours after the last warning is lifted or the storm is last downgraded, whichever comes first.
Is a hurricane deductible a percentage of the damage?
Usually it’s a percentage of your dwelling limit, not of the damage. Your declarations page will show both the percentage and the dollar amount.
Does homeowners insurance cover storm surge in Stratford or Fairfield?
No. The Connecticut Insurance Department says storm surge is generally considered flood damage, and flood requires a separate policy.
How much flood coverage is available for a high-value home?
The NFIP generally caps residential building coverage at $250,000 and contents at $100,000. Private flood insurance can offer higher limits for larger shoreline homes.
Do I need to schedule art, jewelry and wine?
Usually, yes. Standard policies have low limits on items like jewelry and watches, especially for theft. Scheduling them, usually with an appraisal, gives each item its own coverage.
Which high-value home carriers do you work with in Connecticut?
We work with Chubb, Cincinnati, Hanover, Openly, National General and Andover, along with 30+ carriers overall, and compare them for your home.