
Even if there isn’t a leak right now, homeowners insurance cancellations due to roof problems typically indicate that the insurer views your roof as a potential risk. The decision is typically made based on factors like age, obvious wear, or inspection results that indicate a higher likelihood of claims.
For instance, an inspection may identify uneven wear or previous repairs as indicators that the roof may soon fail, even though a homeowner with a 20-year-old roof and a few patched areas may still have no leaks. From the insurer’s perspective, that risk often outweighs keeping the policy in place.
- If a roof is likely to cause future claims, the insurance is canceled.
- It’s not just about age; the condition and repair history are just as important.
- You usually have a short time to act before coverage ends.
- What happens next depends on whether the item needs to be fixed or replaced completely.
- Acting quickly can help you avoid gaps in coverage and problems with lenders.
This situation may seem sudden, but it follows a pattern that is easy to see. Knowing how insurance companies look at roofs, what your notice really means, and how to respond can help you make smart, steady choices instead of hasty ones.
Before you make any decisions about repairs or replacement, it helps to understand exactly how insurers are evaluating your roof right now.
If you’re unsure whether your situation requires a repair or full replacement, you can request a quick coverage review to get clarity before spending anything.
Can Homeowners Insurance Be Cancelled Because of Roof Issues?
Yes, roof problems can cause homeowners insurance to be canceled. The decision is usually based on how the insurer sees future risk, not just how well the current policy is working.
You don’t have to see or hear a roof leaking or failing for a policy to be canceled. It just needs to show signs that make it more likely that claims will be made in the future.
A roof with old shingles, past repairs, or uneven wear, for instance, may still be working. From a homeowner’s perspective, nothing appears urgent. From an insurer’s perspective, those same signs point to a predictable failure window.
This difference in perspective is where most confusion begins. If you’re trying to understand how insurers evaluate roof-related claims in the first place, it helps to look at what homeowners insurance actually covers when it comes to roof leaks.
What a Roof-Related Cancellation Means
A homeowners insurance cancelled because of roof issues is rarely about a single defect. It usually reflects the insurer’s view that your roof presents a predictable future claim risk, even if no damage has occurred yet.
For instance, a roof with old shingles, a little bit of granule loss, and patches from the past may still keep water out. But to an insurance company, those signs mean that the business is more likely to fail in the next few years. When making insurance decisions, it’s not just about the current state of things; it’s also about the chances of something happening.
Insurers act before failure because claims are most expensive when damage spreads beyond the roof. Water intrusion can affect structure, wiring, and interiors. Preventing that exposure is central to underwriting.
At Portsmouth Atlantic Insurance, we often see homeowners surprised by this shift in perspective. The roof doesn’t need to be failing. It only needs to appear likely to fail.
- Insurers focus on future risk, not present damage
- Small issues can signal larger underlying concerns
- Past repairs can suggest recurring problems
- Inspections are designed to detect patterns, not just defects
Many homeowners only recognize these risks after a policy change. A second look at your coverage can often bring clarity.
Many homeowners rush into repairs at this stage, assuming that fixing visible issues will restore coverage.
In reality, insurers are evaluating risk patterns, not just damage.
If you want to understand how your specific roof would be viewed by an insurer today, a second-look coverage assessment can help you avoid unnecessary repairs that don’t actually solve the problem.
Cancellation vs Non-Renewal (Simple Explanation)
It’s important to know that cancellation and non-renewal are not the same thing. The difference affects how quickly you need to act. When you cancel your policy, it ends before the end of the term. When you don’t renew, your coverage stays in place until the end of the term.
How much notice you get depends on your state. In New Hampshire, an insurer generally has to give you at least 45 days’ written notice before a mid-term cancellation or a non-renewal takes effect (10 days for nonpayment, or for a new policy in its first 90 days). Once a New Hampshire policy has been in force for 90 days, mid-term cancellation is limited to specific reasons, so roof concerns more often show up as a non-renewal. In Connecticut, a mid-term cancellation generally requires at least 30 days’ written notice (10 days for nonpayment), and a non-renewal requires at least 60 days’ notice.
The sense of urgency changes a lot. Cancellation puts immediate pressure on you to avoid a lapse in coverage, while non-renewal gives you time to plan.
- Cancellation: shorter time frame, more important
- Not renewing: more time, but still needs to be done
- Different states and insurance companies have different notice periods.
- Both need to deal with the roof’s underlying condition.
From an advisory point of view, the type of notice should help you decide what to do next. If you don’t know the timeline, you might make decisions too quickly.
What Insurance Companies Look for in a Roof
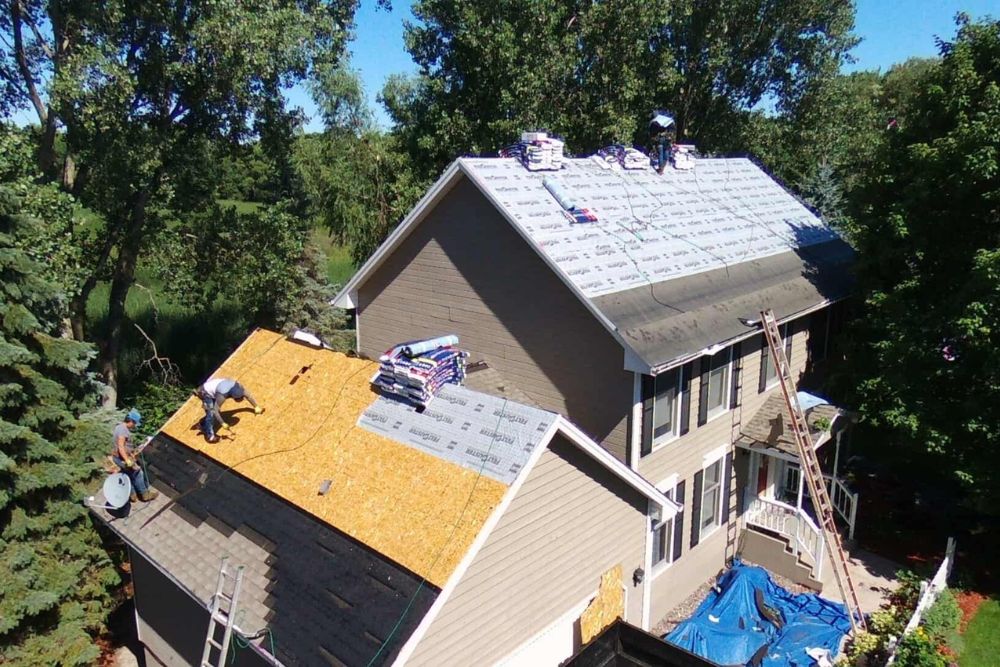
Not just age, but also how long the roof will last and how risky it is overall, are taken into account by insurance companies. A newer roof that isn’t in good shape may be flagged more quickly than an older roof that is.
For instance, a 12-year-old roof that isn’t draining properly and shows signs of wear may be more of a worry than a 17-year-old roof that has been well-maintained and documented.
Inspectors usually check:
- Age vs remaining life
- Visible condition (shingles, flashing, sagging)
- Repair history (patches, inconsistencies)
- Storm exposure (wind, hail, coastal conditions)
They also review patterns. Multiple repairs in the same area may suggest ongoing issues rather than isolated damage. In many cases, coverage decisions become stricter as roofs age, especially once they approach the later stages of their expected lifespan.
At Portsmouth Atlantic Insurance, we often explain that inspections are not pass or fail in the traditional sense. They are evaluations of risk over time.
Understanding what insurers look for helps you respond more effectively. It also helps avoid unnecessary repairs that may not address the actual concern.
Roof Issues That Commonly Trigger Cancellation
Certain roof conditions consistently lead to policy cancellation because they signal increasing risk. These are not always major failures, but patterns that suggest deterioration.
For example, a roof with curling shingles and uneven patches may still function, but those signs indicate material fatigue and inconsistent repairs. Insurers interpret that as a higher likelihood of future claims.
Common triggers include:
- Wear and deterioration (granule loss, curling, moss)
- Structural concerns (sagging, soft spots, decking issues)
- Repeated patchwork repairs in the same areas
Patchwork repairs are particularly important. They can signal that the roof has been addressed multiple times without resolving the underlying issue.
From a risk standpoint, these conditions are cumulative. One issue alone may not lead to cancellation, but several together often do.
Recognizing these triggers early allows homeowners to address concerns before they affect coverage.
What Happens After Your Policy Is Cancelled
When a policy is cancelled due to roof condition, the timeline becomes critical. Most homeowners have a limited window before coverage ends: at least 45 days’ notice in New Hampshire, or at least 30 days for a Connecticut mid-term cancellation (10 days in either state if the reason is nonpayment).
For example, a homeowner who delays action after receiving a notice may find themselves without coverage, forcing the lender to step in.
Mortgage lenders require continuous insurance because the home secures the loan. If coverage lapses, the lender may place insurance on the property.
- This is called force-placed insurance
- It is typically more expensive
- It often provides less comprehensive protection
Federal mortgage servicing rules require your servicer to send a written notice at least 45 days before charging you for force-placed coverage, followed by a reminder. Once those notices run out, there’s little room to negotiate. The key risk is not just losing your policy, but losing control over your coverage.
Understanding this timeline helps prevent unnecessary financial and coverage disruptions. At this stage, the risk isn’t just losing coverage — it’s losing control over your options. Insurers also look closely at claims patterns over time, not just individual events.
If you’ve received a notice and the end date is coming up, this is the point where a coverage review becomes time-sensitive, especially if you want to avoid force-placed insurance.
Reviewing your options early can help you stay in control of both cost and coverage.
What to Do Next (Step-by-Step, Calm Guidance)
If your policy has been cancelled, the next steps should be deliberate, not rushed. Acting without clarity can lead to unnecessary costs.
For example, replacing a roof immediately without confirming the insurer’s concern may not resolve the issue if documentation or inspection standards are the real problem.
Start with:
- Confirm the reason in writing
- Get an independent roof inspection
- Document all findings and repairs
- Prepare for re-application with updated information
An independent inspection is especially valuable. It provides an objective view and helps determine whether repair or replacement is appropriate.
At Portsmouth Atlantic Insurance, we often guide homeowners through this process to ensure each step aligns with what insurers actually require.
If you’re unsure how these steps apply to your situation, getting guidance before taking action can prevent unnecessary costs.
Many homeowners find it helpful to walk through their specific case with an advisor before committing to repairs or replacement.
Repair vs Replacement: How to Decide
The decision between repair and replacement should be based on long-term insurability, not just immediate cost. A short-term fix may not satisfy underwriting requirements.
For example, repairing a section of a 22-year-old roof may address visible damage, but insurers may still view the roof as nearing the end of its useful life. Before deciding, it helps to understand when insurance may contribute to roof replacement versus when the cost falls entirely on the homeowner.
Consider:
- Repair is appropriate when damage is isolated and the roof has remaining life
- Replacement is often required when age and condition combine to increase risk
A repair may restore function, but not confidence from an insurer’s perspective.
The goal is not just to fix the roof, but to restore insurability. This often requires looking beyond immediate costs and focusing on long-term stability.
How to Get Covered Again After a Roof Issue
Getting coverage again depends on demonstrating reduced risk. Insurers will typically require documentation showing the roof’s condition has improved.
For example, a homeowner who provides inspection reports, photos, and proof of repairs is more likely to secure coverage than one who only states the issue has been addressed.
Expect insurers to ask for:
- Recent inspection reports
- Proof of repairs or replacement
- Photos of the current roof condition
Independent agents can help navigate this process by identifying carriers more open to certain risk profiles.
At Portsmouth Atlantic Insurance, we work with multiple carriers and can help match your situation with appropriate options, especially after a cancellation.
Preparation and documentation are often the difference between approval and denial.
How to Prevent This Situation in the Future
Preventing cancellation starts with understanding how insurers evaluate risk before renewal. Waiting until a notice arrives limits your options.
For example, a homeowner who schedules a roof inspection before renewal can address minor issues early, avoiding larger concerns later.
Prevention steps include:
- Conducting pre-renewal inspections
- Keeping maintenance records and receipts
- Addressing minor issues before they escalate
- Planning upgrades based on roof age and condition
Documentation is often overlooked but highly valuable. It provides evidence of care and maintenance, which can influence underwriting decisions.
A proactive approach helps maintain both coverage and flexibility over time.
Common Misunderstandings Homeowners Have
Many homeowners misunderstand how insurers evaluate roofs, leading to unexpected cancellations. For example, a roof with no leaks may still be flagged if it shows signs of wear or repeated repairs. Insurers are assessing future risk, not current performance.
Common misconceptions include:
- “No leak means no problem”
- “Age alone determines insurability”
In reality, condition, maintenance, and repair history often matter as much as age. Many of these same risk factors also influence why premiums increase over time, even before a cancellation occurs.
Other Reasons a Home Insurer May Cancel or Not Renew
A roof is one of the most common reasons, but it isn’t the only one. Here are the others we see, and what each one usually means for you.
- A change in how the carrier sees your risk. New information about the property, such as a new flood zone designation or a change in the carrier’s view of local weather, can lead to a non-renewal even when nothing about your house has changed.
- Several claims in a short period. A run of claims can flag a policy, even when each claim was legitimate.
- Missed payments. Most carriers allow a grace period, but it varies. If you miss a payment, check the date on your notice right away.
- The home’s overall condition. Beyond the roof, things like old wiring, failing plumbing or unsafe steps and railings can lead a carrier to step back until they’re fixed.
- Business decisions. Sometimes a carrier changes where or what it writes, and it has nothing to do with you or your home.
If the Reason Isn’t Your Roof
- Read the notice closely. It should state the reason and the date coverage ends.
- Call the carrier if it’s fixable. A missed payment or a repair you’ve already finished may be enough to keep the policy in place.
- Start shopping early. Don’t wait for the end date. A gap in coverage can cause problems with your lender and makes the next policy harder to place.
- Keep good records. Receipts, photos and inspection reports help the next carrier see that the issue has been handled.
We work with 40+ carriers, so if one company says no, we can often find another that fits your home. Understanding these distinctions helps avoid surprises and supports better long-term decisions.
Sources
- New Hampshire General Court, RSA 417-B:4 – Cancellation; Refusal to Renew; Notice
- New Hampshire General Court, RSA 417-B:3 – Cancellation Grounds
- Connecticut General Assembly, Conn. Gen. Stat. § 38a-316g (cancellation of homeowners insurance policies)
- Connecticut General Assembly, Conn. Gen. Stat. § 38a-307 (standard fire policy cancellation terms)
- Connecticut General Assembly, Conn. Gen. Stat. § 38a-323 (notice of nonrenewal)
- Consumer Financial Protection Bureau, What can I do if my mortgage servicer is charging me for force-placed homeowner’s insurance?
- Federal Reserve (Regulation X), 12 CFR 1024.37 – Force-placed insurance
FAQs
1. Why would homeowners insurance cancel a policy because of the roof?
Yes, insurers cancel policies when the roof presents a high risk of future claims. This includes aging materials, visible wear, or repeated repairs. The decision is based on risk assessment, not just current damage, meaning a roof can be functional but still considered uninsurable.
2. Can insurance drop you for an old roof?
Yes, but age alone is not always the reason. Insurers look at remaining useful life and condition. A well-maintained older roof may still qualify, while a newer roof in poor condition may not.
3. What happens if insurance cancels your policy due to roof issues?
You typically have a limited time to secure new coverage: at least 45 days’ notice in New Hampshire, or at least 30 days for a mid-term cancellation in Connecticut (10 days in either state for nonpayment). If you do not, your mortgage lender may place force-placed insurance, which is more expensive and offers less protection.
4. Can I get homeowners insurance with a bad roof?
Yes, but options may be limited. Insurers usually require proof of repairs or replacement. Some carriers may offer temporary or conditional coverage depending on the situation.
5. Should I repair or replace my roof after cancellation?
It depends on the roof’s age and condition. Repairs may be enough for isolated issues, but older roofs often require full replacement to meet underwriting standards and restore insurability.
6. How do I prove my roof is insurable again?
Provide inspection reports, photos, and documentation of repairs or replacement. Clear evidence of improved condition helps insurers reassess risk and approve coverage.
7. Myth vs Fact: If my roof isn’t leaking, insurance shouldn’t cancel my policy
Myth. Insurers focus on future risk, not current leaks. A roof can be dry but still considered likely to fail based on age, wear, or repair history.
8. Myth vs Fact: Replacing part of the roof is always enough
Myth. Partial repairs may not address underlying issues. Insurers often look for consistency in condition, and patchwork repairs can signal ongoing risk.
9. What happens if my homeowners insurance drops me?
Your insurer has to send written notice before a cancellation or non-renewal takes effect, and the notice should say why. Read it right away, ask whether the problem can be fixed in time to keep the policy, and line up replacement coverage before the end date so there is no gap. If you have a mortgage, your lender will need proof of new coverage, which is covered in what happens to your mortgage if homeowners insurance is cancelled.
10. Why else might an insurer cancel or non-renew a homeowners policy?
Besides the roof, common reasons include non-payment, several claims in a short period, other property condition problems, and a carrier deciding to write less business in an area. Because we compare 40+ carriers, a non-renewal from one company doesn’t mean others won’t write the home.
Get Clarity on Your Roof and Insurance Options Before Time Runs Out
A homeowners insurance cancellation due to roof condition is a signal, not just a setback. Understanding what insurers see, how timelines work, and how to respond helps you move forward with clarity.
If your policy has been cancelled or you’re approaching renewal, the next step isn’t just fixing the roof — it’s making sure your next move actually restores coverage. A quick review of your situation can help you understand your options, avoid unnecessary costs, and move forward with clarity.